
Blog
In this dedicated blog page, we invite you to explore a wealth of knowledge, expertise, and inspiration that transcends traditional boundaries.
INXY Raises $7M to Expand Cross-Border Payment Infrastructure
INXY has secured new funding to continue building its global payments platform. The total round reached $7M. The company focuses on stablecoin infrastructure for businesses. Its tools help companies accept crypto and send payouts while keeping accounting in fiat.
INXY has secured new funding to continue building its global payments platform. The total round reached $7M.
The company focuses on stablecoin infrastructure for businesses. Its tools help companies accept crypto and send payouts while keeping accounting in fiat.
This funding comes at a time when global payments are changing. Traditional rails are slow and expensive. Cross-border transfers often take days and include multiple intermediaries.
Stablecoins offer a different path. They move value quickly and directly. They reduce friction in international transactions. Many businesses are starting to explore this model.
INXY builds infrastructure for this shift. The goal is simple. Let companies use crypto without becoming crypto companies.
The platform supports mass payouts, payment acceptance, and automated conversion. Funds can be sent globally and settled in EUR or USD.
The company has already processed over $2B in annual stablecoin volume. This shows growing demand for alternative payment rails.
The new capital will be used to:
– Expand the payments infrastructure.
– Strengthen compliance and regulatory alignment.
– Grow the team and product capabilities.
Regulation is also shaping the market. In Europe, frameworks like MiCA are creating clearer rules for crypto services. This makes it easier for businesses to adopt compliant solutions.
INXY positions itself in this new environment as a regulated infrastructure provider. It operates under EU and Canadian frameworks and focuses on low-risk business use cases.
The company believes the future of payments will be stablecoin-based, compliant, and invisible to the end user.
The work ahead is not about hype. It is about making payments simple, reliable, and global.
Articles
How to Accept USDT Payments on Your Website
Accepting USDT is a two-day integration and a six-month operational commitment. This guide covers the full path from sandbox to production: choosing between direct wallet, crypto settlement and fiat settlement, picking networks and confirmation depth, a nine-step integration sequence, five webhook rules that prevent double-crediting, chart-of-accounts mapping through a settlement clearing account, and the failures that show up after go-live.
Accepting USDT is a two-day integration and a six-month operational commitment. The integration is the easy part: a checkout call, a webhook endpoint, a settlement report. What takes longer is everything after go-live — underpayments, wrong-network sends, a webhook that fired three times, and a finance team asking why the settlement total does not match the order total. This guide covers the full path: sandbox to production, webhook handling that survives retries, reconciliation, chart-of-accounts mapping, and the failures that show up in week three.
Decide the model first: direct wallet, gateway, or converted settlement
This decision determines everything downstream, and reversing it later means re-doing the reconciliation.
Direct wallet acceptance. You generate an address, the customer sends USDT, you hold USDT. No provider fee — but you now own address generation, network monitoring, confirmation logic, underpayment handling, refunds, key custody, KYT and sanctions screening. For most businesses that is not a saving; it is an unstaffed payments team.
Gateway with crypto settlement. The provider handles checkout, addresses and confirmation, then settles USDT to your wallet. You keep the token, the price exposure and a cryptoasset on your balance sheet.
Gateway with fiat settlement. Same checkout flow, but the provider auto-converts at confirmation and settles EUR or USD to your bank. Your ledger never holds a cryptoasset and your exposure window is minutes rather than days.
For most merchants the third option is correct, and the reason is not technical: the first two push a treasury and compliance function into a company that did not plan to have one. Crypto payment gateway vs processor sets out how the roles differ. The rest of this guide assumes a gateway integration with fiat settlement — the flow INXY Payments runs across 20 supported cryptocurrencies with next-day bank settlement.
Pick the networks before you write code
USDT is one token on several networks, and they are not interchangeable. A customer who sends TRC-20 USDT to an ERC-20 address has lost the funds, and no amount of support can recover them.
| Network | Block time | Practical finality | Typical merchant use |
|---|---|---|---|
| Tron (TRC-20) | 3 seconds | Solidified once at least 19 of 27 active super representatives have produced a block at that height or above — in practice about 1 minute (TRON developer documentation) | Default for low-value, high-volume checkout and for Asia/LatAm payers |
| Ethereum (ERC-20) | 12-second slots, 32 slots per epoch (6.4 minutes) | Finalised across checkpoint epochs — roughly 13 minutes in practice (ethereum.org) | Higher-value payments, counterparties who require it |
| BNB Smart Chain (BEP-20) | Sub-second to seconds | Provider-defined confirmation depth | Cost-sensitive alternative where payers already hold BEP-20 |
| Polygon | Seconds | Provider-defined confirmation depth | Cost-sensitive, increasingly requested |
The practitioner's rule: support the networks your payers actually use, not every network you can. Each extra network is another address type, confirmation rule, support queue and reconciliation column. Start with two. How USDT network fees compare has the cost detail.
Confirmation depth is a commercial decision, not a technical one. Crediting at one confirmation is fast and carries reorg risk; waiting for finality is safe and costs the customer minutes. For instantly delivered digital goods most merchants credit at the provider's standard depth; for anything irreversible and high-value, wait for finality. Decide it explicitly and check that your provider's default matches.
The integration sequence: sandbox to production in nine steps
- Complete KYB before you write anything. Gateway onboarding requires company documents, UBO identification, a description of your business model and often your website in a reviewable state. It is the longest-lead item in the project and teams routinely start it last. How to verify a merchant account sets out what is collected.
- Get sandbox credentials and read the invoice lifecycle. Every gateway models a payment as an object with states — created, pending, underpaid, confirmed, expired, failed. Map those states to your own order states on paper before you write code. Most integration bugs are state-mapping bugs.
- Create a payment on the server side, never the client. The amount, currency, order reference and callback URL are set by your backend. A client-settable amount is an open invitation, and it is the single most common security defect in crypto checkout integrations.
- Handle the rate lock window explicitly. The gateway quotes a USDT amount against your fiat price and holds it for a fixed window. If the customer pays after expiry, the payment arrives short or long in fiat terms. Display the countdown, and decide in advance whether an expired-but-paid invoice is auto-recredited or manually reviewed.
- Build the webhook endpoint before the checkout page. It is the part that carries the risk, and it needs to exist before you can test anything end to end. Details in the next section.
- Test the failure cases, not the happy path. In sandbox, deliberately produce: an underpayment, an overpayment, a payment after invoice expiry, a duplicate webhook delivery, an out-of-order webhook delivery, and a webhook your endpoint rejects with a 500. If you have not seen all six in sandbox, you will see them in production instead.
- Wire up the settlement report and hand it to finance before go-live. Not after. If the export does not carry, per row, the order reference, the gross fiat amount, the fee, the FX rate applied and the settlement date, your month-end will not close cleanly. This is the step teams skip and regret.
- Go live with one network and a payment cap. Cap the maximum invoice value for the first two weeks. It converts a potential six-figure incident into a three-figure one while your confirmation and reconciliation logic proves itself.
- Reconcile manually for one full cycle. Match every settlement line to an order by hand for the first month. It is how you find the edge case in your state mapping while the volume is still small enough to fix.
Webhook handling: five rules that prevent the expensive bugs
The webhook is where a payment integration succeeds or quietly breaks. Treat it as an untrusted network endpoint that will be called more than once, out of order, and occasionally by someone who is not your provider.
1. Verify the signature before parsing anything. Compute the expected signature over the raw request body — not a re-serialised object, because re-serialisation changes byte order and the signature will not match — and compare in constant time. Reject and log failures.
2. Make the handler idempotent. Key on the provider's payment identifier, not your order ID. Record processed identifiers and return success without re-processing. Webhook delivery is at-least-once by design, so retries are normal, and a non-idempotent handler will credit the same order twice.
3. Never treat the payload amount as your source of truth. Verify server-side against the provider's API before fulfilling. A signature proves the message came from your provider; fetching the object proves the current state.
4. Respond fast, process asynchronously. Return 2xx as soon as the event is persisted, then fulfil on a queue. Inline fulfilment times out under load, the provider retries, and you are back to rule two.
5. Do not assume ordering. A confirmed event can arrive before the pending event preceding it. Drive order state from the event's own state field and a timestamp, never from arrival order.
And make sure the endpoint is reachable. IP allowlists, WAF rules and leftover staging basic-auth are a recurring go-live failure. Confirm delivery from the provider's dashboard on day one, not from your own logs.
Reconciliation and chart-of-accounts mapping
This is the part that determines whether your finance team supports the project in month three.
With fiat settlement, a USDT payment produces three distinct economic events that arrive at different moments: the customer's on-chain payment, the conversion to fiat, and the bank settlement. If your ledger treats them as one event, you will carry an unexplained variance every month.
A mapping pattern that works in practice:
| Event | Debit | Credit |
|---|---|---|
| Invoice issued | Trade receivable | Revenue |
| Payment confirmed on-chain, converted | Settlement clearing account (asset) | Trade receivable |
| Provider fee applied | Payment processing fees (expense) | Settlement clearing account |
| Conversion difference vs invoiced rate | FX gain/loss | Settlement clearing account |
| Bank settlement received | Bank | Settlement clearing account |
The clearing account is the control. It should net to zero once every batch has settled, and a persistent non-zero balance tells you exactly where the break is — unsettled, unmatched, or mis-rated. Without it, differences disappear into revenue and nobody finds them until audit.
Four requirements to put in the provider evaluation, not discover afterwards:
- Row-level settlement export with order reference, gross amount, fee, FX rate and settlement timestamp on every line.
- A stable order reference that survives from invoice creation to bank settlement. If the reference is lost at conversion, matching becomes manual.
- Consistent timezone handling. A settlement timestamp in the provider's timezone against orders in yours produces month-end cut-off differences every single period.
- Fees itemised, not netted. A net figure hides the fee and makes cost analysis impossible.
Accounting treatment for digital assets varies by jurisdiction and by reporting framework, and it changes. The mapping above is an operational pattern, not accounting or tax advice — confirm the treatment with your own auditors before you book it.
What breaks after go-live
Underpayments. The customer sends slightly less than invoiced, usually because their wallet deducted the network fee from the amount rather than adding it. Decide the policy before it happens: auto-accept below a tolerance threshold, hold for review above it, and make the threshold a configuration value rather than a code change.
Wrong-network sends. The dominant support burden in USDT acceptance. Mitigate at the interface: show the network prominently, use network-specific QR codes, never present a bare address without its network label, and put the warning next to the address rather than at the bottom of the page.
Duplicate order creation. A customer refreshes checkout and generates a second invoice for the same order, then pays the first one. Your order is now linked to an unpaid invoice. Key invoice creation on the order ID and return the existing invoice instead of creating a new one.
Refunds are outbound payments, not reversals. There are no chargebacks on this rail — a structural property, since there is no card scheme representment process — which removes a large category of loss. It also means a refund is a new payout to an address the customer supplies, with its own screening, its own network fee and its own operational process. Design the refund flow during integration, not on the first request.
Expired-invoice payments. A customer pays an hour after the rate window closed and the fiat value no longer matches the invoice. Without a written policy this lands on a support agent with no authority to decide it.
Staging credentials that outlive staging. Sandbox keys left in a production environment variable, or a production endpoint still pointing at a dev URL. Verify both directions on go-live day.
The decision framework
Do not start with the API documentation. Start with three questions, in this order:
- Where do your payers sit, and what network do they already use? A payer-data question, not an engineering one, and it settles which networks you support.
- Do you want a cryptoasset on your balance sheet? If no — and for most merchants the answer is no — the model is fiat settlement, which removes most of the treasury and accounting complexity before it exists.
- Who owns reconciliation? If the answer is “we'll work it out after launch,” involve finance now. Every integration that goes badly goes badly at month-end, not at go-live.
Get those three right and the integration is a short piece of work. Get them wrong and no amount of clean code fixes it.
Where this is not the right answer: if you sell primarily to domestic consumers in a well-banked market with working card acceptance and a low decline rate, adding USDT acceptance will produce a small share of volume and a real amount of operational overhead. Stablecoin acceptance earns its keep when cards are failing you — regional declines, chargeback ratios threatening your acquirer relationship, or cross-border settlement measured in days. If none of those describe you, the honest answer is that this is not your priority this quarter.
If they do describe you, the fastest path is a sandbox integration against your real checkout flow rather than a proof of concept. Get started for credentials, or book a demo if the reconciliation model is the part you need to settle first. For the developer-side detail, integrating a crypto payment API goes deeper on the API surface, and checkout design that converts covers the payer-facing half.
This article describes regulatory and market conditions for general information. It is not legal, tax, or financial advice — INXY Payments is a payment infrastructure provider, not a law or accountancy firm, and decisions with regulatory consequence should be reviewed by qualified counsel in the relevant jurisdiction.
FAQ
How do I accept USDT payments on my website?
Integrate a crypto payment gateway: create the payment server-side with the fiat amount and order reference, display the gateway's checkout with the correct network, verify the signed webhook when the payment confirms, and settle either in USDT or converted to fiat. Most merchants choose fiat settlement so no cryptoasset touches the balance sheet.
Which USDT network should I accept?
Support the networks your payers already use rather than all of them. TRC-20 is the common default for low-value, high-volume checkout, with ERC-20 added where counterparties require it. Each extra network adds address handling, confirmation rules, support load and a reconciliation column, so start with two.
How long does a USDT payment take to confirm?
It depends on the network and your chosen confirmation depth. On Tron, a block is solidified in about a minute once at least 19 of 27 active super representatives have built on it. On Ethereum, finality is reached across checkpoint epochs — roughly 13 minutes. Many merchants credit earlier and accept the residual risk.
What happens if a customer underpays?
The gateway marks the payment underpaid rather than confirmed. Set a tolerance threshold in advance: auto-accept small shortfalls, hold larger ones for review. Underpayment is usually caused by a wallet deducting the network fee from the sent amount rather than adding it, so it is common rather than exceptional.
Are there chargebacks on USDT payments?
No. On-chain settlement has no card scheme representment process, so the chargeback category of loss does not exist. Refunds still do — but a refund is a new outbound payment to an address the customer supplies, with its own screening and network fee, so the refund flow needs designing during integration.
How do we reconcile USDT payments in our accounting?
Route everything through a settlement clearing account. The on-chain payment, the conversion and the bank settlement are three separate events arriving at different times; the clearing account should net to zero once a batch has settled, and any residual balance points straight at the break. Require a row-level export with fee and FX rate per line.
TRC-20 vs ERC-20 vs BEP-20: What USDT Really Costs
TRON meters Energy, Ethereum runs a gas auction, BNB Chain does both cheaply — so a fee table comparing them flattens the thing that matters. What a USDT transfer actually costs on each, how fast it is final, and which network to send a payout batch on.
The TRC20 vs ERC20 question is usually answered with a fee table and left there. That answer is incomplete in a way that costs money at volume: the three networks price transactions using three different mechanisms, reach settlement finality on three different timescales, and fail in three different ways when they get busy. If you are sending one transfer, pick the cheapest. If you are sending a payout batch of four hundred, the cheapest network is frequently the wrong one, and this article explains exactly when.
What the three standards are
Snippet target. TRC-20, ERC-20 and BEP-20 are token standards on three separate blockchains — TRON, Ethereum and BNB Smart Chain. The same USDT exists as a different token contract on each, and the balances are not interchangeable without a bridge or an exchange. Choosing a network means choosing that chain's fee model, confirmation speed and liquidity, not a different kind of dollar.
The critical consequence: a USDT balance is chain-specific. Sending BEP-20 USDT to a TRC-20 address is not a slow transfer, it is a transfer to a different network entirely, and whether the funds are recoverable depends on who controls the keys at the destination.
The fee models are not comparable
This is the part fee tables flatten. Each chain charges for a different scarce resource.
Ethereum (ERC-20) — an auction for block space
Ethereum's total fee is "units of gas used * (base fee + priority fee)" (ethereum.org). The base fee is set by the protocol and adjusts with demand: it "will increase or decrease by a maximum of 12.5% per block if the target block size is above or below the target", and once the block is created "this base fee is 'burned', removing it from circulation" (ethereum.org).
A standard ERC-20 transfer consumes roughly 65,000 gas, and around 90,000 from an address that has never held the token (Eco, data pulled 13 May 2026). The same transfer therefore costs approximately $0.30 at 2 gwei, $1.50 at 10 gwei, $4.50 at 30 gwei and $12 at 80 gwei (Eco, 13 May 2026).
The operational point is not the average — it is the variance. A 12.5% per-block move compounds fast. Your treasury model has to survive the 80 gwei day, not the 2 gwei day.
TRON (TRC-20) — a resource you rent, not a price you pay
TRON does not run a gas auction. It meters two resources: Bandwidth, which "covers the byte size of transactions stored on-chain", and Energy, which "covers the computation the TVM performs when executing a smart contract" (TRON developer docs). Every account gets "a free 600 Bandwidth daily quota" and no free Energy at all. A USDT transfer needs roughly 345 Bandwidth, so the free quota covers the Bandwidth leg of about one transfer a day and contributes nothing to the Energy leg, which is where the money is.
A USDT TRC-20 transfer consumes roughly 64,285 Energy to a recipient already holding USDT, and roughly 130,285 Energy to a recipient whose USDT balance is zero.
The doubling is triggered by a zero balance, not by a new address — and this is where most articles get it wrong. The trigger is not history but the balance at the moment of the transfer: if the recipient has never received USDT or its USDT balance is currently zero, the write creates a new storage slot in the token contract rather than updating an existing one, and storage creation on the TVM costs roughly double. A contractor who sweeps their wallet to an exchange after every payment therefore lands on the expensive tier every single time, not once. In a payout batch to freelancers — who by definition empty their wallets — the 130,285-Energy tier is the default case, not the exception. Budget the batch on the high tier and treat the low tier as upside.
Three ways to pay for Energy, and what each actually costs
| Route | What you pay per transfer | What it costs you elsewhere |
|---|---|---|
| Burn TRX | ~6.77 TRX to a funded recipient, ~13.37 TRX to a zero-balance one (≈$1.87 / $3.70 at TRX $0.2766, 10 Feb 2026) | Nothing locked, nothing to manage. Highest per-transfer cost by a wide margin. |
| Stake TRX yourself | No marginal TRX while your Energy allowance lasts | A large locked position and a 14-day exit. A treasury decision, not a fee setting. |
| Rent Energy from a resource provider | ~2.93 TRX per 65,000 Energy for a one-hour rental, published as “around 60% cheaper than burning TRX” (rate card captured 14 September 2026) | An unregulated third party inside your payment execution path. |
Self-staking is a treasury position, not a fee discount. Energy from staking is allocated by "the proportion of your staked TRX relative to the total TRX staked across the entire network for that resource" (TRON developer docs). There is no fixed TRX-per-Energy rate — the amount you must lock to cover a given number of transfers moves with how much everyone else has staked, so any figure you read is a snapshot of a market, not a protocol constant. At the ratios prevailing through 2026, covering a single 65,000-Energy transfer per day has required staking on the order of 13,000 TRX. Exit is slow: "The unstaked TRX enters a 14-day pending period before it can be withdrawn" (TRON developer docs). Staked TRX does carry TRON Power at 1 TP per TRX, but the docs are blunt that "Unused TP earns you nothing — voting is what generates rewards", so any offset against the locked capital requires actively voting for Super Representatives and is not a return on the stake itself. TRONSCAN's Resource Calculator will price a given stake against current network conditions before you commit.
Renting Energy is the part almost nobody writes up. A market exists of operators who stake TRX at scale and resell the resulting Energy, delegated to your address for a fixed window, priced in TRX well below the burn cost. For a business running a few hundred payouts a month this is materially the cheapest route, and unlike staking it locks up no capital.
Here is what a rental vendor will not put on their pricing page. You are inserting an unregulated counterparty into the execution path of a payment. The delegation itself is benign, but your batch now depends on that operator being available at the moment it runs, you are paying them in TRX, and for a regulated payment business that dependency sits inside a process compliance will eventually ask about. Rented Energy is usually the right answer for a merchant optimising their own treasury. It is a much harder answer for a licensed provider executing client payouts at volume — which is one reason INXY abstracts the resource question away entirely rather than handing the merchant a rental dependency to manage.
TRON also caps contract execution with a fee_limit, and the docs are explicit that "a sufficient account balance alone does not guarantee execution". A batch can fail on a fee limit set months earlier while the account is fully funded.
BNB Smart Chain (BEP-20) — cheap, fast, and structurally different
BEP-20 uses an Ethereum-style gas model at much lower prices. A USDT BEP-20 transfer consumes "around 50,000 to 65,000 gas" at "typical gas prices of 1 to 5 gwei in BNB", putting end-to-end fees in "the $0.10 to $0.30 range for a basic transfer at retail demand levels" (Eco, 2026).
The chain itself changed materially in 2025. The Maxwell hardfork went live on mainnet on 30 June 2025, "reducing block times from 1.5 seconds to 0.75 seconds", with "Fast Finality... now achievable in ~1.875 seconds" (BNB Chain, 2025). That is the fastest published finality of the three.
Comparison table
| TRON (TRC-20) | Ethereum (ERC-20) | BNB Smart Chain (BEP-20) | |
|---|---|---|---|
| Fee mechanism | Energy + Bandwidth — burned, self-staked, or rented | Gas auction: base fee (burned) + priority fee | Gas auction at low gas prices |
| Typical USDT transfer cost | Burn: ~6.77 TRX to a funded recipient, ~13.37 TRX to a zero-balance one (≈$1.87 / $3.70 at TRX $0.2766, 10 Feb 2026). Rented Energy: ~2.93 TRX per 65,000 Energy (14 Sep 2026). Self-staked: no marginal cost, large locked position | ~$0.30 at 2 gwei to ~$12 at 80 gwei, 65,000 gas (13 May 2026) | ~$0.10–$0.30, 50,000–65,000 gas at 1–5 gwei (2026) |
| Cost predictability | High if staked or rented; moderate if burned | Low — base fee moves up to 12.5% per block | High |
| Block time | 3 seconds | 12 seconds (one slot) | 0.75 seconds |
| Practical finality | Solidified once ≥19 of 27 Super Representatives have built on it, “about 1 minute” | Checkpoint-based; epochs of 32 slots ≈ 6.4 minutes, so finality lands near 13 minutes | Fast Finality “~1.875 seconds” |
| Reversal cost to an attacker | Requires colluding SRs | “at least one-third of the total supply of staked ETH” | BFT fast-finality guarantees |
| Where volume actually is | Dominant settlement rail: 60–80% of real-economy stablecoin flows, though share fell from ~74% (Jan 2025) to ~60% (end 2025) | Rising share, favoured by regulated institutions | Rising share alongside Solana and Polygon |
| Best for | High-frequency, price-sensitive payouts with deep USDT liquidity | High-value settlement where counterparties demand Ethereum | Fast, cheap transfers where counterparty accepts BNB Chain |
Chain-share figures: BCG / Allium, Stablecoin Payments: The Truth Behind the Numbers. Cost figures carry their own capture dates above; verify against a live explorer before committing a large batch.
Finality time by chain, and what "confirmed" means
"Confirmed" and "final" are different states, and conflating them is how a reconciliation goes wrong.
- TRON produces a block every 3 seconds across 27 Super Representatives. A block is solidified "once at least 19 distinct active SRs have each produced a block at that height or above", which takes "about 1 minute" under normal conditions (TRON developer docs). Before solidification, a reorg is possible — the fork rule is "longest chain wins".
- Ethereum divides time "into slots (12 seconds) and epochs (32 slots)" — roughly 6.4 minutes per epoch — and finalises through checkpoint voting, which in practice means about two epochs, near 13 minutes. Once final, reverting a block requires an attacker "to commit to losing at least one-third of the total supply of staked ETH" (ethereum.org). Most exchanges credit USDT ERC-20 deposits after 12 to 32 confirmations, "putting practical settlement in the 3 to 7 minute range" (Eco, 13 May 2026).
- BNB Smart Chain reaches Fast Finality in "~1.875 seconds" post-Maxwell (BNB Chain, 2025).
The number that matters to you is none of these — it is your counterparty's confirmation policy. If the receiving exchange requires 20 confirmations, TRON's one-minute solidification is irrelevant; you wait for their threshold. Ask for it in writing during integration, because it is the actual determinant of when a payout is "done" from the recipient's point of view.
Network fee pass-through: who eats it
Three models exist, and which one you are on decides whether network fees hit your gross margin or your recipients' trust.
- Absorbed by the sender. You pay the network fee on top of the payout amount. Clean for the recipient, and the line lands in your cost base where finance can see it.
- Deducted from the payout. The recipient receives the amount minus the fee. This is the single largest source of "underpayment" support tickets in crypto acceptance, because the invoice and the received amount no longer match.
- Abstracted by the provider. A gateway sponsors gas and prices it into a blended rate. INXY runs this model — the merchant experience is wallet-free, gas-free and blockchain-free — so network volatility becomes the provider's exposure rather than a line on your month-end.
There is no free option among the three. Abstraction moves the variance rather than eliminating it, and a provider carrying it will price it in somewhere. The question to ask is not "do you charge network fees" but "what happens to my rate when Ethereum gas triples for a week".
Read the full network fee comparison → /blog/usdt-network-fees-compared
Mempool congestion and what actually breaks
Ethereum: the stuck transaction. You broadcast at a max fee that made sense, the base fee climbs 12.5% per block, and your transaction sits unmined. Since "the max fee must exceed the sum of the base fee and the tip", a transaction whose ceiling falls below the prevailing base fee waits indefinitely. Replacing it requires a same-nonce transaction at a higher fee, and if your batch submits sequential nonces, one stuck transaction blocks every transaction behind it. This is the classic Friday-afternoon batch failure.
TRON: the exhausted Energy pool. Staked Energy regenerates over time and a rental covers a fixed window. Either way, a batch that runs past its allowance silently switches to burning TRX for the remainder — so a run budgeted at 2–3 TRX per transfer finishes at 7 or 14, and nothing errors to tell you. If the account also lacks TRX, the remaining transfers simply fail. Size the allowance against the zero-balance Energy figure, not the average.
BNB Smart Chain: the false sense of finality. Sub-second blocks make everything feel instantaneous, which encourages treating first inclusion as settlement. It is not; Fast Finality is a separate state roughly 1.875 seconds later. At three transfers per second in a batch loop, the gap between "submitted" and "final" is where double-counting creeps into reconciliation.
All three: the wrong-network send. The most expensive failure is not a fee, it is a USDT transfer sent on the wrong chain to an address that exists on both. Address formats differ between TRON and the EVM chains, which catches most errors — but ERC-20 and BEP-20 share an address format entirely, and a BEP-20 send to an ERC-20 address is a silent, recoverable-only-if-someone-holds-the-key mistake.
Choosing a network for a payout batch
The operational question the other articles skip. Run it in this order.
- Ask the recipients, before anything else. A batch is only as cheap as the network every recipient can actually receive on. One contractor who can only take ERC-20 does not force the whole batch onto Ethereum — it forces you to split the batch.
- Segment by network, then by recipient balance. On TRON, any recipient sitting at a zero USDT balance costs roughly double the Energy — including regulars who sweep their wallet after every payment. Check balances at batch build time rather than assuming returning payees are on the cheap tier.
- Price the batch on today's numbers, not last month's. Check the live base fee before an Ethereum batch. A 400-transfer batch at 65,000 gas each is 26 million gas; at 2 gwei that is trivial and at 80 gwei it is not.
- Decide burn, stake or rent on TRON — and decide it deliberately. Burning is the default and the most expensive. Renting Energy is usually cheapest and locks no capital, at the price of a third party in the payment path. Self-staking wins only at sustained volume and only if you can lock the position for 14 days on exit. Model all three against your float, not against the per-transfer price.
- Set fee ceilings and nonce strategy before you submit. Use non-sequential or parallelised nonces where the provider supports it, so one stuck transaction does not halt the batch. Set fee_limit on TRON deliberately rather than inheriting a default.
- Run screening before broadcast, not after. KYT and sanctions checks that fire after a transfer is on-chain are a remediation exercise, not a control. On our side, screening, auto-conversion and routing all run before payout execution.
- Reconcile on finality, not inclusion. Mark a payout settled when it reaches the chain's finality state and your counterparty's confirmation threshold — whichever is later.
Send a USDT batch by API or CSV → /cryptocurrencies/mass-payout-in-usdt
Common mistakes
Treating TRON's cost as zero, or paying it the expensive way by default. TRON is cheap, not free: the 600 free daily Bandwidth covers the Bandwidth leg of roughly one transfer and no Energy at all. Burning TRX is what happens when nobody decides anything, and it is the most expensive of the three routes. Deciding once — burn, stake or rent — is worth more than any other network optimisation on this page.
Choosing the network before checking liquidity, and assuming the answer is permanent. A cheap transfer into a market where nobody will off-ramp that token is an expensive transfer. TRON's dominance in real-economy flows exists partly because its USDT liquidity is deepest where payouts actually land — but its share fell from about 74% in January 2025 to about 60% by the end of that year as institutional and platform-integrated flows moved toward Ethereum, BNB Smart Chain, Solana and Polygon (BCG/Allium). Review the network mix; do not set it once.
Optimising the network while ignoring the off-ramp. The network fee is often the smallest line in the total cost of a payout. The conversion spread and the fiat settlement route are usually larger. Fixing the cheap line first is a common and expensive habit.
This article describes technical and market conditions for general information. It is not legal, tax, or financial advice — INXY Payments is a payment infrastructure provider, not a law or accountancy firm, and decisions with regulatory consequence should be reviewed by qualified counsel in the relevant jurisdiction.
Decision framework
- High-frequency payouts to contractors, affiliates or suppliers in emerging markets → TRC-20, and stop burning TRX. Rent Energy if you can accept the counterparty; self-stake if volume is sustained and the capital can sit for 14 days on exit.
- Large, low-frequency settlements to institutional counterparties → ERC-20, and price the gas variance in rather than assuming an average.
- Speed-sensitive transfers where the counterparty already runs BNB Chain → BEP-20, but reconcile on Fast Finality, not first inclusion.
- A mixed recipient list → do not pick one network. Split the batch and treat the split as normal operations rather than an exception.
- You do not want to run any of this → network selection, gas abstraction, screening and conversion belong in infrastructure, not in a finance team's spreadsheet.
The decision worth re-running quarterly is which asset and which chain your recipients actually prefer — it moves. See supported currencies and networks → /cryptocurrencies, or talk to our payments team about a batch → /book-a-demo.
FAQ
Is TRC20 or ERC20 cheaper for sending USDT? TRC-20 is normally cheaper. A USDT TRC-20 transfer costs roughly 6.77 TRX to an address already holding USDT if you burn rather than stake, while an ERC-20 transfer ranges from about $0.30 at 2 gwei to about $12 at 80 gwei. The gap widens sharply whenever Ethereum demand spikes, because TRON's cost is far more stable.
Can I send USDT from a TRC-20 address to an ERC-20 address? No. They are separate blockchains and the address formats differ, so most wallets reject the attempt. Moving between them requires a bridge or an exchange that supports both networks. ERC-20 and BEP-20 share an address format, which makes cross-sends between those two possible and genuinely risky.
Which USDT network is fastest? BNB Smart Chain, on published figures. Blocks are produced every 0.75 seconds and Fast Finality is achievable in around 1.875 seconds. TRON solidifies a block in about a minute, and Ethereum finalises in roughly 13 minutes. In practice your counterparty's required confirmation count usually matters more than the chain's own finality.
Why does a USDT transfer cost twice as much to some addresses? Because the recipient's USDT balance is zero. On TRON that costs roughly 130,285 Energy against 64,285, since the contract must create a storage slot rather than update one. It applies to brand-new addresses and to regulars who empty their wallet after every payment — so for freelancer payouts the expensive tier is the normal case.
How much TRX do I need to stake to cover my transfers? There is no fixed rate. TRON allocates Energy by your share of the total TRX staked network-wide, so the requirement moves as others stake more or less. At 2026 ratios, one 65,000-Energy transfer per day has needed on the order of 13,000 TRX staked, and unstaking carries a 14-day pending period. Price it with a resource calculator before committing.
Should I burn, stake or rent Energy on TRON? Burning is simplest and the most expensive per transfer. Renting Energy from a resource provider is normally the cheapest and locks no capital, but puts a third party in your payment path. Self-staking suits sustained volume if you can tolerate the locked position and the 14-day exit. It is a treasury decision, not an engineering setting.
What is network fee pass-through? It is who bears the blockchain fee on a transfer. Either the sender adds it on top, the recipient absorbs it through a reduced payout, or a payment provider sponsors the gas and prices it into a blended rate. The second model is the most common cause of underpayment and reconciliation disputes.
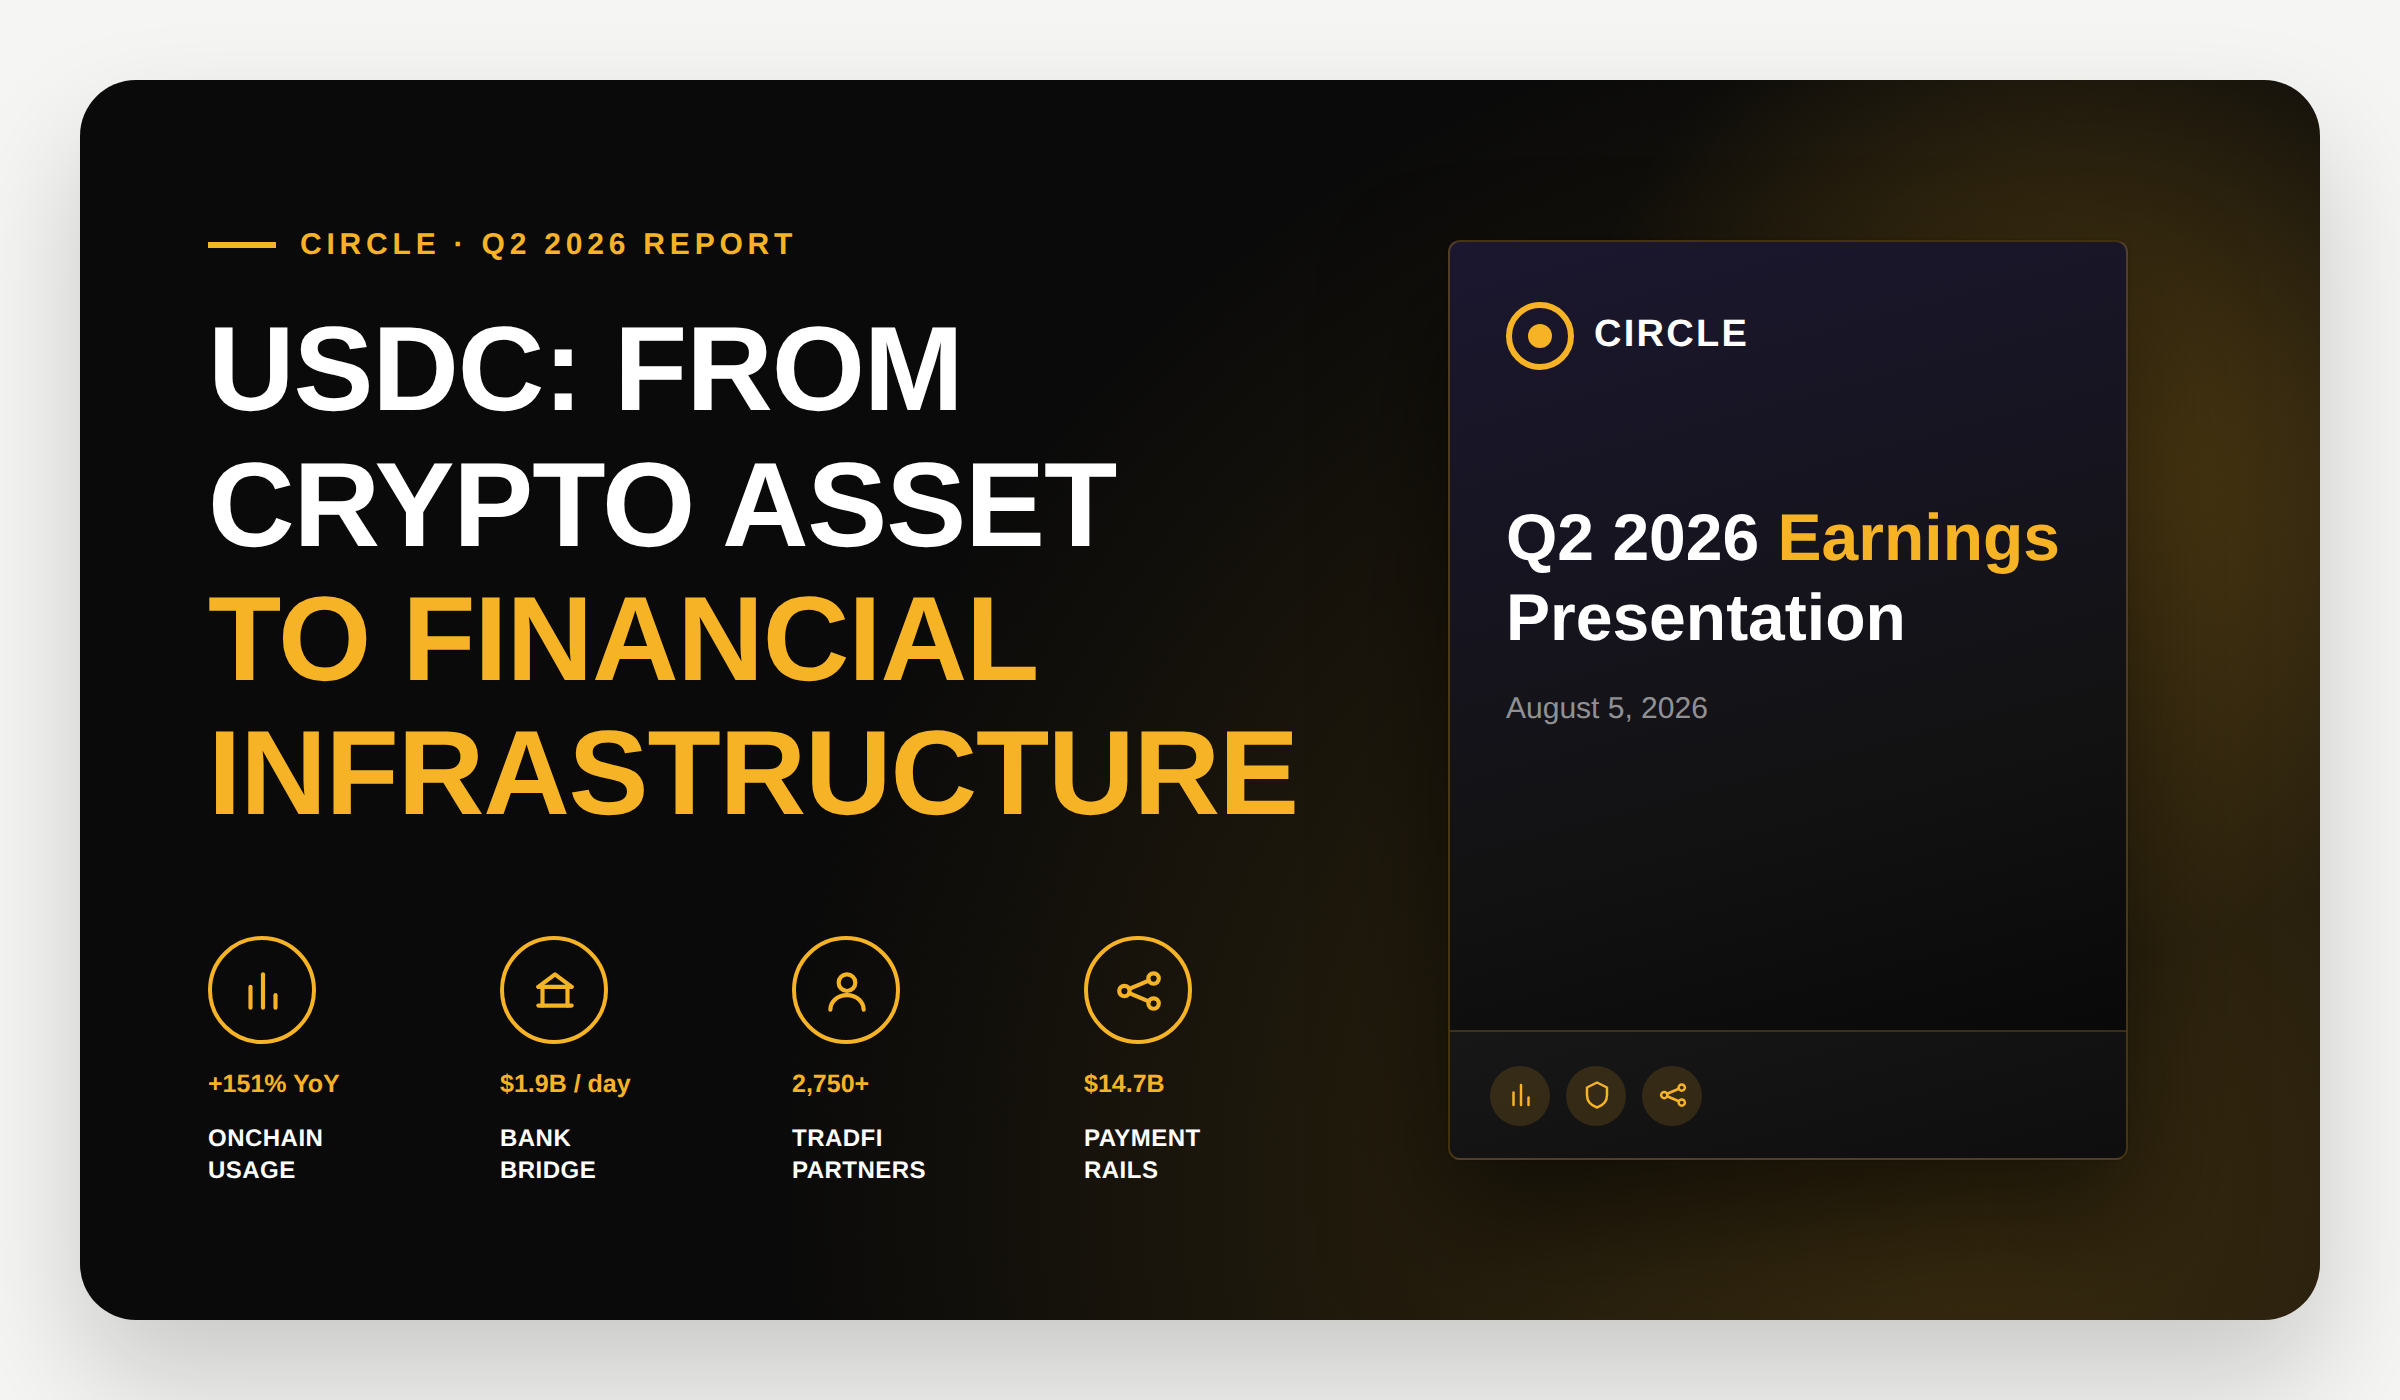
Circle Q2 2026 Report: USDC Is Becoming Financial Infrastructure
Circle’s Q2 2026 report shows how USDC is evolving from a stablecoin into a broader financial rail. Here are the numbers and trends that matter for payments and global businesses.
Circle Q2 2026: Stablecoins Are Becoming Financial Infrastructure
Stablecoins have spent years sitting somewhere between crypto markets and traditional finance.
Circle’s Q2 2026 results suggest that line is becoming much harder to see.
USDC circulation continues to grow. Transaction volume is growing much faster. Banks and financial institutions are moving closer to public blockchain infrastructure. Circle is expanding from stablecoin issuance into payments, tokenized assets, custody, and its own blockchain infrastructure.
The bigger story is not simply that USDC had another strong quarter.
It is that stablecoins are starting to look like a real financial rail.
Here are the developments from Circle’s Q2 2026 Earnings Presentation that we believe matter most.
USDC is growing, but usage is growing much faster
USDC in circulation reached $73.3 billion at the end of Q2 2026, up 19% year over year.
That is significant growth on its own.
But transaction activity tells a more interesting story.
USDC recorded $14.8 trillion in onchain transaction volume during Q2, representing 151% year-over-year growth.
Circle also reported approximately:
- $163 billion in daily onchain transaction volume.
- $1.9 billion in daily minting and redemptions.
- $2.9 billion in daily USDC notional trading volume.
Daily minting and redemption activity increased 105% year over year.
This distinction between supply and activity is important.
A stablecoin can grow because more capital is being stored in it. But when transaction activity grows much faster than circulation, it suggests that the same digital dollars are being used more actively.
Money is not simply entering the system.
It is moving through it.
The wider market shows a similar pattern. Circle’s presentation, using CoinMarketCap and Visa Onchain Analytics data, shows stablecoin circulation growing 22% year over year, while reported transaction volumes grew 84%.
That may be one of the clearest signals that the stablecoin story is moving beyond holding and trading.
The bridge between banking and blockchain is becoming more important
Blockchain transaction speed gets much of the attention around stablecoins.
For businesses, however, a fast blockchain is only useful if money can also move efficiently into and out of it.
Circle reported $170 billion of USDC mint and redeem volume in Q2, compared with $83 billion one year earlier.
Circle’s network now includes more than 15 partner banks, 150 distribution partnerships, and 2,750 direct relationships.
The goal is straightforward.
Make it easier to move between fiat money and USDC across major markets.
This matters because the real business use case rarely ends on a blockchain.
A company may receive stablecoins but need EUR or USD for operating expenses.
A fintech may collect fiat but need stablecoins for international settlement.
A platform may need to move between both depending on the recipient, geography, or payment route.
The blockchain is one part of the journey.
The bridge between traditional money and digital money can be just as important as the rail itself.
Traditional finance is moving closer to stablecoins
One of the strongest themes in Circle’s report is the number of traditional financial institutions appearing throughout it.
The presentation highlights continued adoption involving names including BNY Mellon, Standard Chartered, Kakao, and JCB.
The Arc section goes even further.
Circle lists more than 100 private mainnet partners and shows a validator set that includes financial and infrastructure companies such as BlackRock, DTCC, Global Payments, ICE, Mastercard, MoneyGram, Standard Chartered, Sumitomo Mitsui, and Visa.
This changes the old narrative.
For years, crypto was often presented as an alternative financial system that would replace banks and traditional payment infrastructure.
What is emerging looks different.
Banks, card networks, asset managers, payment companies, and blockchain infrastructure are increasingly connecting to one another.
Stablecoins do not necessarily need to replace traditional finance.
They can become another rail inside it.
Regulation is becoming an infrastructure advantage
The report also makes regulation a central part of Circle’s strategy.
Circle reports USDC across 35 blockchain networks, more than 55 registrations and licenses, and availability across 185 countries.
The company also highlights:
- 1:1 reserve backing.
- Segregated reserve accounts.
- Monthly reserve-asset attestations by a Big Four accounting firm.
- AML and BSA controls.
- Real-time monitoring.
- OFAC screening.
Another major development came in July 2026.
Circle received final OCC approval to establish Circle National Trust under direct US federal oversight.
Circle describes this as a regulated foundation for digital asset custody and a future capability for USDC reserve management.
The strategic message is important.
Regulation is often described as friction for digital assets.
For institutional adoption, the opposite can also be true.
Banks and large businesses need clear rules, reserve transparency, compliance controls, and accountable counterparties before they can move meaningful financial activity onto new rails.
In that context, regulation becomes less of a brake and more of a bridge to adoption.
Stablecoins are becoming payment infrastructure
Perhaps the most relevant development for the payments industry is the growth of Circle Payments Network, or CPN.
CPN connects financial institutions around stablecoin-based payment flows.
Its annualized transaction volume reached $14.7 billion in Q2, growing 76% quarter over quarter. Circle reported 175 financial institutions enrolled by the end of June.
Circle is also working on the less visible parts of payment infrastructure.
The presentation highlights unified onboarding and liquidity, faster corridor activation, automatic rerouting when routes fail, and integrations with Circle Mint, StableFX, and Arc.
These details matter.
Moving a token from one wallet to another is relatively easy.
Building reliable payment infrastructure around it is harder.
Businesses need liquidity.
They need fiat settlement.
They need compliance.
They need reconciliation.
They need reliable payment routes.
They need reporting.
And they need systems that still work when something goes wrong.
That is where stablecoin payments start becoming less about crypto and more about financial operations.
USDC is becoming increasingly cross-chain
Another part of the infrastructure story is interoperability.
USDC is now supported across 35 blockchain networks.
Circle reports 756 CCTP routes across supported networks. Its Cross-Chain Transfer Protocol allows native USDC to move between chains without relying on traditional wrapped-token bridges.
Circle describes the goal as unified liquidity without fragmentation across blockchain ecosystems.
This may sound technical, but the business implication is simple.
Companies generally do not want to think about which blockchain their money is sitting on.
They want liquidity to be available where it is needed.
The more invisible this complexity becomes, the easier stablecoins become to use as ordinary financial infrastructure.
The story is expanding beyond the digital dollar
USDC remains Circle’s core product, but the Q2 presentation points toward a much broader strategy.
EURC circulation reached €382 million, compared with €172 million one year earlier.
That represents approximately 2.2x year-over-year growth.
Circle also reported $3.1 billion in USYC assets, compared with $0.3 billion a year earlier, representing growth of more than 10x. Circle describes USYC as the world’s largest tokenized money market fund.
This is an important expansion of the stablecoin thesis.
The opportunity may not stop with tokenized cash.
Cash can become digital.
Treasury assets can become digital.
Securities can become digital.
Settlement can move onto the same infrastructure.
That brings us to one of the most ambitious parts of Circle’s strategy.
Arc shows where Circle thinks financial infrastructure is heading
Circle plans to launch the Arc mainnet on September 16, according to the Q2 presentation.
Its testnet had already processed 502 million transactions across 2.8 million transacting wallets, with reported uptime of 99.99%.
Arc is not presented as another general-purpose blockchain.
Circle describes it as infrastructure designed specifically for regulated finance.
The network is designed around features such as:
- USDC-denominated gas.
- Sub-second finality.
- Configurable privacy.
- Built-in FX.
- Institutional validators.
Two partnerships show what Circle is aiming for.
DTCC integration is expected to bring tokenized real-world assets onto Arc, including selected equities, ETFs, and Treasuries. Circle also describes potential use cases around securities lending and collateral settlement.
Meanwhile, BlackRock’s BUIDL tokenized treasury fund is expected to deploy on Arc, with BlackRock also participating as a founding validator.
This suggests a much larger ambition.
Circle is not only trying to issue a successful stablecoin.
It is building an environment where money, assets, payments, liquidity, and settlement can increasingly exist on the same infrastructure.
AI agents may become another source of payment demand
One of the more experimental parts of the report is Circle’s work around AI agents.
Circle reports that 99.3% of x402 agent-payment volume settles in USDC, with more than 900 paid services already available in its agent marketplace as of July 31.
The idea is that software agents can hold spending policies, purchase services, settle payments onchain, earn money, and build reputation from completed transactions.
It is still early.
But it highlights something important about digital money.
Traditional payment systems were designed primarily around people and companies.
Software increasingly needs to transact as well.
Always-on, programmable money may therefore find use cases that do not map neatly onto today's card or banking infrastructure.
The financial results show a real business behind the narrative
Circle generated $701 million in total revenue and reserve income in Q2, up 7% year over year.
Adjusted EBITDA reached $143 million, up 8% year over year.
Other revenue grew 41% year over year, although reserve income remains the dominant part of Circle's revenue mix.
Circle continues to guide toward approximately 40% multi-year CAGR in USDC circulation.
The wider market expectations are even broader.
Third-party forecasts cited by Circle put the stablecoin market somewhere between $0.9 trillion and $4 trillion by 2030.
That range is huge.
But perhaps that is the point.
Nobody knows exactly how large the market will become.
The direction is easier to see than the final number.
What we think this means for businesses
Our main takeaway from Circle’s Q2 report is not that every company suddenly needs USDC.
It is that the distinction between “crypto infrastructure” and “financial infrastructure” is starting to disappear.
Stablecoins are becoming useful where they solve an actual financial problem.
That can mean accepting payments from customers who prefer digital assets.
It can mean paying contractors or partners internationally.
It can mean moving liquidity outside banking hours.
It can mean converting between fiat and digital currencies.
It can mean reaching markets where traditional payment rails are expensive or limited.
And increasingly, it can happen behind the scenes without the end user needing to understand blockchain at all.
This is also how we think about the market at INXY Payments.
We started with crypto processing and built products around accepting, converting, and sending digital money.
But businesses do not have a “crypto problem”.
They have a money problem.
They need to receive money, hold it, convert it, pay people, move it internationally, and keep control of the whole process.
Stablecoins are becoming one of the rails that can make those jobs easier.
The technology matters.
But as the infrastructure improves, businesses should need to think about it less.
That may be the clearest sign that stablecoins are growing up.
Explore the full Circle Q2 2026 report
We have highlighted the developments we found most relevant for payments and global businesses.
There is much more in the original 35-page Circle Q2 2026 Earnings Presentation, including detailed data on USDC circulation, liquidity, Arc, CPN, tokenized assets, AI, financial performance, and Circle’s outlook.
The full Circle Q2 2026 report is available below.
Stablecoin Payment Infrastructure in 2026
The most important shift in digital payments this year is not a new chain or a new token. It is the quiet realisation that stablecoins have crossed from speculation into infrastructure. The Paypers’ Global Stablecoins Report 2026 puts total stablecoin market capitalisation at roughly USD 317.9 billion, with projections that it could exceed USD 2 trillion as institutional participation accelerates — and some contributors put the figure closer to USD 4 trillion by 2030. At INXY, we read those numbers differently from most. The headline is not the size of the market. It is that stablecoins have become one of the first blockchain-based instruments to show clear product-market fit in payments.
The most important shift in digital payments this year is not a new chain or a new token. It is the quiet realisation that stablecoins have crossed from speculation into infrastructure. The Paypers’ Global Stablecoins Report 2026 puts total stablecoin market capitalisation at roughly USD 317.9 billion, with projections that it could exceed USD 2 trillion as institutional participation accelerates — and some contributors put the figure closer to USD 4 trillion by 2030. At INXY, we read those numbers differently from most. The headline is not the size of the market. It is that stablecoins have become one of the first blockchain-based instruments to show clear product-market fit in payments.
That single fact reframes the question every finance team, PSP, and merchant should be asking. It is no longer “should we look at stablecoins?” It is “which payment flows should run on them, and what stablecoin payment infrastructure do we need to make that safe, compliant, and economical?” This article is our read of the report’s data — and what it means for businesses that want to accept stablecoin payments, automate payouts, and move value across borders without rebuilding the financial stack from scratch.
Stablecoins have reached product-market fit in payments
For a decade, crypto payments were a promise: faster, cheaper money movement that never quite arrived at scale. What changed is not the blockchain — it is the infrastructure wrapped around it. The report is blunt on this point, describing stablecoins as one of the first blockchain-based instruments to demonstrate clear product-market fit in payments, increasingly used for cross-border settlement, treasury operations, merchant payouts, and everyday commerce.
The adoption base is real, not theoretical. Triple-A’s data cited in the report shows cryptocurrency ownership rising from around 560 million people in 2024 to roughly 700 million in 2026 — about 8.5% of the global population. These are not all traders. A growing share are freelancers, remote workers, and businesses that earn and hold digital dollars and want to spend or settle them without friction. Demand for a usable rail already exists; the constraint has been supply of trustworthy infrastructure.
Our view is simple. The metric that matters is not the market cap of crypto. It is the number of businesses that can use stablecoins to solve a concrete money problem — a supplier that needs paying today, a payout that needs to clear over a weekend, a treasury balance stranded behind a banking cut-off. That is the lens we apply to every number below.
Enterprise adoption is at an inflection point
Awareness of stablecoins among enterprises is now nearly universal, yet active production use remains modest. That gap is exactly what an inflection point looks like. In the EY-Parthenon survey referenced in the report (n=350), a majority of current non-users said they expect to begin using stablecoins within the next six to twelve months. The conversation inside finance teams has moved from “should we look at this?” to “where should we use it first?”
The intent is concentrated, not scattered. Among corporates asked which use cases they are most interested in over the next five years, the top answers were paying suppliers cross-border (77%), accepting cross-border business payments (49%), and accepting domestic business payments (37%). In financial services specifically, 91% of respondents said stablecoins would become a top priority or receive more attention. This is a back-office, treasury-first story — the place where return on investment is clearest and operational risk can be tightly controlled.
One data point matters more than any other for how this market will be served. When corporates were asked how important it is that their existing banking or payments provider supports stablecoins, 81% said it was critical or important, and 68% said they would prefer a bank-grade issuer. In other words, most businesses do not want to become crypto companies. They want to reach stablecoin capability through providers they already trust, embedded into the ERP and treasury systems they already run. Interoperability beats novelty every time.
Cross-border is the killer use case — but only where legacy rails fail
Cross-border payments lead enterprise adoption for a practical reason: this is where the old process is genuinely broken. A traditional international transfer can take days, pass through several correspondent banks, and leave money stranded in transit. Stablecoins offer near real-time settlement, 24/7 availability, and on-chain visibility — and the economics can be decisive. Among organisations already using stablecoins, 41% report cost savings of 10% or more compared with traditional methods, with the largest gains in cross-border B2B, where correspondent fees, FX spreads, and reconciliation costs stack up.
But the honest version of this story is geographic, and we insist on telling it that way. In Europe, where SEPA Instant already moves money in seconds at near-zero cost, the incremental advantage of a stablecoin for a domestic transfer is small. The value appears on corridors where legacy infrastructure fails. The report cites OpenPayd’s point that a USD 200 remittance to Sub-Saharan Africa can cost more than 8%, against a global average above 6% — and that stablecoins can cut that by over 75%, going as low as 0.5% when paired with reliable on- and off-ramps. MetaComp describes a payment from the UAE to Singapore that takes two to five days through correspondent banking settling in roughly 20 minutes at about half the cost.
So the right question is not “will stablecoins replace banks?” It is “which payment flow should run on which rail?” Stablecoins are not a universal upgrade; they are a precise tool for corridors that are slow, expensive, or fragmented. Matching the right rail to the right flow, market by market, is the actual work — and it is the work we build infrastructure to automate.
The cost nobody talks about: on-ramp and off-ramp economics
Here is the trap that sinks naive stablecoin projects, and the report is refreshingly direct about it. The blockchain fee is only a fraction of the true cost. Moving money into a stablecoin (the on-ramp) and back into local fiat (the off-ramp) is not free. Depending on provider, corridor, and volume, conversion fees run from 0.5% to more than 2% per leg — 1% to 4% on a full round trip. For a business with thin margins, that can erase the headline saving entirely.
The lesson we draw is one we design around every day: the cheapest blockchain transaction does not automatically produce the cheapest payment. Any honest assessment of stablecoin economics must include the full on/off-ramp cost, not just the on-chain fee. This is precisely why liquidity, FX, conversion, and settlement infrastructure matter so much — and why the industry is consolidating around orchestration layers such as Circle’s Payments Network (CPN) and cross-chain protocols like CCTP that move USDC between blockchains without costly bridges. The economics only work when at least one party can hold and route stablecoins natively, and when conversion is priced in basis points rather than percentage points.
For most businesses, building that liquidity and conversion layer in-house is neither realistic nor wise. The competitive edge is not owning a wallet; it is reaching deep, well-priced liquidity through infrastructure that already has it.
The hard part is no longer the blockchain — it is everything around it
If there is one theme the report returns to again and again, it is this: the technology is ready and has been for years. What was missing was the infrastructure required to run stablecoin flows safely, at scale, through systems businesses already understand. Companies need compliance, liquidity, fiat connectivity, reconciliation, custody, and orchestration wrapped around the stablecoin rail. That is where the market gets interesting — and where the winners will be decided.
Compliance is becoming part of the product
Regulation has flipped from the biggest barrier to an adoption enabler. Frameworks such as the GENIUS Act in the US and MiCA in the EU now give issuers and providers a clearer operational footing, especially for bank-issued or bank-distributed stablecoins that meet defined reserve, compliance, and governance standards. The question is no longer whether stablecoins are “too risky.” It is whether a company’s infrastructure is good enough to use them safely.
That raises the bar on operations. KYC, AML, Travel Rule obligations, wallet screening, and transaction monitoring all still apply — and adapting them to on-chain flows is a genuine engineering challenge. The report notes that redundant, repeated KYC is a real drag on growth: across the industry, 25–35% of users abandon onboarding when asked to upload an ID and selfie, while modern compliance engines can screen over 99% of transactions within seconds. Compliance is no longer a checkbox bolted on at the end. It is part of the product, and it has to be fast enough not to kill conversion.
Orchestration and the multi-rail future
The report’s central strategic conclusion — and ours — is that stablecoins will not replace every payment rail. The likely future is multi-rail: bank transfers, instant-payment networks, and stablecoins operating side by side, each carrying the flows it serves best. Stablecoins shine where traditional rails are slow, costly, or fragmented; in highly efficient domestic markets, their edge narrows.
That makes orchestration the decisive capability. Orchestration is the end-to-end management of a payment’s journey — deciding, for each transaction, whether to use a stablecoin, which issuer and chain to select, and when to convert between fiat and digital assets, based on value, urgency, liquidity conditions, and counterparty location. As more rails become available, this routing layer is where cost, speed, and compliance are won or lost. The industry examples in the report make the point: the SG-FORGE and Swift live trial settled tokenised bonds using both traditional financial infrastructure and regulated digital currencies, and Nexus Global Payments is interlinking domestic instant-payment systems like India’s UPI and Singapore’s FAST. None of these efforts replace the old system. They make the whole system work together.
What this means for businesses evaluating stablecoin payments
This report describes, almost line for line, the problem we built INXY to solve. INXY provides the infrastructure businesses need to accept stablecoin payments, automate payouts, convert between crypto and fiat, and move money across borders — without building blockchain, liquidity, compliance, and settlement systems from scratch. We operate the layer behind the customer experience, so the complexity stays out of sight.
Concretely, that means:
- The merchant does not need to become a crypto company to accept stablecoin payments — acceptance runs through familiar checkout and settlement flows, with conversion to fiat handled behind the scenes.
- The fintech does not need to build the entire compliance stack — KYC, AML, Travel Rule, and wallet screening are part of the rail, fast enough to protect conversion rather than throttle it.
- The finance team does not need to manage a collection of wallets and chains — payouts, multi-currency treasury, and on/off-ramp conversion are orchestrated through a single integration, priced to keep the full round-trip economics intact.
If you are evaluating stablecoins, we would frame the decision the way the report’s data suggests. Start with the corridors and flows where traditional rails genuinely fail — cross-border supplier payments, international payouts, multi-currency treasury — not with the flows your domestic bank already handles well. Model the full on/off-ramp cost, not just the on-chain fee. And treat compliance and orchestration as core product requirements, not afterthoughts. The businesses that win with stablecoins are not the ones that move tokens; they are the ones that make different payment systems work together.
The winners will be the integrators, not the disruptors
The biggest shift captured in the Global Stablecoins Report 2026 is not from fiat to crypto. It is from crypto product to financial infrastructure — banks, PSPs, and processors integrating stablecoins into systems that already exist. Stablecoins do not need to destroy the old rails to matter. They need to make the whole system move value better.
That is the future we are building for at INXY. Not one payment rail, but many — with an infrastructure layer that decides, routes, converts, and settles across all of them, so businesses get the speed and cost of stablecoins with the trust and control finance teams require. The stablecoin era will not be won by whoever shouts loudest about disruption. It will be won by whoever quietly makes the rails work together.
The Post-MiCA Reality: Why European Businesses Now Buy Regulated Stablecoin Infrastructure Instead of Building It
Coincub's Europe Crypto Report 2026 shows a market reshaped by MiCA: 183 licensed CASPs, USDT delisted across regulated venues, and a hard July 2026 compliance cliff. For businesses that simply need to accept payments and pay people globally, the takeaway is to move money through compliant, licensed payment rails rather than carry crypto's regulatory overhead themselves.
Coincub's Europe Crypto Report 2026 frames the last fourteen months as the arrival of a post-MiCA world. The numbers are striking: the EU went from 12 licensed CASPs to 183, a 15x increase, while roughly 3,167 national VASP registrations collapsed to a fraction of that count. MiCA did what it was designed to do — it delivered legal certainty, consumer protection, a public registry of accountable entities, and a single passporting architecture across 30 EU/EEA markets.
But underneath the regulatory success sits a more practical question for the businesses that actually use crypto rails — merchants, marketplaces, ad networks, hosting providers, gaming platforms, payroll operators. The report's data points to an uncomfortable conclusion: the cost of being a regulated entity in Europe has moved out of reach for most companies that simply need to accept and send money. That gap is exactly where regulated payment infrastructure becomes the rational choice.
This piece reads the Coincub findings through that operational lens: not "who won the license race," but "what does a company that just needs to move value across borders do now?"
The compliance floor priced out everyone but the giants
The single most important structural fact in the report is the split MiCA created. Of 183 licensed CASPs, 78 (42%) cover just 1–5 countries — almost exclusively German banks bolting crypto onto existing compliance infrastructure — while 84 (45%) hold near-full EU passports covering 26–30 countries, disproportionately offshore-originated firms that hired EU counsel and passported across the single market. The middle ground is nearly empty.
Why? Because the entry ticket is steep. The report puts the compliance cost floor at €50,000–€150,000 in minimum capital, plus mandatory physical substance, dedicated compliance staff, banking relationships, and 9–18 months of preparation for authorization. As Coincub bluntly notes, that is survivable for a Cayman entity backed by $500M in VC but certainly not survivable for a European pre-seed startup.
Lithuania is the cautionary tale: 345 registered firms fell to 4 MiCA CASP licenses — a 99% wipeout. The cheap-registration model that once let small firms onboard fast didn't survive contact with substance requirements.
The operational read: the businesses that most need crypto and stablecoin payments — merchants, marketplaces, ad networks, payroll operators — were never trying to become crypto companies in the first place. Their job is to accept money and pay people, not to run regulated infrastructure. In a market where the compliance floor is this high, the practical answer is the same one they already use for cards and cloud: consume the capability through a provider that carries the licensing for them. This is the core case for a regulated payment gateway like INXY Payments, which lets a business accept, send, and convert digital money without building or operating crypto infrastructure itself.
Only 14 firms can run an exchange — but most businesses never needed one
One of the report's most under-discussed numbers: of 183 licensed CASPs, only 14 are authorized to operate a centralized exchange with an order book and matching engine. That's 7% of the total.
It's a useful reminder that "crypto business" is not one thing. The overwhelming majority of companies touching digital assets don't want to run a trading venue. They want to accept payment from a customer, settle in euros or dollars the next day, and pay out affiliates, contractors, or suppliers across borders — without holding volatile assets or managing wallets and gas.
That distinction matters because it reframes the licensing panic. The scarce, hard-to-get authorization is the exchange license. The thing most businesses actually need is payment and settlement infrastructure — and they can consume it as a service. INXY's positioning sits precisely here: wallet-free, gas-free, blockchain-free acceptance and payouts, with automatic conversion to stablecoins or fiat to minimize volatility, and same-day bank settlement with audit-ready reporting.
USDT left regulated venues. Businesses still need a stable unit of account.
Few 2025 developments were as visible as the stablecoin reshuffle. Coinbase Europe delisted USDT in December 2024; Binance followed on 31 March 2025; Kraken, OKX, and Revolut did the same. The world's largest stablecoin was removed from every regulated EU exchange.
Globally, Tether barely flinched — its market cap held around $138B as Asian markets absorbed the volume. But inside the EU, the report notes, USDC became the dollar stablecoin of choice, and EURC spiked in April 2025, driven partly by MiCA compliance and partly by shifting US tariff politics. Meanwhile France's finance minister has openly backed more euro-pegged stablecoins, welcoming plans by ING, UniCredit, and BNP Paribas to launch a joint euro stablecoin in H2 2026.
The operational read: for a European business, the question is no longer "which stablecoin is biggest globally" but "which regulated stablecoin rails keep me compliant and keep my accounting clean in EUR or USD." A payment provider that natively handles USDC, EURC, and automatic crypto-to-fiat conversion insulates a merchant from exactly this kind of regulatory reshuffle — the business keeps operating in a stable unit of account while the underlying compliant instrument shifts around it. This is a structural argument for consuming stablecoin settlement as managed infrastructure rather than picking a token and hoping it stays listed.
MiCA is rarely just one license — and the compliance stack keeps growing
For businesses dealing in e-money tokens (EMTs), the report highlights a trap that catches even well-funded firms: one license is often not enough. The EBA intervened twice on the overlap between MiCA and PSD2, because CASPs transacting e-money tokens can also fall within payment-services territory. The practical message for many firms, as Coincub puts it, is "get MiCA, then clear PSD2 too."
This is why the same names keep winning — only groups with the structure to absorb double compliance survive it. For a business whose core job is selling a product or paying a global team, layering two regulatory regimes on top of that was never a realistic path, and shouldn't have to be their problem to solve.
The operational read: the more the EU layers overlapping regimes (MiCA, PSD2, Travel Rule, AML/KYT), the stronger the case for accepting and sending money through a provider that has already absorbed those obligations. INXY builds Travel Rule, AML, and KYT monitoring into the platform and operates under licensing across multiple jurisdictions, so a business gets compliant payment and payout rails without standing up that machinery in-house.
The July 1, 2026 cliff makes reliability a procurement decision
The report is unambiguous about the near-term risk: the grandfathering period ends July 1, 2026. Every entity that hasn't secured MiCA authorization by then must cease operations. Poland — with 1,800+ VASPs and still no MiCA implementation in national law — has no path at all. Estonia's queue is moving but unfinished. Romania's competent-authority designation is still "to be announced." And preparation-to-submission takes 9–18 months, so for anyone still on transitional status without an application already in progress, the window is practically closed.
For a business relying on a crypto payment partner, this is not abstract. A provider operating on borrowed transitional time is a continuity risk. After July 1, some counterparties will simply stop being able to process. The report also flags a tightening trend: the European Commission's Market Integration Package would move direct supervision of all CASPs to ESMA in Paris, and license-lending and white-labeling models built on permissive hubs are directly threatened.
The operational read: vendor due diligence in 2026 has to include a hard look at licensing durability. The question "will my payment provider still be legally operating in Q3?" belongs on every procurement checklist. Choosing a properly licensed, substance-backed provider — rather than a thin white-label wrapper — is now a risk-management decision, not a nice-to-have.
Cross-border fragmentation is the everyday problem passporting doesn't solve
Passporting fixed market access on paper — 183 CASPs now carry access to 30 markets, preserving about 86% of pre-MiCA coverage with a fraction of the entities. But for an operating business, day-to-day friction isn't about legal access; it's about actually moving money to a lot of people, quickly, across borders, at a predictable cost.
That's the gap ordinary payment operations live in: paying affiliates, freelancers, contractors, suppliers, and partners worldwide; reconciling it all; keeping fees down. Traditional rails are slow and expensive here, and the report's broader theme — a market where value increasingly routes through a handful of large, often non-European intermediaries — only sharpens the case for automated, API-driven payout infrastructure that settles in minutes rather than days. Mass payouts by file or API, on-the-fly conversion from a fiat balance, and consolidated reporting are the practical answer to a fragmented single market.
Conclusion: the market told businesses to stop building regulatory overhead
Read strategically, the Europe Crypto Report 2026 is a story about concentration. MiCA raised the floor so high that being a licensed crypto entity is now the domain of large groups and well-capitalized offshore giants. USDT's exit, the MiCA-plus-PSD2 stack, the July 2026 cliff, and the drift toward ESMA supervision all point the same way: the regulatory burden of operating crypto rails in Europe is rising, not falling.
For the businesses that simply need to accept payments, settle in fiat, and pay people globally, the answer isn't to take on crypto's regulatory machinery themselves. It is to treat regulated crypto and stablecoin capability the way they already treat cloud, KYC, or card processing — as infrastructure they plug into. That is the position a provider like INXY Payments occupies: a licensed, compliance-first platform that lets a Web2 business accept and send money on modern stablecoin rails without operating regulated crypto infrastructure itself.
In a post-MiCA Europe, most companies don't need to become a crypto company to use crypto. They need working, compliant rails to move money across borders — and that is something they can simply plug in.
Sources: Coincub, "Europe Crypto Report 2026 — An Outlook of a Post-MiCA World"; INXY Payments (inxy.io).
Stablecoins Just Took Over Institutional OTC
Stablecoins hit 81% of institutional OTC in H1 2026. INXY unpacks Finery Markets' Stablecoin 2035 report — key data and what it means for payments.
An INXY expert read on Finery Markets' "Stablecoin 2035: Back to the Future" report (H1 2026)
Finery Markets just published its "Stablecoin 2035" report, and the headline number is hard to ignore: stablecoins reached 81% of all institutional OTC trades in H1 2026, up from 26% in 2023. The debate about whether stablecoins have product-market fit is over. The interesting questions now are operational — and they land squarely on the businesses that move money for a living.
Here is how our team reads the data, and what it changes for anyone building on stablecoin rails.
The numbers that matter
- OTC is the only growing segment. In H1 2026, OTC trading volumes grew +76% YoY, while the top-20 DEXs fell -38% and the top-20 CEXs -13%. Institutional flow is consolidating into OTC, and it is settling in stablecoins — stablecoin OTC volume nearly doubled (+94% YoY).
- The dollar owns the rail. USD-pegged tokens accounted for 99.87% of OTC stablecoin volume. EUR stablecoins grew 32x year over year, but off a base so small it changes nothing structurally — yet.
- The market is deep and diversifying. Total supply is now north of $300B (~$319B). Tether sits around $190B and USDC around $76B, but their combined share slipped from ~89% to ~83% as issuers multiplied from 30 in 2020 to 215+ in 2025.
- Real assets are following. Tokenized U.S. Treasuries crossed $15B (+150% YoY); tokenized equities are near $1.5B (+400%). Roughly two-thirds of stablecoin supply is held in emerging markets — savings demand, not speculation.
Three signals for payment businesses
1. Payments and treasury — not trading — are the real entry point. The report's contributors converge on one idea: stablecoins become "ordinary" inside a company through the treasury and payments desk, not the trading floor. Cross-border corridors that took 2–5 business days now settle in minutes, with all-in costs compressing from 3–5% (correspondent banking) toward ~1%. For a payments provider, that is the pitch: released working capital and removed friction on flows that recur every single day.
2. The winning infrastructure is invisible. Multiple authors describe the same 2035 endpoint — the word "stablecoin" disappears from the enterprise vocabulary because the rails sit beneath familiar fintech interfaces. Users initiate value in stablecoins; merchants and counterparties receive local fiat without ever touching a wallet, chain, or bridge. The value isn't the token. It's the compliance-first connective layer that hides complexity while preserving speed and 24/7 availability.
3. "Regulated" is the moat. Across every contribution, the common thread is regulation. By 2035, regulated coins — dollar and local alike — are expected to hold the dominant share of supply and activity. Licensing, compliance translation across jurisdictions (MiCA, VARA, Singapore's PSA), and a single clean interface across a fragmented patchwork of currency regimes become the real competitive edge — not raw settlement speed.
The INXY takeaway
The report describes a world where money movement runs on stablecoin rails without the end user ever needing to know it. That is exactly the layer payment infrastructure providers should be building toward: regulated on/off-ramps, stablecoin-to-fiat settlement in the currencies clients actually need, and an interface that treats "any currency, any chain" as a non-issue.
The strategic mistake would be to read this as a race to launch yet another stablecoin. The report is explicit that by 2035, "the truly savvy stablecoin strategy may be not launching one at all." The durable advantage is not issuance — issuance is easy. It is liquidity, compliance, and distribution wired into the systems businesses already use.
For merchants, PSPs, and treasuries evaluating stablecoin payments today, the question the report leaves us with is the right one to steal: not how do we add stablecoins to our stack — but what does our business look like when settlement is instant, always-on, and fiat never needs to leave the chain in the first place?
This commentary is informational and not investment advice.
News

Unlock Global Scale: Meet INXY Payments at Affiliate World Asia in Bangkok

Building the Future of Finance: INXY Payments at TOKEN2049 Asia
Let’s work together
See how easy it is to start with crypto payments without interrupting your current business flow