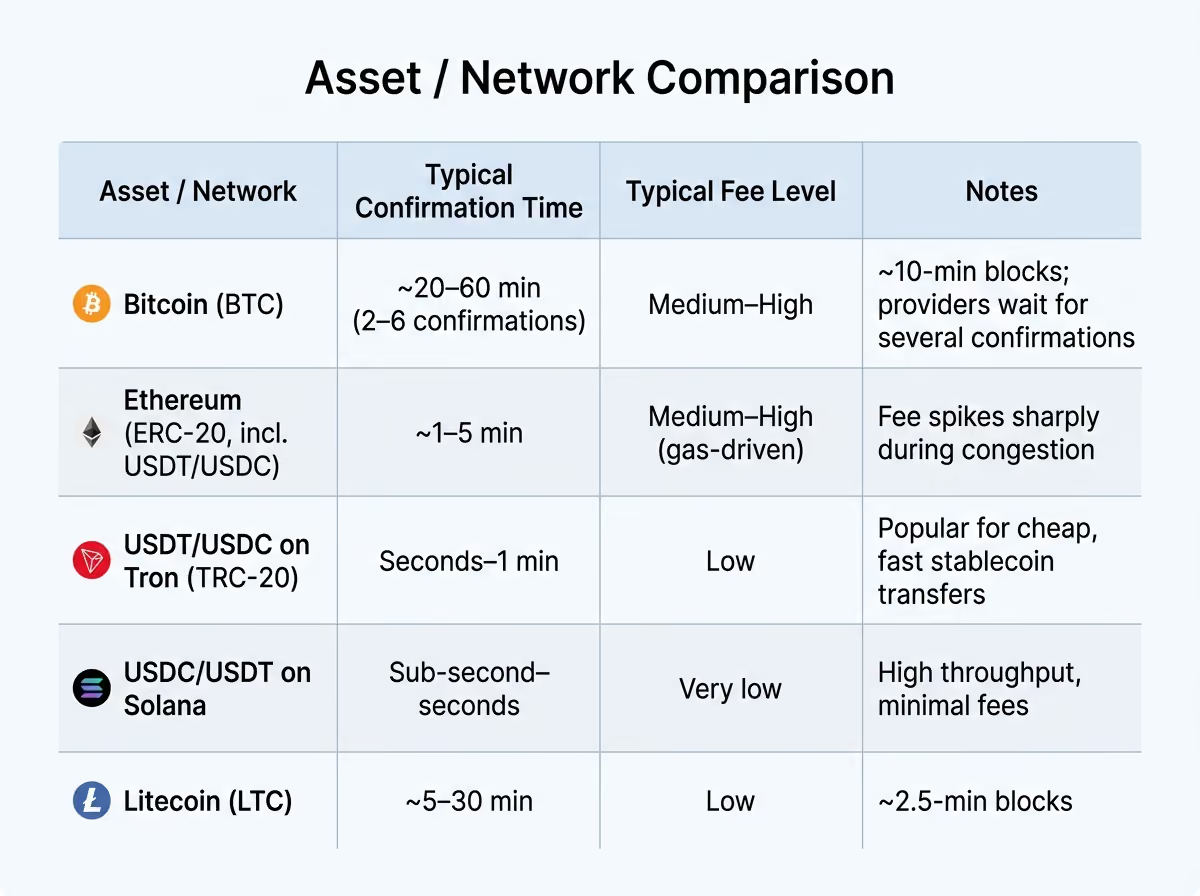
The TRC20 vs ERC20 question is usually answered with a fee table and left there. That answer is incomplete in a way that costs money at volume: the three networks price transactions using three different mechanisms, reach settlement finality on three different timescales, and fail in three different ways when they get busy. If you are sending one transfer, pick the cheapest. If you are sending a payout batch of four hundred, the cheapest network is frequently the wrong one, and this article explains exactly when.
What the three standards are
Snippet target. TRC-20, ERC-20 and BEP-20 are token standards on three separate blockchains — TRON, Ethereum and BNB Smart Chain. The same USDT exists as a different token contract on each, and the balances are not interchangeable without a bridge or an exchange. Choosing a network means choosing that chain's fee model, confirmation speed and liquidity, not a different kind of dollar.
The critical consequence: a USDT balance is chain-specific. Sending BEP-20 USDT to a TRC-20 address is not a slow transfer, it is a transfer to a different network entirely, and whether the funds are recoverable depends on who controls the keys at the destination.
The fee models are not comparable
This is the part fee tables flatten. Each chain charges for a different scarce resource.
Ethereum (ERC-20) — an auction for block space
Ethereum's total fee is "units of gas used * (base fee + priority fee)" (ethereum.org). The base fee is set by the protocol and adjusts with demand: it "will increase or decrease by a maximum of 12.5% per block if the target block size is above or below the target", and once the block is created "this base fee is 'burned', removing it from circulation" (ethereum.org).
A standard ERC-20 transfer consumes roughly 65,000 gas, and around 90,000 from an address that has never held the token (Eco, data pulled 13 May 2026). The same transfer therefore costs approximately $0.30 at 2 gwei, $1.50 at 10 gwei, $4.50 at 30 gwei and $12 at 80 gwei (Eco, 13 May 2026).
The operational point is not the average — it is the variance. A 12.5% per-block move compounds fast. Your treasury model has to survive the 80 gwei day, not the 2 gwei day.
TRON (TRC-20) — a resource you rent, not a price you pay
TRON does not run a gas auction. It meters two resources: Bandwidth, which "covers the byte size of transactions stored on-chain", and Energy, which "covers the computation the TVM performs when executing a smart contract" (TRON developer docs). Every account gets "a free 600 Bandwidth daily quota" and no free Energy at all. A USDT transfer needs roughly 345 Bandwidth, so the free quota covers the Bandwidth leg of about one transfer a day and contributes nothing to the Energy leg, which is where the money is.
A USDT TRC-20 transfer consumes roughly 64,285 Energy to a recipient already holding USDT, and roughly 130,285 Energy to a recipient whose USDT balance is zero.
The doubling is triggered by a zero balance, not by a new address — and this is where most articles get it wrong. The trigger is not history but the balance at the moment of the transfer: if the recipient has never received USDT or its USDT balance is currently zero, the write creates a new storage slot in the token contract rather than updating an existing one, and storage creation on the TVM costs roughly double. A contractor who sweeps their wallet to an exchange after every payment therefore lands on the expensive tier every single time, not once. In a payout batch to freelancers — who by definition empty their wallets — the 130,285-Energy tier is the default case, not the exception. Budget the batch on the high tier and treat the low tier as upside.
Three ways to pay for Energy, and what each actually costs
| Route |
What you pay per transfer |
What it costs you elsewhere |
| Burn TRX |
~6.77 TRX to a funded recipient, ~13.37 TRX to a zero-balance one (≈$1.87 / $3.70 at TRX $0.2766, 10 Feb 2026) |
Nothing locked, nothing to manage. Highest per-transfer cost by a wide margin. |
| Stake TRX yourself |
No marginal TRX while your Energy allowance lasts |
A large locked position and a 14-day exit. A treasury decision, not a fee setting. |
| Rent Energy from a resource provider |
~2.93 TRX per 65,000 Energy for a one-hour rental, published as “around 60% cheaper than burning TRX” (rate card captured 14 September 2026) |
An unregulated third party inside your payment execution path. |
Self-staking is a treasury position, not a fee discount. Energy from staking is allocated by "the proportion of your staked TRX relative to the total TRX staked across the entire network for that resource" (TRON developer docs). There is no fixed TRX-per-Energy rate — the amount you must lock to cover a given number of transfers moves with how much everyone else has staked, so any figure you read is a snapshot of a market, not a protocol constant. At the ratios prevailing through 2026, covering a single 65,000-Energy transfer per day has required staking on the order of 13,000 TRX. Exit is slow: "The unstaked TRX enters a 14-day pending period before it can be withdrawn" (TRON developer docs). Staked TRX does carry TRON Power at 1 TP per TRX, but the docs are blunt that "Unused TP earns you nothing — voting is what generates rewards", so any offset against the locked capital requires actively voting for Super Representatives and is not a return on the stake itself. TRONSCAN's Resource Calculator will price a given stake against current network conditions before you commit.
Renting Energy is the part almost nobody writes up. A market exists of operators who stake TRX at scale and resell the resulting Energy, delegated to your address for a fixed window, priced in TRX well below the burn cost. For a business running a few hundred payouts a month this is materially the cheapest route, and unlike staking it locks up no capital.
Here is what a rental vendor will not put on their pricing page. You are inserting an unregulated counterparty into the execution path of a payment. The delegation itself is benign, but your batch now depends on that operator being available at the moment it runs, you are paying them in TRX, and for a regulated payment business that dependency sits inside a process compliance will eventually ask about. Rented Energy is usually the right answer for a merchant optimising their own treasury. It is a much harder answer for a licensed provider executing client payouts at volume — which is one reason INXY abstracts the resource question away entirely rather than handing the merchant a rental dependency to manage.
TRON also caps contract execution with a fee_limit, and the docs are explicit that "a sufficient account balance alone does not guarantee execution". A batch can fail on a fee limit set months earlier while the account is fully funded.
BNB Smart Chain (BEP-20) — cheap, fast, and structurally different
BEP-20 uses an Ethereum-style gas model at much lower prices. A USDT BEP-20 transfer consumes "around 50,000 to 65,000 gas" at "typical gas prices of 1 to 5 gwei in BNB", putting end-to-end fees in "the $0.10 to $0.30 range for a basic transfer at retail demand levels" (Eco, 2026).
The chain itself changed materially in 2025. The Maxwell hardfork went live on mainnet on 30 June 2025, "reducing block times from 1.5 seconds to 0.75 seconds", with "Fast Finality... now achievable in ~1.875 seconds" (BNB Chain, 2025). That is the fastest published finality of the three.
Comparison table
|
TRON (TRC-20) |
Ethereum (ERC-20) |
BNB Smart Chain (BEP-20) |
| Fee mechanism |
Energy + Bandwidth — burned, self-staked, or rented |
Gas auction: base fee (burned) + priority fee |
Gas auction at low gas prices |
| Typical USDT transfer cost |
Burn: ~6.77 TRX to a funded recipient, ~13.37 TRX to a zero-balance one (≈$1.87 / $3.70 at TRX $0.2766, 10 Feb 2026). Rented Energy: ~2.93 TRX per 65,000 Energy (14 Sep 2026). Self-staked: no marginal cost, large locked position |
~$0.30 at 2 gwei to ~$12 at 80 gwei, 65,000 gas (13 May 2026) |
~$0.10–$0.30, 50,000–65,000 gas at 1–5 gwei (2026) |
| Cost predictability |
High if staked or rented; moderate if burned |
Low — base fee moves up to 12.5% per block |
High |
| Block time |
3 seconds |
12 seconds (one slot) |
0.75 seconds |
| Practical finality |
Solidified once ≥19 of 27 Super Representatives have built on it, “about 1 minute” |
Checkpoint-based; epochs of 32 slots ≈ 6.4 minutes, so finality lands near 13 minutes |
Fast Finality “~1.875 seconds” |
| Reversal cost to an attacker |
Requires colluding SRs |
“at least one-third of the total supply of staked ETH” |
BFT fast-finality guarantees |
| Where volume actually is |
Dominant settlement rail: 60–80% of real-economy stablecoin flows, though share fell from ~74% (Jan 2025) to ~60% (end 2025) |
Rising share, favoured by regulated institutions |
Rising share alongside Solana and Polygon |
| Best for |
High-frequency, price-sensitive payouts with deep USDT liquidity |
High-value settlement where counterparties demand Ethereum |
Fast, cheap transfers where counterparty accepts BNB Chain |
Chain-share figures: BCG / Allium, Stablecoin Payments: The Truth Behind the Numbers. Cost figures carry their own capture dates above; verify against a live explorer before committing a large batch.
Finality time by chain, and what "confirmed" means
"Confirmed" and "final" are different states, and conflating them is how a reconciliation goes wrong.
- TRON produces a block every 3 seconds across 27 Super Representatives. A block is solidified "once at least 19 distinct active SRs have each produced a block at that height or above", which takes "about 1 minute" under normal conditions (TRON developer docs). Before solidification, a reorg is possible — the fork rule is "longest chain wins".
- Ethereum divides time "into slots (12 seconds) and epochs (32 slots)" — roughly 6.4 minutes per epoch — and finalises through checkpoint voting, which in practice means about two epochs, near 13 minutes. Once final, reverting a block requires an attacker "to commit to losing at least one-third of the total supply of staked ETH" (ethereum.org). Most exchanges credit USDT ERC-20 deposits after 12 to 32 confirmations, "putting practical settlement in the 3 to 7 minute range" (Eco, 13 May 2026).
- BNB Smart Chain reaches Fast Finality in "~1.875 seconds" post-Maxwell (BNB Chain, 2025).
The number that matters to you is none of these — it is your counterparty's confirmation policy. If the receiving exchange requires 20 confirmations, TRON's one-minute solidification is irrelevant; you wait for their threshold. Ask for it in writing during integration, because it is the actual determinant of when a payout is "done" from the recipient's point of view.
Network fee pass-through: who eats it
Three models exist, and which one you are on decides whether network fees hit your gross margin or your recipients' trust.
- Absorbed by the sender. You pay the network fee on top of the payout amount. Clean for the recipient, and the line lands in your cost base where finance can see it.
- Deducted from the payout. The recipient receives the amount minus the fee. This is the single largest source of "underpayment" support tickets in crypto acceptance, because the invoice and the received amount no longer match.
- Abstracted by the provider. A gateway sponsors gas and prices it into a blended rate. INXY runs this model — the merchant experience is wallet-free, gas-free and blockchain-free — so network volatility becomes the provider's exposure rather than a line on your month-end.
There is no free option among the three. Abstraction moves the variance rather than eliminating it, and a provider carrying it will price it in somewhere. The question to ask is not "do you charge network fees" but "what happens to my rate when Ethereum gas triples for a week".
Read the full network fee comparison → /blog/usdt-network-fees-compared
Mempool congestion and what actually breaks
Ethereum: the stuck transaction. You broadcast at a max fee that made sense, the base fee climbs 12.5% per block, and your transaction sits unmined. Since "the max fee must exceed the sum of the base fee and the tip", a transaction whose ceiling falls below the prevailing base fee waits indefinitely. Replacing it requires a same-nonce transaction at a higher fee, and if your batch submits sequential nonces, one stuck transaction blocks every transaction behind it. This is the classic Friday-afternoon batch failure.
TRON: the exhausted Energy pool. Staked Energy regenerates over time and a rental covers a fixed window. Either way, a batch that runs past its allowance silently switches to burning TRX for the remainder — so a run budgeted at 2–3 TRX per transfer finishes at 7 or 14, and nothing errors to tell you. If the account also lacks TRX, the remaining transfers simply fail. Size the allowance against the zero-balance Energy figure, not the average.
BNB Smart Chain: the false sense of finality. Sub-second blocks make everything feel instantaneous, which encourages treating first inclusion as settlement. It is not; Fast Finality is a separate state roughly 1.875 seconds later. At three transfers per second in a batch loop, the gap between "submitted" and "final" is where double-counting creeps into reconciliation.
All three: the wrong-network send. The most expensive failure is not a fee, it is a USDT transfer sent on the wrong chain to an address that exists on both. Address formats differ between TRON and the EVM chains, which catches most errors — but ERC-20 and BEP-20 share an address format entirely, and a BEP-20 send to an ERC-20 address is a silent, recoverable-only-if-someone-holds-the-key mistake.
Choosing a network for a payout batch
The operational question the other articles skip. Run it in this order.
- Ask the recipients, before anything else. A batch is only as cheap as the network every recipient can actually receive on. One contractor who can only take ERC-20 does not force the whole batch onto Ethereum — it forces you to split the batch.
- Segment by network, then by recipient balance. On TRON, any recipient sitting at a zero USDT balance costs roughly double the Energy — including regulars who sweep their wallet after every payment. Check balances at batch build time rather than assuming returning payees are on the cheap tier.
- Price the batch on today's numbers, not last month's. Check the live base fee before an Ethereum batch. A 400-transfer batch at 65,000 gas each is 26 million gas; at 2 gwei that is trivial and at 80 gwei it is not.
- Decide burn, stake or rent on TRON — and decide it deliberately. Burning is the default and the most expensive. Renting Energy is usually cheapest and locks no capital, at the price of a third party in the payment path. Self-staking wins only at sustained volume and only if you can lock the position for 14 days on exit. Model all three against your float, not against the per-transfer price.
- Set fee ceilings and nonce strategy before you submit. Use non-sequential or parallelised nonces where the provider supports it, so one stuck transaction does not halt the batch. Set fee_limit on TRON deliberately rather than inheriting a default.
- Run screening before broadcast, not after. KYT and sanctions checks that fire after a transfer is on-chain are a remediation exercise, not a control. On our side, screening, auto-conversion and routing all run before payout execution.
- Reconcile on finality, not inclusion. Mark a payout settled when it reaches the chain's finality state and your counterparty's confirmation threshold — whichever is later.
Send a USDT batch by API or CSV → /cryptocurrencies/mass-payout-in-usdt
Common mistakes
Treating TRON's cost as zero, or paying it the expensive way by default. TRON is cheap, not free: the 600 free daily Bandwidth covers the Bandwidth leg of roughly one transfer and no Energy at all. Burning TRX is what happens when nobody decides anything, and it is the most expensive of the three routes. Deciding once — burn, stake or rent — is worth more than any other network optimisation on this page.
Choosing the network before checking liquidity, and assuming the answer is permanent. A cheap transfer into a market where nobody will off-ramp that token is an expensive transfer. TRON's dominance in real-economy flows exists partly because its USDT liquidity is deepest where payouts actually land — but its share fell from about 74% in January 2025 to about 60% by the end of that year as institutional and platform-integrated flows moved toward Ethereum, BNB Smart Chain, Solana and Polygon (BCG/Allium). Review the network mix; do not set it once.
Optimising the network while ignoring the off-ramp. The network fee is often the smallest line in the total cost of a payout. The conversion spread and the fiat settlement route are usually larger. Fixing the cheap line first is a common and expensive habit.
This article describes technical and market conditions for general information. It is not legal, tax, or financial advice — INXY Payments is a payment infrastructure provider, not a law or accountancy firm, and decisions with regulatory consequence should be reviewed by qualified counsel in the relevant jurisdiction.
Decision framework
- High-frequency payouts to contractors, affiliates or suppliers in emerging markets → TRC-20, and stop burning TRX. Rent Energy if you can accept the counterparty; self-stake if volume is sustained and the capital can sit for 14 days on exit.
- Large, low-frequency settlements to institutional counterparties → ERC-20, and price the gas variance in rather than assuming an average.
- Speed-sensitive transfers where the counterparty already runs BNB Chain → BEP-20, but reconcile on Fast Finality, not first inclusion.
- A mixed recipient list → do not pick one network. Split the batch and treat the split as normal operations rather than an exception.
- You do not want to run any of this → network selection, gas abstraction, screening and conversion belong in infrastructure, not in a finance team's spreadsheet.
The decision worth re-running quarterly is which asset and which chain your recipients actually prefer — it moves. See supported currencies and networks → /cryptocurrencies, or talk to our payments team about a batch → /book-a-demo.
FAQ
Is TRC20 or ERC20 cheaper for sending USDT? TRC-20 is normally cheaper. A USDT TRC-20 transfer costs roughly 6.77 TRX to an address already holding USDT if you burn rather than stake, while an ERC-20 transfer ranges from about $0.30 at 2 gwei to about $12 at 80 gwei. The gap widens sharply whenever Ethereum demand spikes, because TRON's cost is far more stable.
Can I send USDT from a TRC-20 address to an ERC-20 address? No. They are separate blockchains and the address formats differ, so most wallets reject the attempt. Moving between them requires a bridge or an exchange that supports both networks. ERC-20 and BEP-20 share an address format, which makes cross-sends between those two possible and genuinely risky.
Which USDT network is fastest? BNB Smart Chain, on published figures. Blocks are produced every 0.75 seconds and Fast Finality is achievable in around 1.875 seconds. TRON solidifies a block in about a minute, and Ethereum finalises in roughly 13 minutes. In practice your counterparty's required confirmation count usually matters more than the chain's own finality.
Why does a USDT transfer cost twice as much to some addresses? Because the recipient's USDT balance is zero. On TRON that costs roughly 130,285 Energy against 64,285, since the contract must create a storage slot rather than update one. It applies to brand-new addresses and to regulars who empty their wallet after every payment — so for freelancer payouts the expensive tier is the normal case.
How much TRX do I need to stake to cover my transfers? There is no fixed rate. TRON allocates Energy by your share of the total TRX staked network-wide, so the requirement moves as others stake more or less. At 2026 ratios, one 65,000-Energy transfer per day has needed on the order of 13,000 TRX staked, and unstaking carries a 14-day pending period. Price it with a resource calculator before committing.
Should I burn, stake or rent Energy on TRON? Burning is simplest and the most expensive per transfer. Renting Energy from a resource provider is normally the cheapest and locks no capital, but puts a third party in your payment path. Self-staking suits sustained volume if you can tolerate the locked position and the 14-day exit. It is a treasury decision, not an engineering setting.
What is network fee pass-through? It is who bears the blockchain fee on a transfer. Either the sender adds it on top, the recipient absorbs it through a reduced payout, or a payment provider sponsors the gas and prices it into a blended rate. The second model is the most common cause of underpayment and reconciliation disputes.