Imagine launching a killer feature that multiplies your transaction volume overnight, only to have regulators freeze your operations a week later. Welcome to the high-stakes reality of integrating stablecoins into your platform. Right now, digital dollars are powering the global economy, moving billions across borders daily. Your users are demanding it, and the business case for instant settlements is undeniable.
But there is a catch. Financial watchdogs globally are circling. Offering stablecoins is a massive growth lever for ambitious fintechs, but stepping into the crypto arena without an airtight compliance strategy is like walking a tightrope without a net. The ultimate challenge is navigating this regulatory minefield without sacrificing the seamless user experience your customers expect.
The Top Three: USDT, USDC, and DAI
Before diving into regulatory complexities, it is crucial to understand the stablecoin hierarchy and why diversifying your asset offerings is mandatory for compliance.
Tether (USDT): While it currently holds the number one spot for global trading volume, USDT faces severe regulatory headwinds. Notably, the European Union has implemented strict restrictions and effective bans on USDT exchanges under new frameworks, forcing fintechs to rethink relying on a single asset.
USD Coin (USDC): Sitting comfortably as the second most popular stablecoin, USDC is the gold standard for institutional compliance. It is a fully collateralized asset, genuinely backed 1:1 by actual US dollars and short-term assets, providing unparalleled transparency for strict regulators.
DAI: Holding the third position globally, DAI offers a robust, decentralized alternative that maintains its peg through smart contracts and over-collateralization, rounding out the essential stablecoins for any modern financial platform.
Key Regulatory Challenges in the Crypto Landscape
Offering stablecoins is not as simple as plugging into an API. Financial authorities are rapidly tightening their grip to prevent money laundering and systemic economic risks. First, stringent Know Your Customer (KYC) and Anti-Money Laundering (AML) directives require dynamic, ongoing monitoring. Second, the FATF Travel Rule mandates that institutions must securely share originator and beneficiary data for crypto transfers exceeding specific thresholds.
Finally, jurisdictional fragmentation creates a massive headache. The EU’s Markets in Crypto-Assets (MiCA) regulation perfectly exemplifies this, creating strict new rulebooks that directly restrict non-compliant stablecoins like USDT. This makes offering fully backed, transparent assets like USDC an absolute necessity for European operations.
Proven Strategies to Offer Stablecoins Compliantly
To protect your business from crippling fines while maximizing the incredible benefits of digital assets, you must follow these proven operational strategies:
Diversify Your Assets: Do not rely solely on USDT. Offer USDC to satisfy strict regulatory requirements in the EU, and provide DAI for users seeking decentralized options.
Implement Bank-Grade KYC/AML: Utilize automated identity verification systems that check users against global sanctions watchlists in real-time.
Integrate Transaction Monitoring: Deploy sophisticated blockchain analytics tools to trace wallets, ensuring incoming funds are not linked to illicit activities.
Geofence Restricted Jurisdictions: Utilize precise IP tracking to block specific stablecoin features in regions where they are explicitly banned or heavily restricted.
INXY as the Premier Crypto Payment Gateway Partner
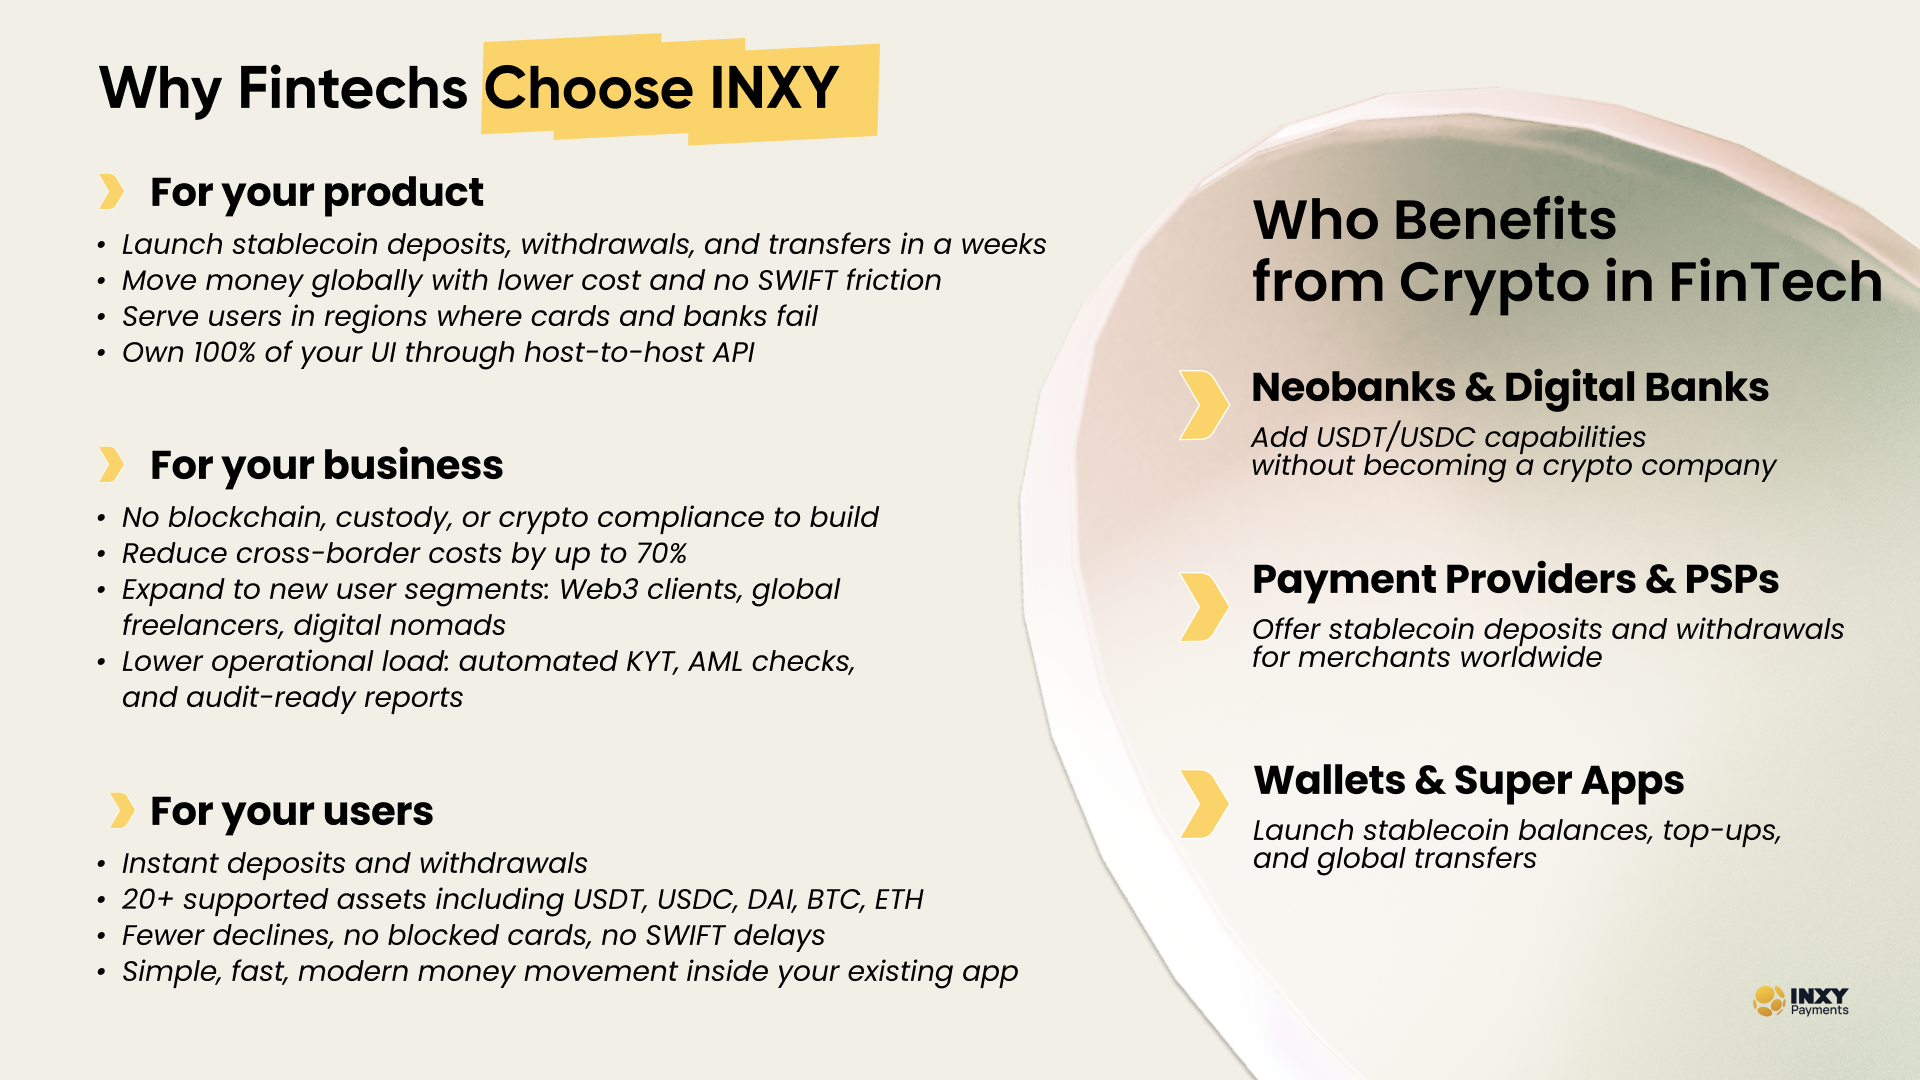
Navigating this tangled web of regulations demands the right underlying technological infrastructure. This is where INXY steps in as the premier partner for fintech companies looking to integrate digital assets securely.
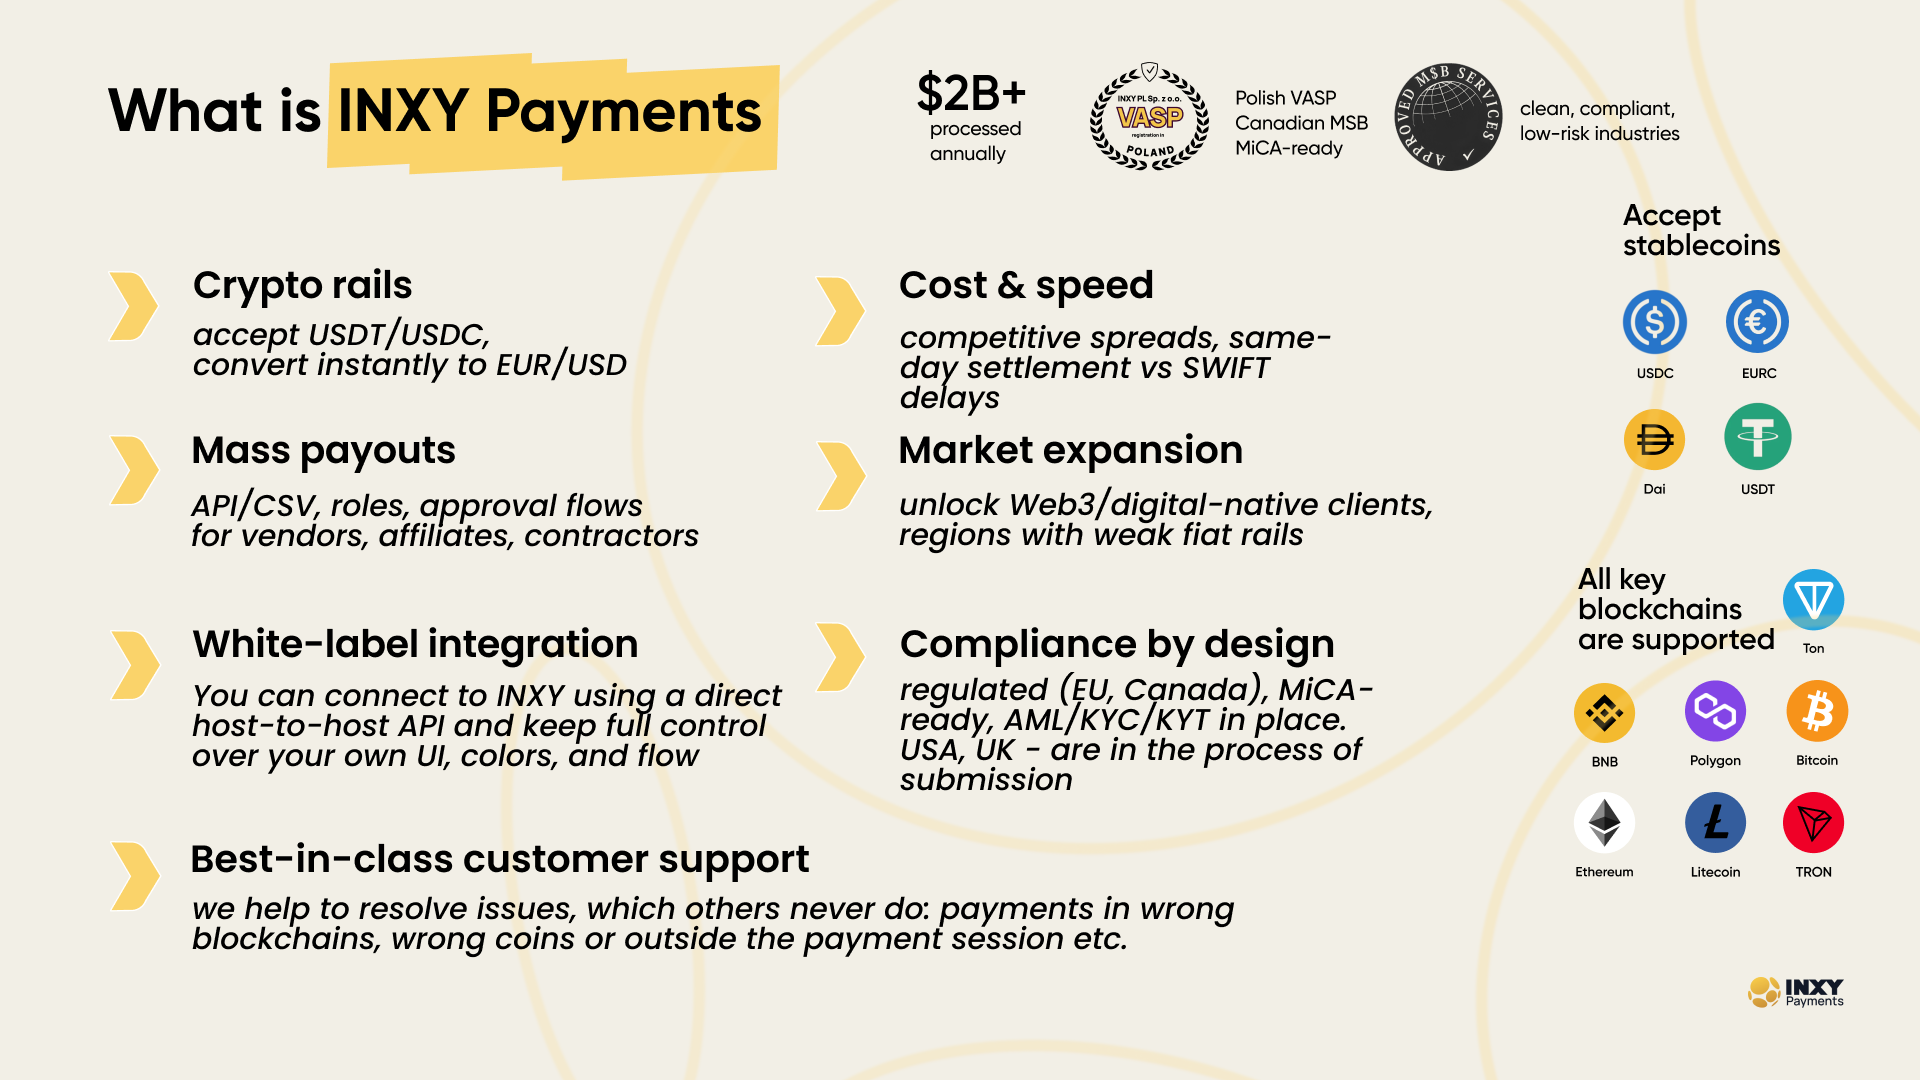
As a dedicated cryptocurrency payment gateway, INXY understands the exact pain points fintechs face. Most importantly, INXY natively supports all three of the top stablecoins: USDT, USDC, and DAI. Whether you need a reliable gateway to process fully backed USDC deposits in the heavily regulated EU market or high-speed APIs for global USDT and DAI transfers, INXY provides the robust backbone your application needs to scale while maintaining strict operational compliance.
Conclusion
The future of global payments is strictly digital, and stablecoins are leading the charge. While the fragmented regulatory environment is complex, it should not deter your business from innovating. By prioritizing proactive compliance, diversifying your asset offerings, and choosing the right technological allies, you can confidently offer secure stablecoin services to your users.
Ready to future-proof your financial platform? Discover how we can help you scale your operations compliantly by visiting https://www.inxy.io/fintech today.
Crypto Mass Payouts for Affiliate Networks: Automate BTC, USDT & ETH Partner Payments
Running an affiliate network means managing dozens — or hundreds — of payment relationships simultaneously. When those partners operate across different countries and expect crypto compensation, the bottleneck isn't traffic or conversions: it's payout infrastructure. Manual crypto transfers don't scale. Exchange withdrawal APIs are built for single recipients. And treasury teams shouldn't be copying wallet addresses one by one every payout cycle.
Running an affiliate network means managing dozens — or hundreds — of payment relationships simultaneously. When those partners operate across different countries and expect crypto compensation, the bottleneck isn't traffic or conversions: it's payout infrastructure. Manual crypto transfers don't scale. Exchange withdrawal APIs are built for single recipients. And treasury teams shouldn't be copying wallet addresses one by one every payout cycle.
INXY's Mass Payouts API solves this at the infrastructure level — letting affiliate programs send BTC, USDT, ETH, and other crypto assets to hundreds of recipients in a single payout cycle — with AML/KYT compliance handled automatically on every transaction.
Why Affiliate Networks Are Moving to Crypto Payouts
Cross-Border Friction with Traditional Rails
Bank wires and PayPal are the default — but they're slow, regionally inconsistent, and expensive for international affiliate programs. SWIFT transfers take 2–5 business days and carry correspondent bank fees. PayPal blocks accounts in dozens of jurisdictions. For an affiliate network paying partners in Southeast Asia, Eastern Europe, or Latin America, these aren't edge cases — they're the norm.
Crypto payouts bypass this entirely. On-chain settlement means funds arrive in minutes regardless of recipient geography, with no correspondent banking dependencies.
Affiliates Demanding Crypto Compensation
Across iGaming, Forex, and SaaS verticals, crypto-denominated affiliate commissions have shifted from a niche perk to a standard expectation. High-volume affiliates — those generating meaningful revenue for programs — increasingly prefer USDT or BTC over fiat because it sidesteps local banking restrictions, enables faster compounding, and reduces currency risk on earnings held in volatile local currencies.
Speed and Cost Advantages of On-Chain Settlement
For affiliate programs running weekly or bi-weekly payout cycles, speed matters. Crypto settlements are typically confirmed within minutes to hours — compared to the 2–5 day window of international bank transfers. On-chain fees, while variable, are often lower than the cumulative cost of wire fees multiplied across a partner base of 100+ recipients.
How INXY's Mass Payout API Works for Affiliate Programs
The INXY affiliate payout workflow is designed to run without manual intervention once integrated:
1. Register your company and pass KYB verification — powered by Sumsub, typically completed within 1–2 business days.
2. Fund your INXY account — deposit BTC, USDT, ETH, or hold EUR/USD and use the buy_crypto flag to auto-convert at payout time.
3. Build your payout batch — compile affiliate wallet addresses, amounts, and optional memo fields. There is no hard cap on the total number of recipients per payout cycle.
4. Submit via the INXY Mass Payouts API — a single REST call with a JSON payload covering your entire affiliate payment run.
5. INXY runs AML/KYT screening automatically on every outgoing transaction — no manual review required from your team.
6. Funds are broadcast on-chain and confirmed — affiliates receive their payouts directly to their wallets.
Webhook callbacks notify your system of each transaction status in real time. No per-transaction dashboards. No manual approvals. No treasury team bottleneck.
Supported Cryptocurrencies for Affiliate Payouts
Bitcoin (BTC)
Bitcoin remains the preferred settlement currency for affiliates in iGaming and high-risk verticals. INXY sends BTC payouts on the Bitcoin mainnet — no Lightning Network at this stage. Settlement time depends on network congestion and the fee tier selected at submission. Affiliates receive BTC directly to any standard Bitcoin wallet address.
USDT (TRC-20 / ERC-20)
USDT is the dominant stablecoin for affiliate compensation — it eliminates volatility risk while preserving the speed and borderless nature of crypto settlement. INXY supports USDT on both TRC-20 (Tron network, low fees) and ERC-20 (Ethereum network). For programs where affiliates prefer stable value, USDT payouts via INXY are the most practical option.
ETH and Other Supported Assets
Ethereum (ETH) and additional crypto assets are supported through INXY's payment infrastructure. Programs can diversify payout currencies based on affiliate preference or treasury composition. INXY's buy_crypto flag means programs can hold EUR or USD in their INXY balance and auto-convert to whichever asset the affiliate batch requires at payout time.
INXY vs Manual Crypto Payouts vs Exchange APIs
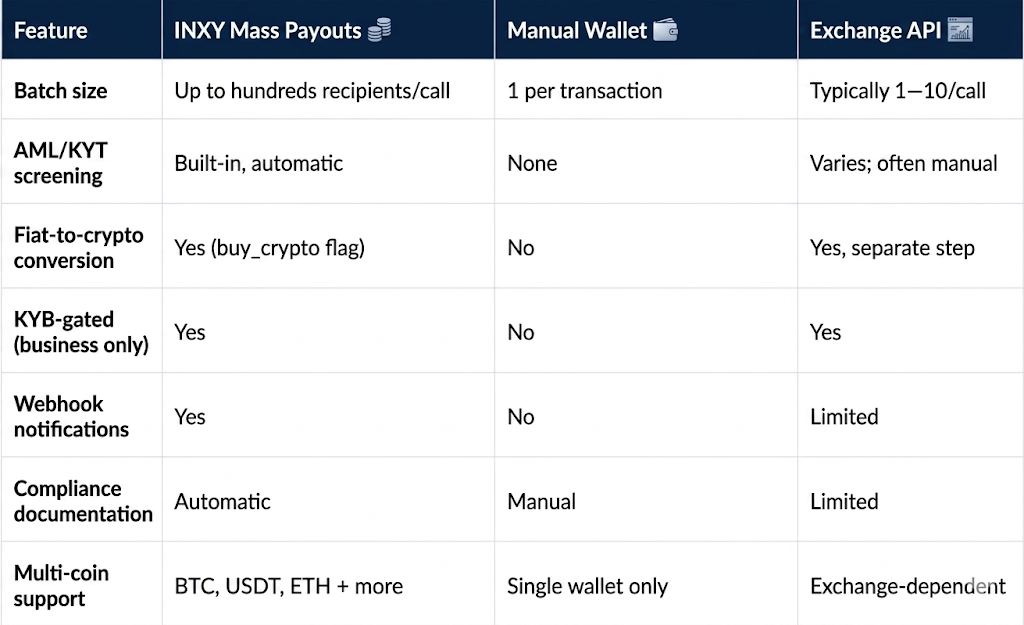
Not all crypto payout methods are equivalent. Here's how INXY's Mass Payouts infrastructure compares to alternatives affiliate programs typically try first:
For affiliate programs paying more than 10 partners per cycle, the operational gap between INXY and manual methods compounds rapidly. A single API call replacing 200 individual wallet transactions isn't a marginal improvement — it's a different category of infrastructure.
For affiliate programs paying more than 10 partners per cycle, the operational gap between INXY and manual methods compounds rapidly. A single API call replacing 200 individual wallet transactions isn't a marginal improvement — it's a different category of infrastructure.
Compliance and AML Screening — Built for Regulated Affiliate Programs
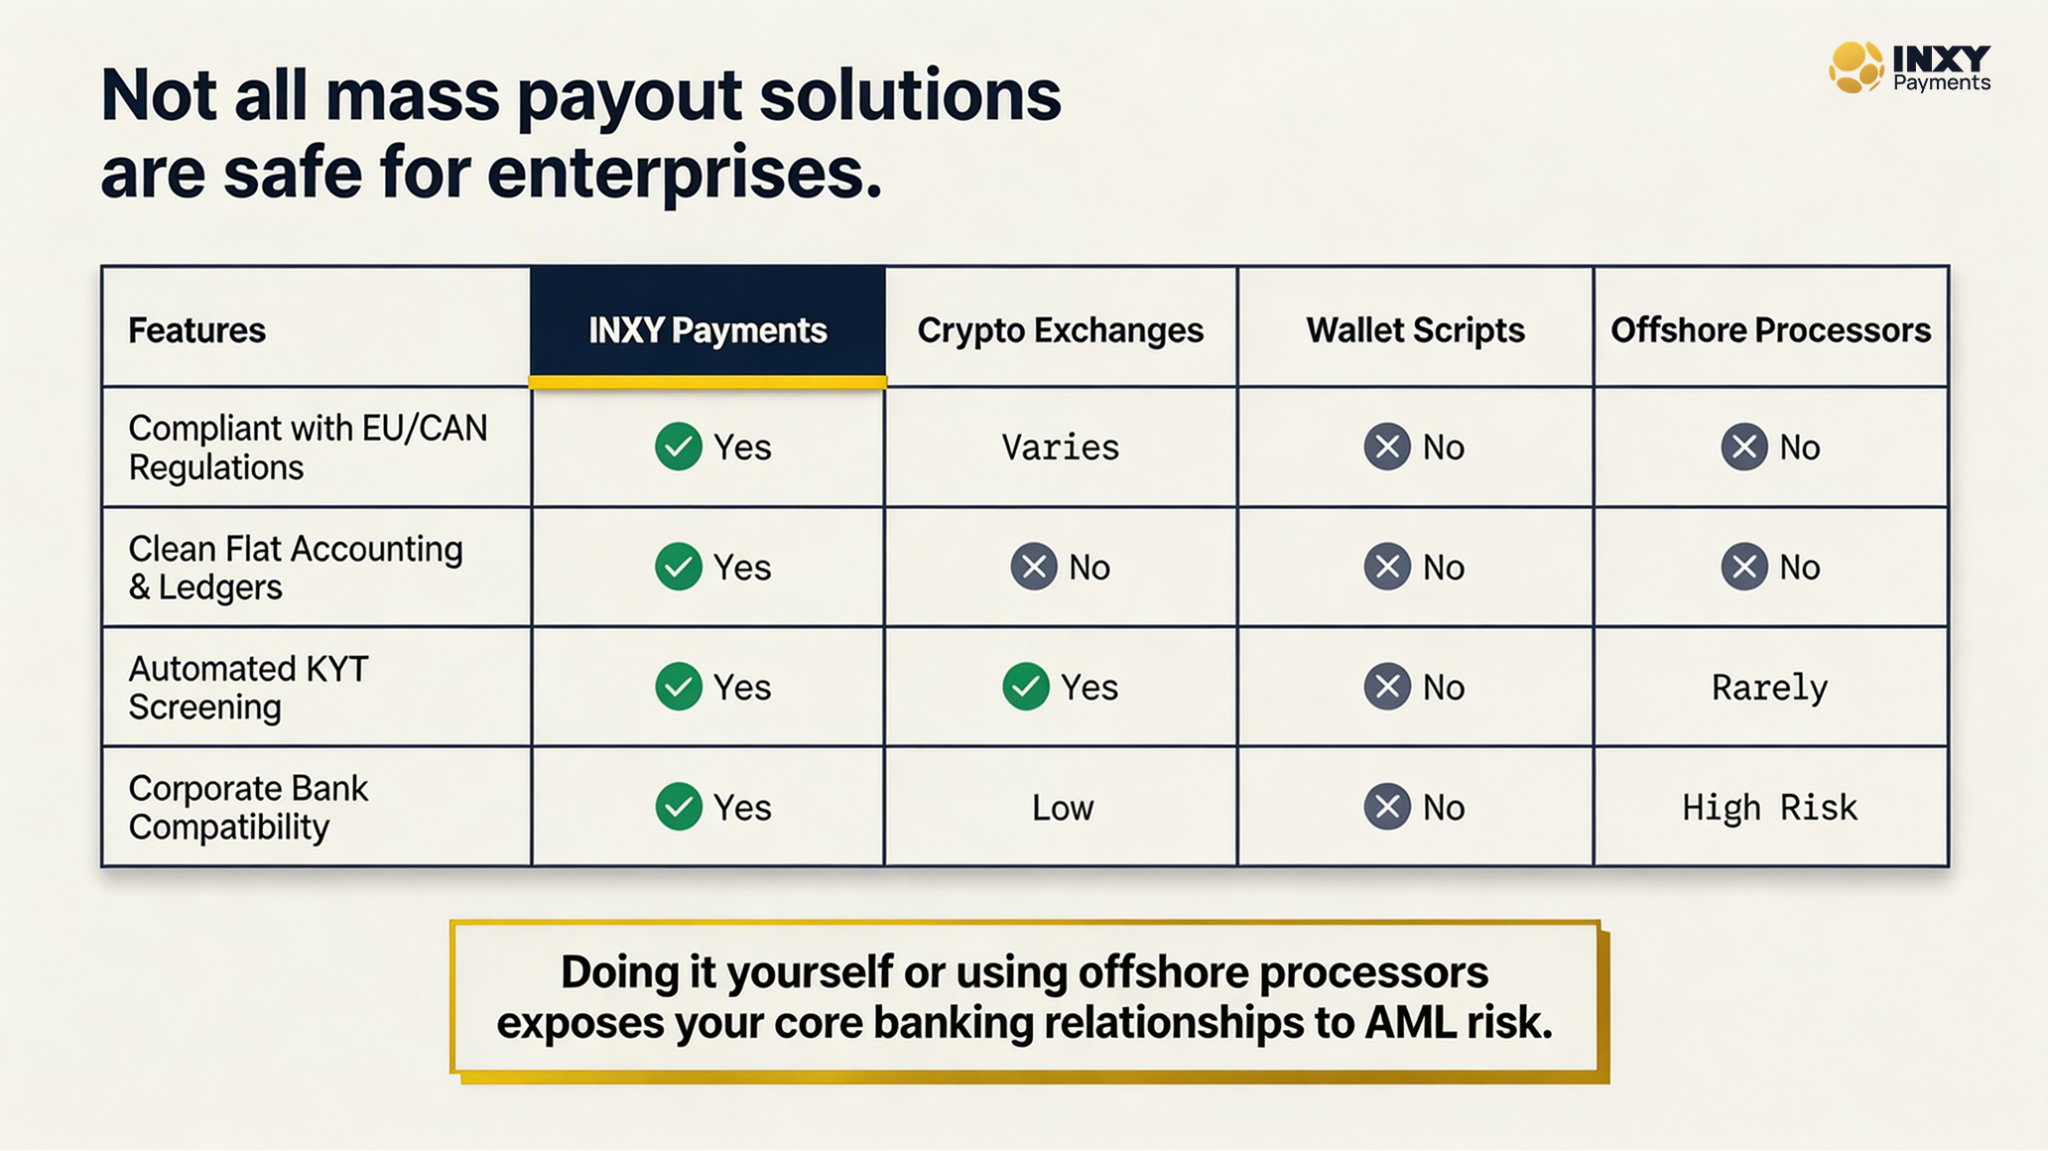
Affiliate networks operating in regulated verticals — iGaming, Forex, fintech — face increasing scrutiny on outgoing payment flows. INXY's compliance stack handles this automatically, without requiring programs to build their own AML logic.
KYT Screening on Every Outgoing Transaction
Every crypto payout processed through INXY is screened using KYT (Know Your Transaction) analysis. KYT evaluates the risk profile of recipient wallet addresses — flagging addresses associated with sanctions lists, mixers, or high-risk counterparties — before funds are broadcast on-chain.
Transaction Statuses: Cleared / Pending Review / On Hold
Each transaction is assigned a compliance status automatically: Cleared (processed immediately), Pending Review (flagged for manual review before settlement), On Hold (suspended pending investigation), or in rare cases Seized. Programs receive status updates via webhook, allowing downstream systems to handle edge cases programmatically.
Compliance Documentation for Your Records
INXY generates compliance documentation for all processed transactions. For affiliate programs that need to demonstrate AML controls to regulators, payment processors, or banking partners, this documentation provides an audit trail without requiring programs to build their own reporting infrastructure.
Who Uses INXY for Affiliate Crypto Payouts?
iGaming and Betting Affiliate Networks
iGaming is the highest-volume use case for crypto affiliate payouts. Programs managing hundreds of partners across multiple jurisdictions use INXY to run weekly BTC and USDT payment cycles. We handle payout cycles of any size — from dozens to hundreds of partners — without manual intervention; larger programs run sequential batches. KYT compliance is particularly valuable here, given the regulatory environment iGaming programs operate in.
Forex and Fintech Referral Programs
Forex brokers and fintech companies running IBs (Introducing Brokers) or referral programs use INXY to settle USDT and ETH commissions with partners globally. These programs often have partners in jurisdictions where receiving USD via wire is slow or restricted — crypto settlement sidesteps that friction entirely.
SaaS Partner and Reseller Programs
SaaS companies with global reseller networks use INXY to pay partner commissions in crypto as an alternative to Stripe payouts or wire transfers. The buy_crypto flag is particularly practical here: finance teams hold EUR or USD in the INXY balance, and INXY handles conversion and disbursement at the scheduled payout date — no active crypto treasury management required.
Frequently Asked Questions
How many affiliates can I pay in one batch?
INXY's Mass Payouts API is designed to handle payout cycles of any scale. There is no hard limit on the total number of recipients per cycle — whether you're paying dozens or hundreds of partners, the infrastructure scales to match your program's volume.
Do I need to hold crypto to pay affiliates?
No. If your INXY account holds EUR or USD, you can use the buy_crypto flag on any payout request. INXY will automatically purchase the required crypto at current market rates and disburse it to the recipient batch — without requiring you to manage a live crypto treasury.
Is KYB required to use INXY?
Yes. INXY is a B2B platform and requires KYB (Know Your Business) verification for all accounts. The KYB process is powered by Sumsub and typically completes within 1–2 business days. Individual accounts are not supported.
What cryptocurrencies can I pay affiliates in?
INXY supports BTC (Bitcoin mainnet), USDT (TRC-20 and ERC-20), ETH, and additional crypto assets. Different currencies can be used across different batches depending on affiliate preference and treasury composition.
How does AML compliance work for affiliate payouts?
Every outgoing transaction is screened using KYT (Know Your Transaction) analysis before broadcast. Transactions are assigned a status — Cleared, Pending Review, or On Hold — and INXY provides compliance documentation for all processed payments. Your team receives webhook notifications for any transactions that require attention.
Can I integrate INXY with my affiliate platform or ERP?
Yes. INXY provides a RESTful API with JSON payloads, webhook callbacks, and detailed transaction logs. Integration with affiliate tracking platforms, payroll systems, or ERP/treasury tools is straightforward for any engineering team familiar with REST APIs.
Ready to Automate Your Affiliate Crypto Payouts?
INXY is purpose-built for B2B programs that need reliable, compliant crypto disbursements at scale. Whether you're running a weekly iGaming payout cycle, a monthly Forex IB settlement, or a SaaS partner commission run — INXY's mass payout infrastructure handles the complexity so your team doesn't have to.
Get started at inxy.io — KYB takes 1–2 business days and your first affiliate payout batch can go out the same week.
Annual vs. Monthly SaaS Billing: Why Upfront Crypto Payments Win on Cash Flow
For most SaaS companies, monthly billing is the unexamined default. It lowers the barrier to entry, so it feels like the safe choice. But for B2B and high-ticket software, that default quietly works against you: it spreads revenue thin, exposes every renewal to a payment failure, and hands a chunk of your SaaS billing and payments flow to card networks that were never built for recurring, cross-border charges.
For most SaaS companies, monthly billing is the unexamined default. It lowers the barrier to entry, so it feels like the safe choice. But for B2B and high-ticket software, that default quietly works against you: it spreads revenue thin, exposes every renewal to a payment failure, and hands a chunk of your SaaS billing and payments flow to card networks that were never built for recurring, cross-border charges.
There is a structurally better model for B2B: annual upfront billing settled in crypto. Paid in stablecoins, an annual plan lands the full year of revenue immediately, removes eleven future points of failure, and eliminates chargebacks entirely. This article makes the cash-flow and retention case for upfront annual billing, and shows how stablecoin payments make it easy to offer.
The Hidden Cost of Monthly Card Subscriptions
A monthly subscription is not one payment — it is twelve chances per customer, per year, for something to go wrong. Card-based SaaS payment processing carries failure rates that compound across a subscriber base:
Involuntary churn — customers lost to failed payments rather than active cancellation — accounts for 20–40% of total churn, and up to 48% in higher-risk sectors.
Left unmanaged, failed payments can quietly consume up to 9% of total revenue.
Expired cards alone cause roughly 42% of failed subscription payments; the customer never chose to leave, the card simply lapsed.
Cross-border recurring charges are frequently flagged or declined by issuing banks, and chargebacks on digital goods drain revenue plus dispute fees.
Each monthly cycle re-exposes you to all of this. Annual billing collapses twelve renewal events into one — shrinking the failure surface by an order of magnitude — and, just as importantly, pulls a full year of cash forward instead of metering it out month by month.
Why Annual Upfront Billing Changes the Math
Upfront annual plans are not just an accounting convenience; they change the unit economics of the business. The advantage is sharpest when the customer actually prefers to pay this way — and crypto buyers do.
Cash flow now, not later. Collecting twelve months upfront strengthens working capital and reduces dependence on outside funding to finance growth.
A smaller churn surface. One payment per year means one renewal decision per year — and far fewer involuntary drop-offs from card failures.
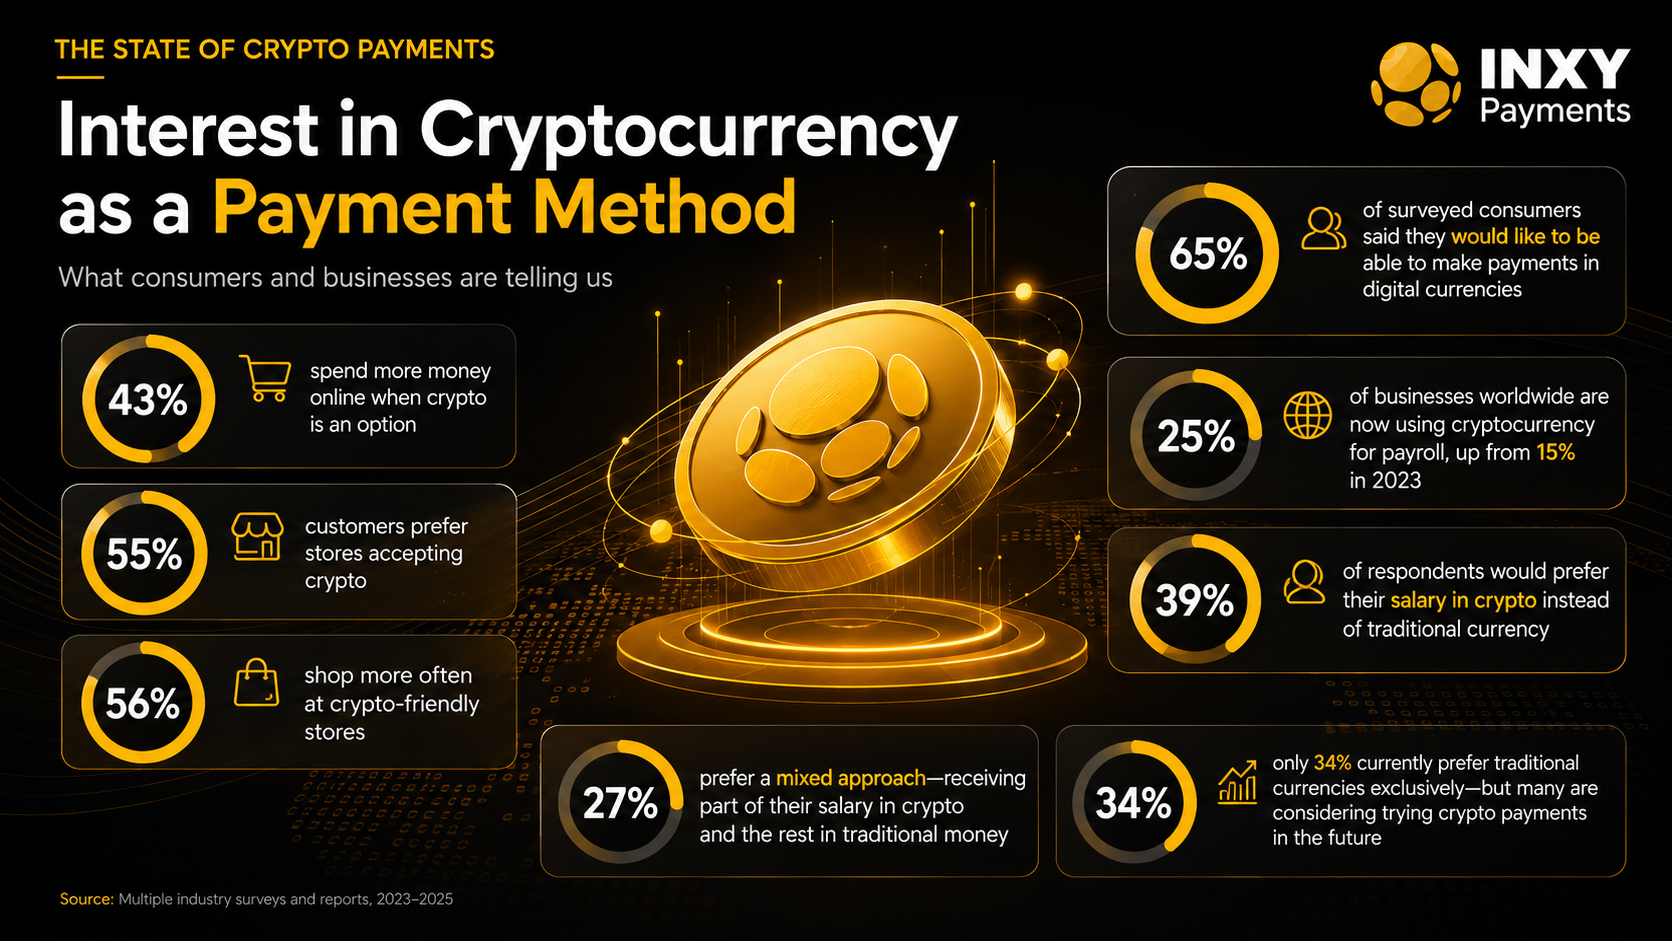
Higher lifetime value. Industry data shows crypto buyers spend roughly 2x more than traditional users, and around 43% spend more simply because crypto is offered as an option.
A buyer base that wants annual. About 60% of crypto users prefer to pay upfront for 12–36 month plans, versus only 20% of credit-card users — so offering crypto and annual pricing together is a natural fit.
With more than 824 million people globally owning crypto — over 10% of the world's population — the segment that prefers upfront, borderless payment is large and high-value, not niche.
Why Crypto Makes Annual Billing Easy to Sell
Blockchain payments are push-based and final — one confirmed transfer, no scheduled pulls. That property, which makes crypto awkward for monthly auto-billing, is exactly what you want for an annual upfront plan: a single, irreversible settlement that closes the deal.
Predictable Revenue Through Auto-Conversion
The usual objection — volatility — is solved at the gateway. When a client pays an annual license in a volatile asset, an auto-convert engine instantly settles it into stablecoins (USDT/USDC) or fiat (EUR/USD), so you book exact, predictable revenue. Stablecoins themselves are pegged 1:1 to the dollar, keeping SaaS payment management clean and auditable.
No Chargebacks, Global Reach, Instant Settlement
Zero chargebacks. On-chain payments are irreversible, eliminating friendly fraud and dispute fees on digital goods.
Borderless billing. A single settlement layer reaches customers who lack the international cards your checkout depends on, with no per-currency FX overhead.
Minutes, not days. Stablecoin payments settle in minutes instead of the 3–5 business days an international wire takes to clear.
Lower processing cost. Versus the typical 2.9% + $0.30 card fee plus cross-border markups, stablecoin transfers on networks like TRON (TRC-20) and Polygon cost a fraction of a percent.
How to Structure Annual Crypto Billing for Your SaaS
Adopting upfront annual crypto billing is a pricing-and-integration exercise, not a blockchain project:
Lead with discounted annual pricing. Make the annual plan the headline option and price the upfront discount so the cash-flow gain outweighs it.
Add crypto as a checkout option, not a replacement. Offer “Pay with Crypto” alongside fiat so you capture the high-LTV segment without disrupting existing customers.
Default to stablecoins on low-fee networks. Present USDT and USDC on TRC-20 and Polygon to keep customer-side network fees negligible and value stable.
Integrate via API or plugins, not smart contracts. Use a gateway's REST API or ready-made modules — including a native WHMCS module for hosting, cloud, and agency billing — to issue invoices and confirm payment automatically.
Auto-convert and reconcile. Convert incoming payments to stablecoins or fiat at the point of sale, and use transaction hashes plus CSV exports so finance can match every annual payment to an account.
Compliance and Accounting
Choosing a regulated gateway keeps annual crypto billing inside the regulatory perimeter rather than outside it. The essentials are KYC/AML on counterparties, transaction monitoring, and jurisdiction-aware handling — for example the EU's MiCA framework, which favors transparent, fully-backed stablecoins like USDC. Because stablecoins are dollar-pegged and settlements can auto-convert to fiat, your revenue stays denominated in a unit your accountants already use, with detailed reporting and exports for clean books.
How INXY Supports Annual Crypto Billing for SaaS
INXY is a regulated, enterprise-grade crypto payment gateway engineered for B2B and SaaS billing. Rather than forcing crypto into a monthly auto-billing mold, it leans into what the rail does best — high-value, upfront settlement:
Built for upfront cash flow. INXY deliberately bypasses standard auto-billing, making annual tariff plans the most profitable option for high-ticket B2B software — you receive the full yearly value immediately.
Auto-Convert Engine. Incoming payments in volatile assets convert instantly to stablecoins or fiat, so a $1,000 or $10,000 annual license books as predictable revenue.
Native SaaS integrations. Robust APIs and ready-made plugins, including a native WHMCS module tailored for hosting, cloud services, and digital agencies.
Zero chargebacks and built-in mass payouts. Irreversible settlement protects revenue, while CSV- or API-driven payouts handle affiliate and contractor disbursements.
A compliance-first stack. EU VASP (Poland), Canadian MSB, MiCA readiness, AML/KYT/KYC, and audit-friendly fiat reporting.
Does crypto support automatic monthly subscriptions?
Crypto payments are push-based, so they are not built for monthly card-style auto-charges. That is why the model that works best for B2B SaaS is annual upfront billing — a single, final payment that also improves cash flow.
How do we avoid volatility on a large annual payment?
A gateway with an auto-convert engine settles incoming crypto into stablecoins or fiat at the point of sale, so a five-figure annual license is booked at an exact, predictable value.
Will offering crypto cannibalize our fiat plans?
No — it is an additional checkout option. It tends to attract new, higher-LTV customers rather than shift existing ones, since a large share of crypto buyers are new to the merchant.
How hard is integration?
You connect a REST API or use ready-made plugins such as a native WHMCS module, rather than writing smart contracts. Most teams launch faster than opening a traditional merchant account.
Conclusion
Monthly card billing spreads SaaS revenue thin and re-exposes it to failed payments and chargebacks twelve times a year. Annual upfront billing — settled in crypto — flips that: a full year of cash collected now, one renewal decision instead of twelve, no chargebacks, and a high-LTV buyer base that prefers to pay this way. The rail's push-based finality is a feature here, not a limitation.
Ready to add upfront annual crypto billing to your checkout? See how INXY can power it at inxy.io.
What Are Web3 Payments? Blockchain & Smart Contracts Explained
“Web3 payments” describe a new way to move money in which value travels directly across a blockchain network instead of through banks and card schemes. Unlike traditional online transactions, blockchain payments settle peer-to-peer on a public ledger, are verifiable by anyone, and can run without a central intermediary holding the funds. For businesses, this means faster settlement, lower cross-border costs, and programmable money that can enforce its own rules.
“Web3 payments” describe a new way to move money in which value travels directly across a blockchain network instead of through banks and card schemes. Unlike traditional online transactions, blockchain payments settle peer-to-peer on a public ledger, are verifiable by anyone, and can run without a central intermediary holding the funds. For businesses, this means faster settlement, lower cross-border costs, and programmable money that can enforce its own rules.
This guide explains what web3 payments are, how they work under the hood, where smart contracts fit in, and how they compare to the crypto checkout flows most merchants already know. It is written for founders, finance teams, and product managers evaluating whether on-chain rails belong in their stack.
What Are Web3 Payments?
Web3 payments are transactions executed on decentralized blockchain networks, where ownership of funds is tied to a cryptographic wallet rather than a bank account. The term “web3” refers to the third era of the internet — one built on open, user-owned protocols. In a payment context, web3 crypto payments let a payer send value (typically stablecoins such as USDC or USDT, or assets like ETH and BTC) straight to a recipient’s wallet, with the network itself confirming and recording the transfer.
Three properties separate web3 payments from conventional digital payments:
Self-custody. The payer controls the funds via private keys until the moment of transfer — there is no card issuer or bank acting as gatekeeper.
On-chain settlement. The transaction is final once confirmed by the network, usually in seconds to minutes, with no multi-day clearing cycle.
Programmability. Logic can be attached to the payment itself, so funds release only when predefined conditions are met.
The market context matters. According to recent industry analysis, fiat-backed stablecoins surpassed $300 billion in market capitalization in late 2025, with annualized on-chain settlement volumes in the mid-$20-trillion range — evidence that web3 rails are moving from experiment to real economic activity.
It helps to see where web3 payments sit relative to terms you already use. “Crypto payments” is the umbrella term for paying with digital assets at all. “Web3 payments” is the subset that runs on open, permissionless networks with user-held funds — as opposed to a closed processor that simply accepts coins and settles them to your bank. That difference in architecture is what unlocks the speed, reach, and automation covered below.
How Web3 Payments Work: Blockchain & Wallets
Blockchain payments rely on three components working together: a wallet that holds the keys, a blockchain network that validates transactions, and (for business use) a gateway that translates the on-chain event into something an accounting system can read. Here is the flow in plain terms.
The role of self-custody wallets
A crypto wallet does not “store” coins; it stores the private keys that prove ownership of a balance recorded on-chain. When a customer pays, their wallet signs the transaction with that key, authorizing the network to move the balance to the merchant’s address. Because the key never leaves the user, there is no card number to steal and no chargeback to reverse — a structural difference from card payments.
On-chain settlement vs. traditional rails
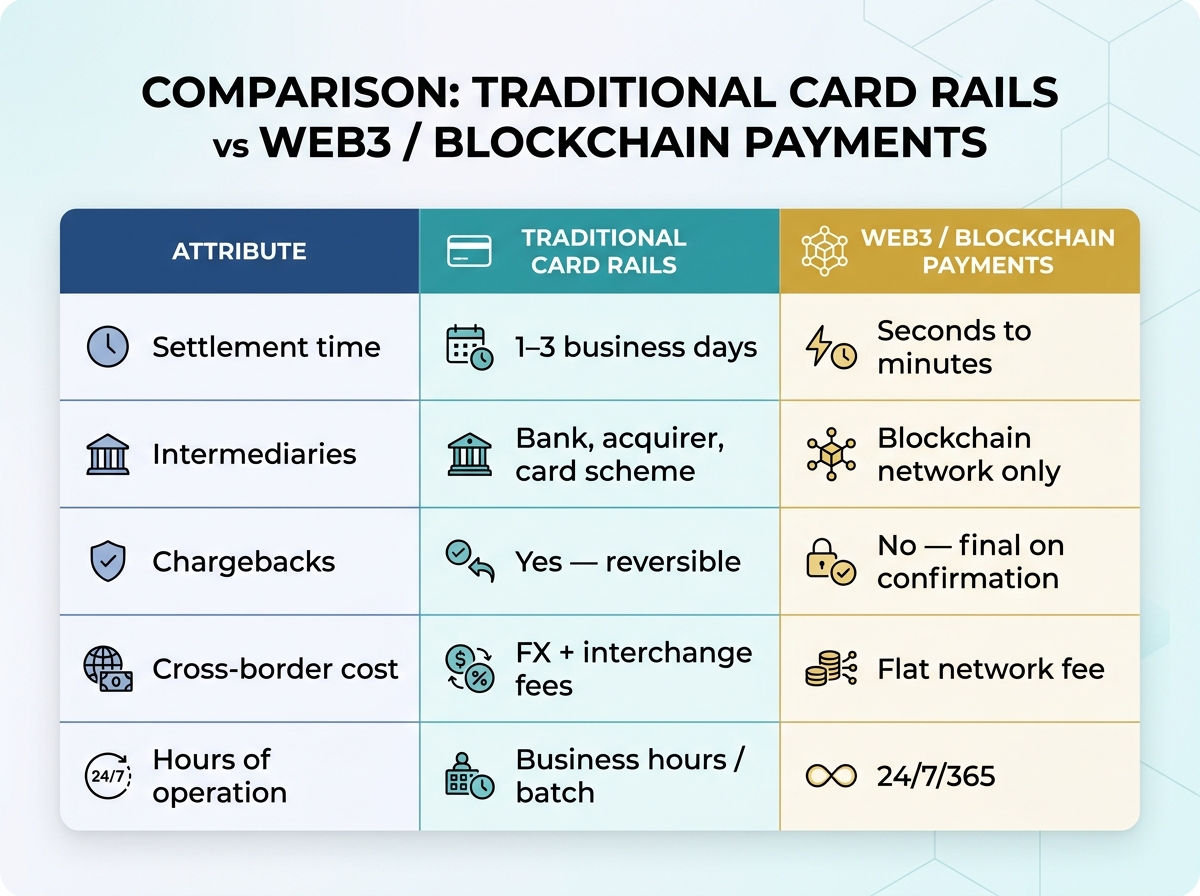
In a card transaction, authorization, clearing, and settlement happen across several institutions over one to three business days. With blockchain payments, validators confirm the transfer and write it to an immutable ledger in a single step. The table below summarizes the practical differences.
Smart Contract Payments Explained
Smart contract payments are blockchain transactions governed by self-executing code. A smart contract is a program deployed on-chain that automatically performs an action — release funds, split a payment, issue a refund — when its conditions are satisfied. No human has to intervene, and no party can alter the outcome once the contract is live.
Automated & programmable payments
This is where web3 moves beyond simple transfers. A smart contract can hold funds in escrow and release them only when a delivery is confirmed, automatically distribute revenue among several wallets, or stream a salary continuously over time. For businesses, programmable money reduces manual reconciliation and removes the trust gap in multi-party deals.
Consider a marketplace that owes three parties on every sale: the seller, an affiliate, and the platform itself. With cards, that single payment is captured, then split later through separate payout runs and reconciliation. A smart contract executes the split atomically — the moment funds arrive, each wallet receives its share in the same transaction. The same logic powers milestone-based contractor payments, automated refunds, and subscription renewals, all without a card on file or a manual approval step.
Escrow: funds lock until both sides meet their obligations.
Revenue splits: a single incoming payment is divided across partners in one transaction.
Recurring & usage-based billing: subscriptions and metered charges execute on-chain without a card on file.
Tokenized payment solutions
Tokenized payment solutions represent real-world value — a dollar, an invoice, a loyalty credit — as a transferable token on a blockchain. Stablecoins are the most widely used example: a token pegged 1:1 to fiat that combines the stability of a currency with the speed of crypto. Industry research estimates that B2B flows already account for roughly 40% of real-economy stablecoin payments and are growing about 65% per year, which is why tokenized settlement is becoming the default rail for cross-border business payments.
Web3 Payments vs. Traditional Crypto Checkout
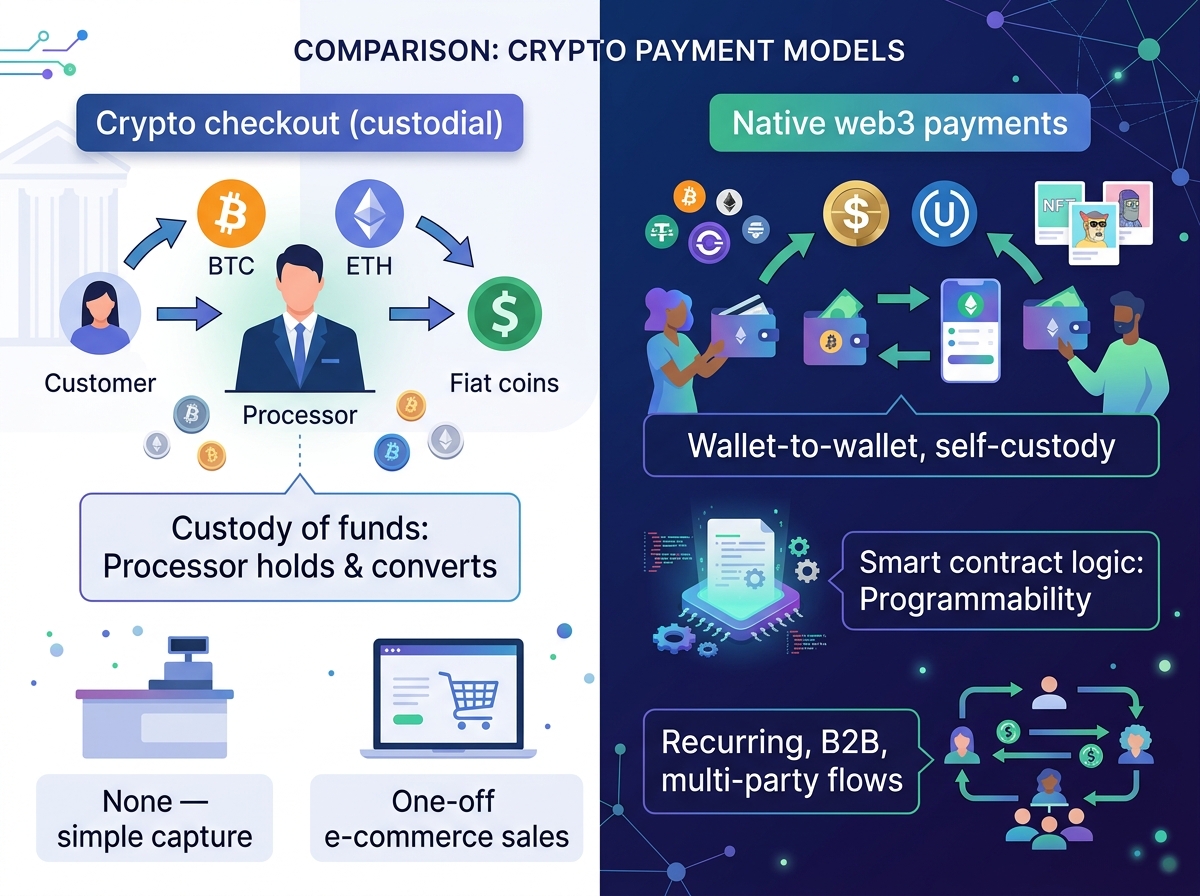
Many merchants already “accept crypto” through a hosted checkout that converts coins to fiat. That is a useful on-ramp, but it is not the same as a full web3 payment model. The distinction is about who controls the funds and whether the payment carries logic.
In practice the two coexist. A business might use a custodial checkout for retail customers while using native, programmable rails for supplier payouts and partner settlements. For a deeper breakdown of provider roles, see our guide on the difference between a crypto payment gateway and a processor.
Benefits & Risks for Businesses
Web3 payments — and the broader category of blockchain smart contracts for business — offer clear operational upside, but they come with trade-offs that finance and compliance teams should weigh.
Key benefits:
Near-instant, 24/7 settlement that frees up working capital.
Lower cross-border fees by removing correspondent-banking layers.
No chargebacks, reducing fraud exposure for digital goods.
Automation of escrow, splits, and recurring billing through smart contracts.
Risks to manage:
Price volatility on non-stablecoin assets — most businesses settle in stablecoins to neutralize this.
Irreversibility means errors and misdirected payments are hard to recover.
Regulatory obligations: under frameworks like the EU’s MiCA, you must work with a licensed VASP/CASP and apply KYC/AML and Travel Rule checks.
Smart-contract risk: poorly audited code can be exploited, so use vetted, audited contracts.
For most companies the practical answer is not to choose between safety and innovation, but to adopt web3 payments through a partner that has already solved custody, compliance, and key management. That keeps the operational benefits — speed, automation, global reach — while shifting the hardest security and regulatory work to infrastructure built for it.
How to Start Accepting Web3 Payments
You do not need to build blockchain infrastructure in-house. A compliant gateway abstracts the wallet, network, and conversion layers so you can accept on-chain payments with a standard integration. A practical path:
Choose your settlement asset. Stablecoins (USDC, USDT, DAI) are the standard for business to avoid volatility.
Select a regulated provider. Confirm licensing, multi-chain support, and KYC/AML coverage for your regions.
Integrate via API or plugin. Add the checkout or payout flow and connect webhooks to your back office.
Decide what to automate. Map which payments — escrow, splits, recurring — benefit from smart-contract logic.
INXY provides a regulated, EU-compliant gateway for exactly this. Explore the web3 payments solution and our smart-contract payment infrastructure, or read how to accept crypto payments in 2026 for the full setup walkthrough.
FAQ
What are web3 payments in simple terms? They are payments sent directly between crypto wallets over a blockchain, without a bank or card network in the middle. The network verifies and records the transfer.
Are web3 payments safe? The underlying blockchain settlement is highly secure and tamper-resistant. The main risks are user error, asset volatility, and smart-contract bugs — all manageable by using stablecoins, audited contracts, and a regulated gateway.
What is a smart contract payment? A payment controlled by on-chain code that executes automatically when set conditions are met — for example, releasing escrowed funds once delivery is confirmed.
How are web3 payments different from accepting Bitcoin at checkout? A standard crypto checkout is custodial and converts coins to fiat. Native web3 payments keep funds in self-custody and can carry programmable logic, making them better suited to recurring, B2B, and multi-party flows.