When closing high-ticket B2B SaaS deals or enterprise annual plans, traditional credit card processing often becomes a bottleneck rather than a solution. High cross-border fees and unexpected fund holds can paralyze your cash flow. In 2026, relying solely on legacy fiat processors is a risk. Your billing infrastructure needs to be as borderless and scalable as your software.
As we move deeper into 2026, SaaS billing has fundamentally evolved. While traditional fiat processors remain standard, the explosive demand for borderless, low-fee digital transactions makes cryptocurrency and stablecoin gateways a mandatory addition to any modern B2B tech stack. This guide breaks down the best payment gateways for SaaS businesses, comparing legacy providers with next-generation Web3 infrastructure to help you optimize your upfront revenue.
Key Features to Look for in a SaaS Payment Gateway
Before diving into the top providers, it is essential to define what makes a payment gateway effective for a SaaS and annual licensing model:
Global Reach & Multi-Currency: Support for international clients without exorbitant cross-border foreign exchange (FX) fees.
API & Native Integrations: Developer-friendly REST APIs and plugins for standard platforms (like WooCommerce, Shopify, or WHMCS).
Chargeback Protection: Mechanisms to protect your business from fraudulent chargebacks that persistently plague the digital goods industry.
Mass Payout Capabilities: Built-in tools to easily distribute affiliate commissions or international contractor payouts.
The Top Payment Gateways for SaaS in 2026
1. Stripe: The Traditional Fiat Giant
Stripe remains a dominant force in the SaaS ecosystem. Its robust API, advanced invoicing tools, and seamless checkout flows make it a default choice for many domestic startups.
Pros: Incredible developer tools, widespread consumer trust, and deep analytics.
Cons: High cross-border transaction fees and persistent vulnerability to chargeback fraud.
2. PayPal / Braintree: The Consumer Favorite
Braintree (owned by PayPal) offers extensive global brand recognition. It is an excellent choice for B2C software products looking for high conversion rates at checkout from everyday consumers.
Pros: High consumer trust, easy integration, supports Venmo and Apple Pay.
Cons: Strict compliance algorithms that can freeze funds without warning, high processing fees for international clients.
3. INXY Paygate: The Premier Web2 to Web3 Bridge
For modern SaaS companies, relying solely on traditional banking is a massive bottleneck. Enter INXY, a regulated, VC-backed cryptocurrency payment gateway that recently secured $3M from Flashpoint VC. INXY is specifically engineered for B2B enterprises and SaaS platforms looking to accept global payments without the friction of legacy banks. INXY acts as a seamless bridge, allowing you to offer a "Pay with Crypto" option while completely eliminating the technical risks normally associated with digital assets.
Boost Your Annual Payments: INXY Paygate strategically bypasses standard auto-billing. This is a massive advantage designed to boost your upfront cash flow. When dealing with high-ticket B2B software and large sums, utilizing stablecoins makes annual tariff plans the absolute most profitable option for both your business and your clients. You get the full yearly value immediately without the risk of monthly drop-offs.
The Auto-Convert Engine: The biggest fear for SaaS CFOs is crypto volatility. With INXY, if a client pays a $1,000 or $10,000 annual software license in Ethereum, the gateway's Auto-Convert feature instantly converts the incoming volatile asset into stablecoins (USDT/USDC) or fiat (EUR/USD). You get exact, predictable revenue.
Native SaaS Integrations: Instead of writing complex smart contracts, SaaS companies can use INXY’s robust APIs or ready-made plugins, including a native WHMCS module perfectly tailored for hosting, cloud services, and digital agencies.
Zero Chargebacks: Blockchain transactions are irreversible, meaning your business is completely protected from friendly fraud.
Built-in Mass Payouts: If you rely on an affiliate network, INXY allows you to automate global mass payouts via CSV uploads or API.
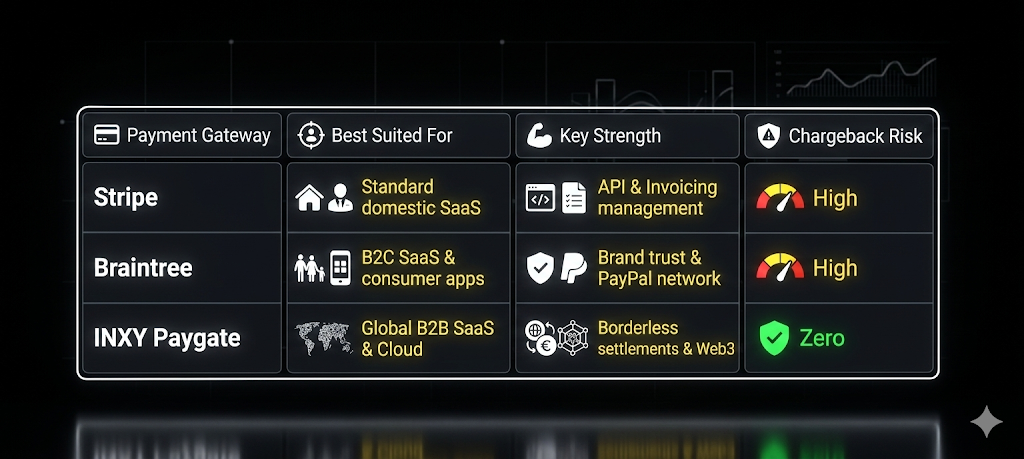
Feature Comparison Matrix
Choosing the right platform depends entirely on your target audience. Here is a high-level comparison of how these gateways stack up:
Why SaaS Businesses Are Adopting Crypto Invoicing
The shift toward stablecoin billing is not a temporary trend; it is a fundamental upgrade to global financial infrastructure. With over 824 million people globally owning crypto—representing more than 10% of the world's population—this is a massive, highly lucrative demographic ready to spend.
By integrating a Web3 gateway alongside your traditional fiat processors, you unlock several strategic advantages:
Massive Upfront Cash Flow: 60% of crypto users prefer to pay upfront for 12–36 month plans, compared to only 20% of credit card users.
Higher Spend & Unmatched LTV: Crypto buyers spend 2x more than traditional users. In fact, 43% of users spend more simply because crypto is offered as an option. Clients who pay in crypto consistently become the highest Lifetime Value (LTV) users—paying more and staying longer.
New Customer Acquisition: 40% of crypto clients are entirely new to the merchant, and 56% of users actively choose to shop more frequently at crypto-friendly businesses.
Lower Transaction Costs: Traditional gateways charge 2.9% + $0.30 per transaction, plus heavy cross-border fees. Crypto payments settle for fractions of a percent, saving high-volume companies thousands of dollars on annual contracts.
Instant Global Settlement: Instead of waiting 3 to 5 business days for an international wire transfer to clear, stablecoin payments settle in minutes.
Conclusion: Future-Proof Your SaaS Billing
In an increasingly borderless digital economy, restricting your customers to legacy credit card processing is a critical mistake. While platforms like Stripe and Braintree excel in their respective domestic markets, the future of global SaaS billing relies on secure, instant, and borderless transactions.
By implementing a specialized gateway, you can bypass the traditional hurdles of international finance. You gain the ability to tap into a high-spending demographic, automate your affiliate mass payouts, and completely eliminate chargeback fraud—all while receiving predictable, auto-converted fiat or stablecoin settlements. It is time to expand your checkout options and embrace the next generation of digital payments.
Sending crypto in 2026 is faster and more accessible thanks to improved wallets, lower network fees, and advanced blockchain technologies. This step-by-step guide explains how to send BTC, USDT, USDC, and ETH securely, compare transaction fees, track transfers, and stay ahead of future crypto transaction trends.
Cryptocurrency might sound complicated, but it's quite straightforward once you get the hang of it. At its core, cryptocurrency is a type of digital money. Unlike traditional currencies like the dollar or euro, crypto doesn't rely on banks. Instead, it uses technology called blockchain to keep track of transactions. This technology is like a digital ledger that records every transaction made.
Bitcoin is the most famous cryptocurrency, but there are many others like Ethereum, USDT, and USDC. Each has its own features and uses. For instance, Bitcoin is often used as a store of value, like gold. Ethereum, on the other hand, is known for its smart contracts. These are like self-executing contracts with the terms directly written into code.
Sending crypto involves creating a digital wallet. This wallet is a bit like a bank account but only for digital currencies. To send crypto, you need the recipient's wallet address. It's important to double-check this address because once you send crypto, you can't get it back if the address is wrong. Crypto transactions are generally fast and can be cheaper than traditional money transfers.
Choosing the Right Crypto Payment Platform
When it comes to sending crypto, picking the right payment platform is crucial. The options have expanded greatly by 2026, offering more choices than ever. But with choice comes the challenge of finding the best fit for your needs. Let's break down what to look for in a crypto payment platform.
First, consider the transaction fees. Different platforms charge varying fees for sending crypto. Some offer lower fees for particular cryptocurrencies like BTC, USDT, USDC, or ETH. It's smart to compare these fees as they can affect the overall cost of your transactions. A platform with lower fees can save you money in the long run.
Next, think about ease of use. Not all platforms are user-friendly. If you're new to crypto, look for a platform that offers a straightforward interface. Tutorials and customer support can also be a big help. A good platform should make the process of sending crypto as simple as possible.
Security is another key factor. You need a platform that keeps your funds safe. Look for platforms with strong security measures, such as two-factor authentication and encryption. You want assurance that your crypto won't fall into the wrong hands.
Consider the platform's reputation and reviews. A platform with positive reviews from other users can be a good sign. Check forums and social media for feedback. Sometimes, the experiences of others can guide you toward the right choice.
Finally, look at the supported cryptocurrencies. If you plan to send BTC, USDT, USDC, or ETH, make sure the platform supports these. Some platforms offer a wider range of cryptocurrencies, which can be useful if you plan to diversify your holdings.
In essence, selecting the right crypto payment platform involves balancing fees, usability, security, reputation, and currency support. By focusing on these aspects, you'll be well on your way to finding a platform that suits your needs.
Setting Up Your Crypto Wallet (ссылка на блог)
Setting up a crypto wallet is a crucial step in sending crypto. It's like having a digital bank account where you store your cryptocurrencies. Let's break down the process into simple steps.
First, you'll need to choose the type of wallet. There are several options like hardware wallets, mobile wallets, and desktop wallets. Each has its own benefits. For instance, hardware wallets are secure because they store your crypto offline. Mobile wallets are convenient for everyday use.
Once you've picked a wallet type, it's time to download or purchase it. If you're going for a software wallet, visit the official website or app store to download it. Be cautious of fake sites and apps. For hardware wallets, buy from a trusted source to avoid counterfeit products.
After installing your wallet, you'll need to create an account. During this step, you'll set up a strong password. This is vital for your wallet's security. You might also be required to set up two-factor authentication for an extra layer of protection.
You'll then receive a recovery phrase. This is a set of words you'll need if you ever lose access to your wallet. Write it down and store it somewhere safe. Never share this phrase with anyone.
Finally, add some crypto to your wallet. You can do this by purchasing crypto from an exchange or receiving it from someone else. Make sure to double-check wallet addresses when sending or receiving crypto to avoid mistakes. With these steps, you're ready to manage your crypto securely.
How to Send BTC, USDT, USDC, and ETH
Sending crypto can seem tricky, but it's quite simple once you get the hang of it. Let's break it down. First, you need a wallet. There are many options, like hardware wallets, mobile apps, or online platforms. Choose one that fits your needs and create an account.
When you're ready to send crypto, you'll need the recipient's wallet address. It's a long string of letters and numbers, so double-check it to avoid mistakes. For example, if you're sending Bitcoin (BTC), make sure the address is a BTC address. Sending crypto to the wrong type of address can result in a loss.
Next, enter the amount you want to send. Most platforms let you choose how much you want to pay in fees. Lower fees mean slower transactions, while paying more can speed things up. It's a balance between cost and time.
Once everything looks good, confirm the transaction. Some platforms may ask for additional verification, like a code sent to your phone or email. This step helps keep your crypto safe. After confirmation, the transaction is processed. Depending on the network, it can take a few minutes to complete.
Keeping track of the transaction is easy. You can use a blockchain explorer to see its status. Just enter your transaction ID or wallet address to follow its progress.
Comparing Transaction Fees
When sending crypto, transaction fees can vary greatly depending on the network you choose. Let’s break this down with a few clear examples.
Imagine you’re sending Bitcoin (BTC). The Bitcoin network can have relatively high fees, especially during periods of high demand. This often makes small transactions less cost-effective.
Now consider Ethereum (ETH). Ethereum transaction fees, known as gas fees, fluctuate depending on network congestion. During peak activity—such as popular NFT launches or intense DeFi usage—these fees can increase significantly.
The same principle applies to stablecoins like USDT and USDC. While their value remains stable, transaction fees depend entirely on the blockchain network used. An important detail to keep in mind is that gas fees are always paid in the native token of the blockchain, not in the stablecoin itself.
For example, if you send USDT on the Ethereum network (ERC-20), you must have enough ETH in your wallet to cover the gas fee. Similarly, when sending USDT on the Tron network (TRC-20), you need to hold TRX in addition to USDT. Without the native token on your balance, the transaction cannot be processed.
This is why networks like Tron are often chosen for USDT transfers—fees there are usually much lower. However, it’s essential to monitor your balance of native coins (ETH, TRX, etc.) to avoid failed transactions.
When choosing how to send crypto, always compare current network fees and make sure you have enough of the required native token. This approach helps keep your transactions smooth, predictable, and cost-effective.
Tracking Your Crypto Transactions
Keeping tabs on your crypto transactions can seem like a puzzle at first. Yet, with a few simple steps, it can become second nature. When you send crypto, each transaction gets recorded on a public ledger called a blockchain. This ledger is like a big book that everyone can see but no one can change. It helps ensure transparency and security.
To start tracking, you'll need a wallet. This is like your digital pocket for holding cryptocurrencies. Each wallet has a unique address, much like your house address, but for crypto. When you send crypto, it gets recorded with this address. Many wallets offer features allowing you to see your full transaction history. This is handy for checking past transfers or seeing who you've sent crypto to.
For those who like visuals, some platforms provide charts and graphs that show your transaction activity over time. These can help you spot patterns or unusual activity. If you're using a crypto payment platform, they might offer additional tools for managing and viewing your transactions. Some even offer alerts to notify you of any new activity, ensuring you're always in the loop.
If you're dealing with several types of crypto like BTC, USDT, USDC, or ETH, separate wallets might be needed. This keeps things organized and prevents confusion. For those wanting to dive deeper, blockchain explorers are available. These are online tools that let you search a transaction by entering your wallet address. They offer detailed info, such as transaction status and fees paid.
Tracking your crypto transactions isn't just about staying organized. It's a way to protect your crypto and understand your spending habits. With these tools, you can manage your crypto finances in a smart and secure way.
Future Trends in Crypto Transactions
The world of cryptocurrency is always on the move. As we look to 2026, several exciting trends are shaping how people send crypto. These changes are not just about technology but also about how we use crypto in everyday life.
One major trend is the rise of decentralized finance, or DeFi. DeFi platforms allow users to conduct financial transactions without a central authority, like a bank. This means lower fees and more control over your money when you send crypto. DeFi is growing fast, and more people are using it for everything from loans to savings accounts.
Another trend to watch is the integration of crypto into traditional financial systems. More banks and financial institutions are starting to accept and use cryptocurrencies. This means you might soon be able to send crypto directly from your bank account. It's a big step towards making crypto a part of everyday financial activities.
In addition to these changes, there is also a focus on improving the speed and efficiency of crypto transactions. Technologies like the Lightning Network for Bitcoin and Ethereum 2.0 are being developed to make transactions faster and cheaper. This could make sending crypto as quick and easy as sending a text message.
Security is another important area of development. As more people use crypto, the need for secure transactions becomes even more critical. New security measures, such as multi-signature wallets and advanced encryption techniques, are being introduced. These tools help protect users' funds and personal information.
Moreover, the use of stablecoins like USDT and USDC is growing. These are cryptocurrencies pegged to stable assets like the US dollar. They offer the benefits of digital currencies without the volatility. This makes them an attractive option for people looking to send crypto with minimal risk.
Lastly, there is an increasing focus on regulation. Governments around the world are working on new laws to govern cryptocurrency use. While some fear that regulation could stifle innovation, it could also make crypto more reliable and accessible to everyone.
As we move forward, these trends will shape the future of crypto transactions. Whether you're a seasoned investor or a newcomer, keeping an eye on these developments can help you make informed decisions about how to send crypto. The landscape is evolving, and with it, new opportunities are emerging for everyone.
FAQ
What is cryptocurrency and why are BTC, USDT, USDC, and ETH commonly used for sending?
Cryptocurrency is a digital or virtual form of currency that uses cryptography for security. BTC (Bitcoin), USDT (Tether), USDC (USD Coin), and ETH (Ethereum) are commonly used due to their widespread acceptance, liquidity, and relatively stable values, making them ideal for transactions.
How do I choose the right crypto payment platform for sending crypto with low fees?
When selecting a crypto payment platform, consider factors such as transaction fees, user interface, security features, and supported cryptocurrencies. Platforms like Binance, Coinbase, and Kraken are popular due to their competitive fees and reliability.
What steps are involved in setting up a secure crypto wallet?
To set up a secure crypto wallet, first choose between a hardware wallet (for maximum security) or a software wallet (for convenience). Download the wallet app or set up the hardware device, create a strong password, and ensure you have a backup of your recovery phrase.
Can you provide a step-by-step guide on sending BTC, USDT, USDC, and ETH?
Open your crypto wallet and select the cryptocurrency you wish to send.
Enter the recipient's wallet address.
Specify the amount to send.
Review the transaction details, including network fees.
Confirm and authorize the transaction.
Wait for transaction confirmation on the blockchain.
How can I compare transaction fees across different networks and platforms?
To compare transaction fees, research and compare the fee structures of each platform, focusing on network fees, withdrawal fees, and any additional service charges. Tools like CoinGecko and CoinMarketCap provide up-to-date fee comparisons.
What methods are available for tracking my crypto transactions?
You can track your crypto transactions using blockchain explorers such as Etherscan for ETH and its tokens or Blockchain.com for BTC. These tools allow you to enter the transaction ID to view the status and confirmations.
What future trends can we expect in crypto transactions by 2026?
By 2026, expect increased adoption of Layer 2 solutions for faster and cheaper transactions, greater integration of AI for improved fraud detection, and wider acceptance of crypto payments in mainstream finance, enhancing user experience and security.
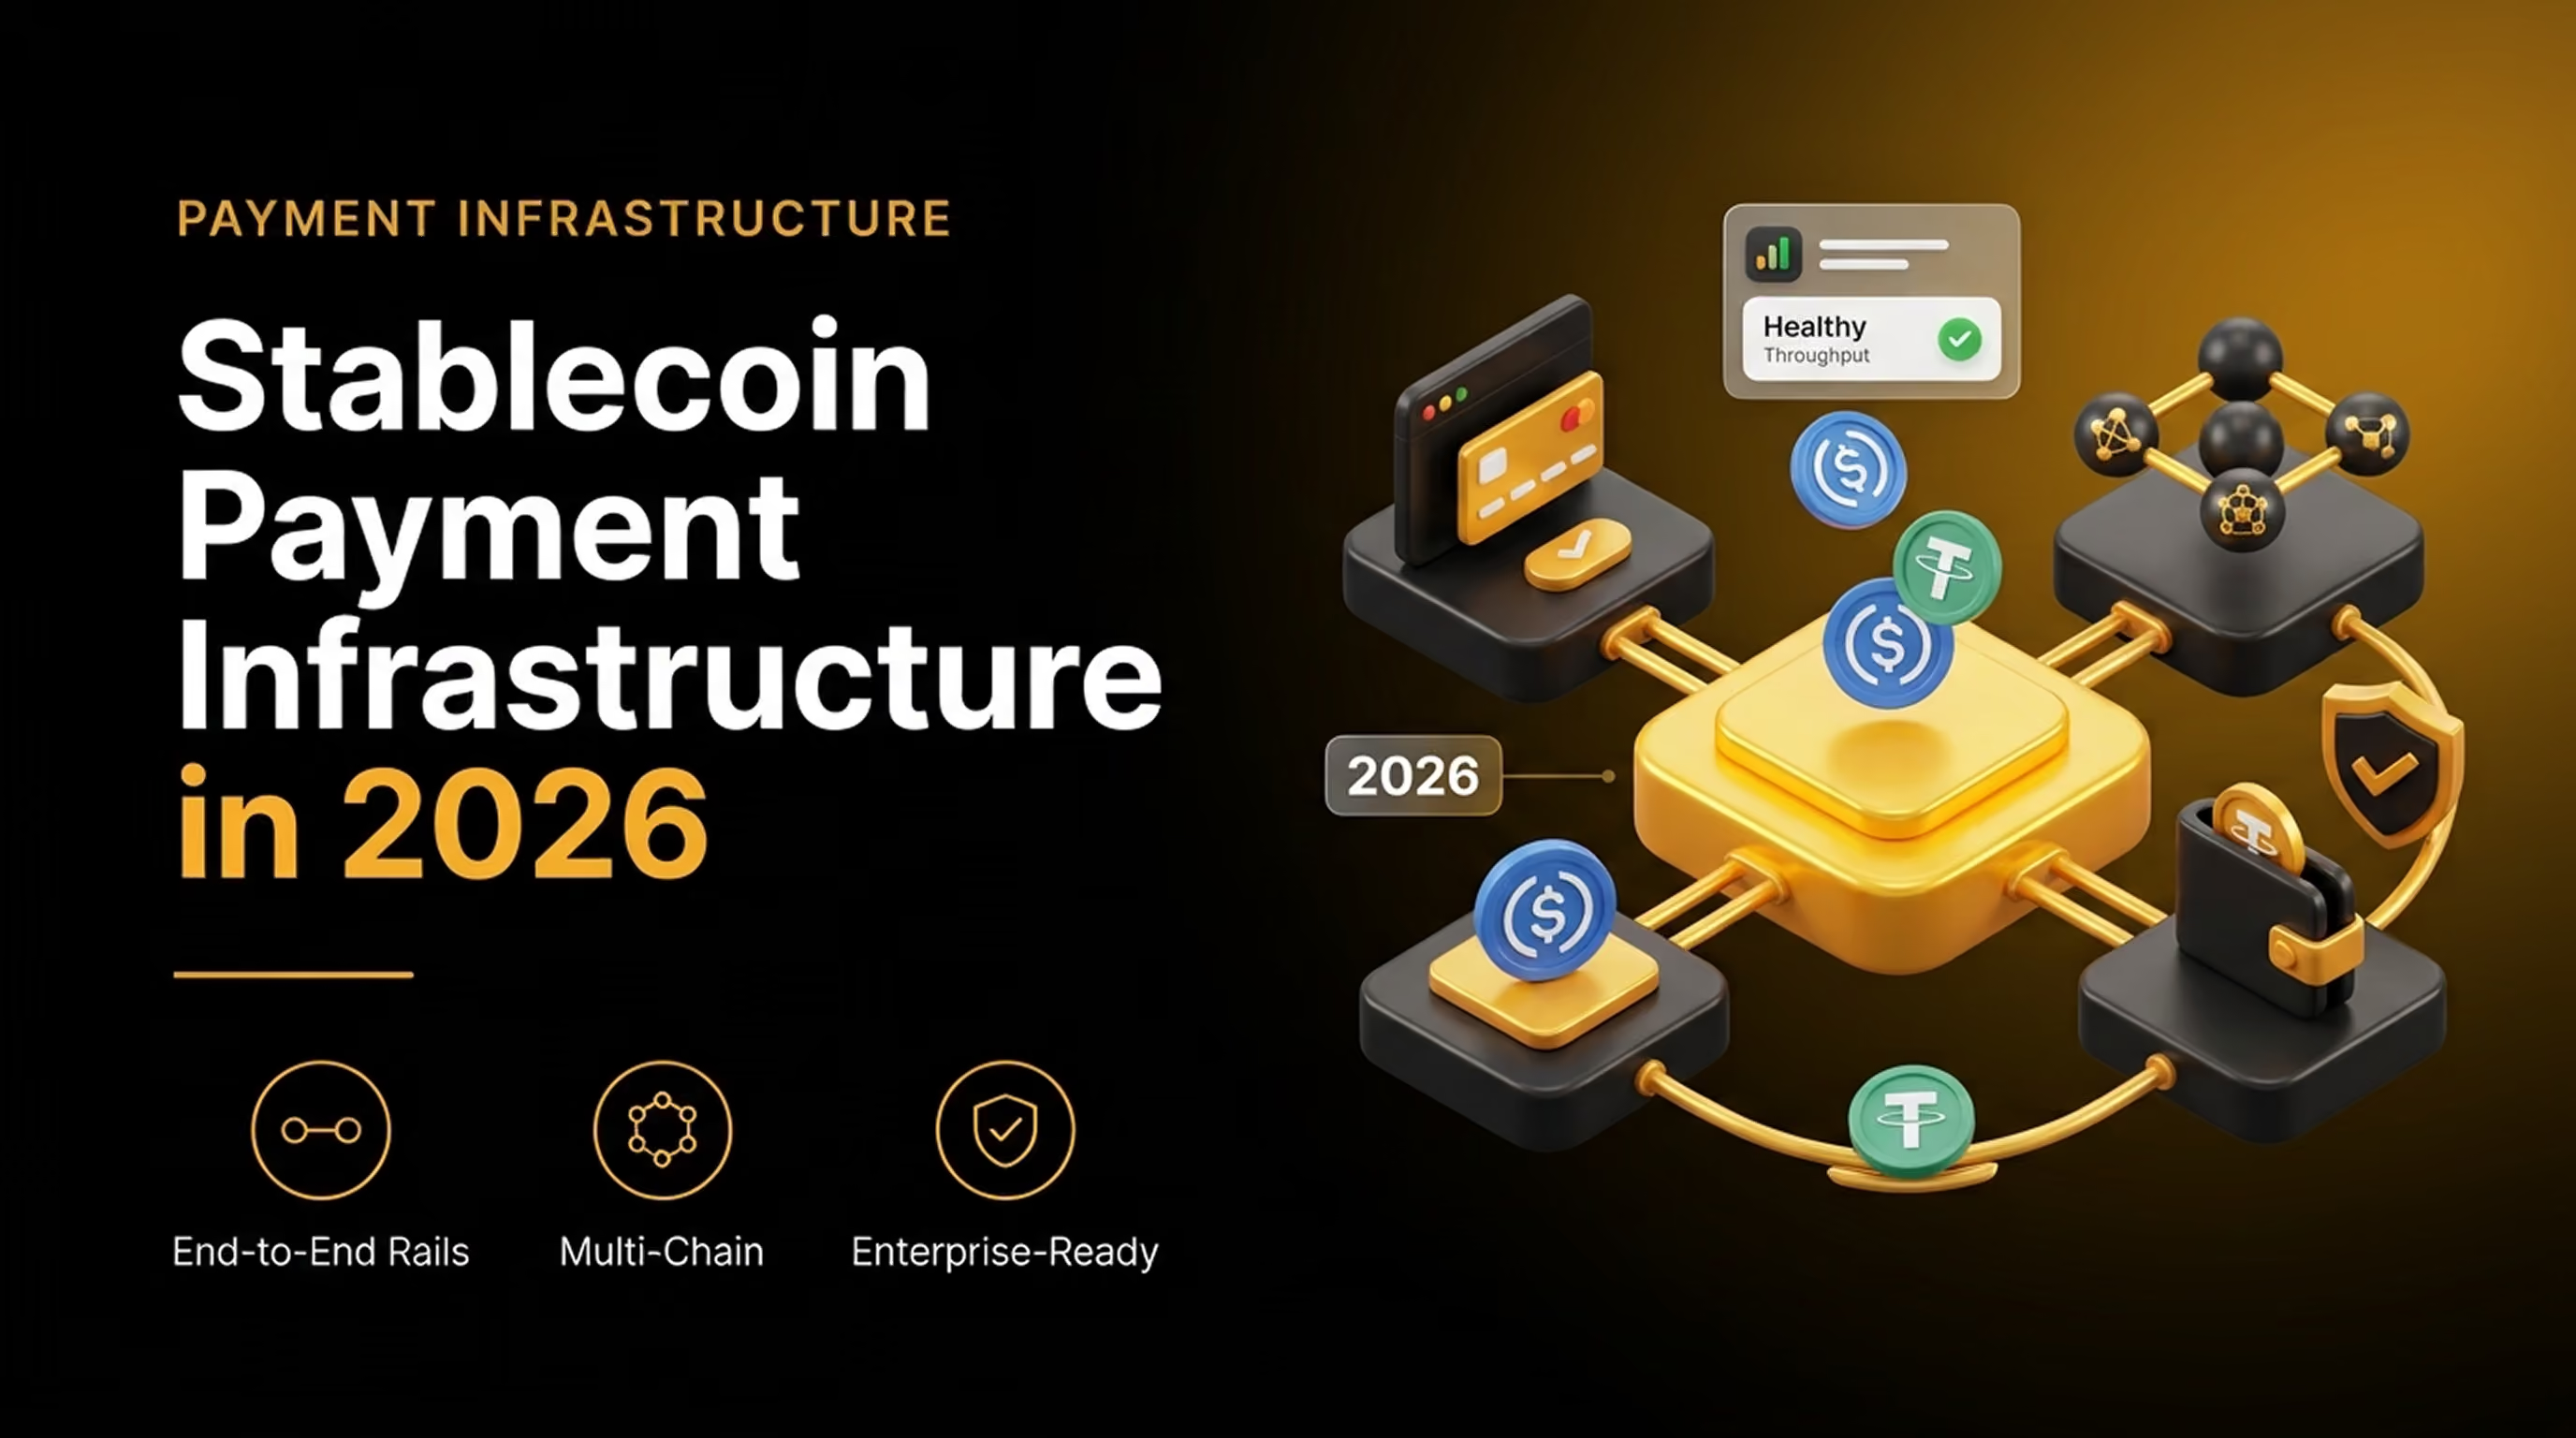
The most important shift in digital payments this year is not a new chain or a new token. It is the quiet realisation that stablecoins have crossed from speculation into infrastructure. The Paypers’ Global Stablecoins Report 2026 puts total stablecoin market capitalisation at roughly USD 317.9 billion, with projections that it could exceed USD 2 trillion as institutional participation accelerates — and some contributors put the figure closer to USD 4 trillion by 2030. At INXY, we read those numbers differently from most. The headline is not the size of the market. It is that stablecoins have become one of the first blockchain-based instruments to show clear product-market fit in payments.
The most important shift in digital payments this year is not a new chain or a new token. It is the quiet realisation that stablecoins have crossed from speculation into infrastructure. The Paypers’ Global Stablecoins Report 2026 puts total stablecoin market capitalisation at roughly USD 317.9 billion, with projections that it could exceed USD 2 trillion as institutional participation accelerates — and some contributors put the figure closer to USD 4 trillion by 2030. At INXY, we read those numbers differently from most. The headline is not the size of the market. It is that stablecoins have become one of the first blockchain-based instruments to show clear product-market fit in payments.
That single fact reframes the question every finance team, PSP, and merchant should be asking. It is no longer “should we look at stablecoins?” It is “which payment flows should run on them, and what stablecoin payment infrastructure do we need to make that safe, compliant, and economical?” This article is our read of the report’s data — and what it means for businesses that want to accept stablecoin payments, automate payouts, and move value across borders without rebuilding the financial stack from scratch.
Stablecoins have reached product-market fit in payments
For a decade, crypto payments were a promise: faster, cheaper money movement that never quite arrived at scale. What changed is not the blockchain — it is the infrastructure wrapped around it. The report is blunt on this point, describing stablecoins as one of the first blockchain-based instruments to demonstrate clear product-market fit in payments, increasingly used for cross-border settlement, treasury operations, merchant payouts, and everyday commerce.
The adoption base is real, not theoretical. Triple-A’s data cited in the report shows cryptocurrency ownership rising from around 560 million people in 2024 to roughly 700 million in 2026 — about 8.5% of the global population. These are not all traders. A growing share are freelancers, remote workers, and businesses that earn and hold digital dollars and want to spend or settle them without friction. Demand for a usable rail already exists; the constraint has been supply of trustworthy infrastructure.
Our view is simple. The metric that matters is not the market cap of crypto. It is the number of businesses that can use stablecoins to solve a concrete money problem — a supplier that needs paying today, a payout that needs to clear over a weekend, a treasury balance stranded behind a banking cut-off. That is the lens we apply to every number below.
Enterprise adoption is at an inflection point
Awareness of stablecoins among enterprises is now nearly universal, yet active production use remains modest. That gap is exactly what an inflection point looks like. In the EY-Parthenon survey referenced in the report (n=350), a majority of current non-users said they expect to begin using stablecoins within the next six to twelve months. The conversation inside finance teams has moved from “should we look at this?” to “where should we use it first?”
The intent is concentrated, not scattered. Among corporates asked which use cases they are most interested in over the next five years, the top answers were paying suppliers cross-border (77%), accepting cross-border business payments (49%), and accepting domestic business payments (37%). In financial services specifically, 91% of respondents said stablecoins would become a top priority or receive more attention. This is a back-office, treasury-first story — the place where return on investment is clearest and operational risk can be tightly controlled.
One data point matters more than any other for how this market will be served. When corporates were asked how important it is that their existing banking or payments provider supports stablecoins, 81% said it was critical or important, and 68% said they would prefer a bank-grade issuer. In other words, most businesses do not want to become crypto companies. They want to reach stablecoin capability through providers they already trust, embedded into the ERP and treasury systems they already run. Interoperability beats novelty every time.
Cross-border is the killer use case — but only where legacy rails fail
Cross-border payments lead enterprise adoption for a practical reason: this is where the old process is genuinely broken. A traditional international transfer can take days, pass through several correspondent banks, and leave money stranded in transit. Stablecoins offer near real-time settlement, 24/7 availability, and on-chain visibility — and the economics can be decisive. Among organisations already using stablecoins, 41% report cost savings of 10% or more compared with traditional methods, with the largest gains in cross-border B2B, where correspondent fees, FX spreads, and reconciliation costs stack up.
But the honest version of this story is geographic, and we insist on telling it that way. In Europe, where SEPA Instant already moves money in seconds at near-zero cost, the incremental advantage of a stablecoin for a domestic transfer is small. The value appears on corridors where legacy infrastructure fails. The report cites OpenPayd’s point that a USD 200 remittance to Sub-Saharan Africa can cost more than 8%, against a global average above 6% — and that stablecoins can cut that by over 75%, going as low as 0.5% when paired with reliable on- and off-ramps. MetaComp describes a payment from the UAE to Singapore that takes two to five days through correspondent banking settling in roughly 20 minutes at about half the cost.
So the right question is not “will stablecoins replace banks?” It is “which payment flow should run on which rail?” Stablecoins are not a universal upgrade; they are a precise tool for corridors that are slow, expensive, or fragmented. Matching the right rail to the right flow, market by market, is the actual work — and it is the work we build infrastructure to automate.
The cost nobody talks about: on-ramp and off-ramp economics
Here is the trap that sinks naive stablecoin projects, and the report is refreshingly direct about it. The blockchain fee is only a fraction of the true cost. Moving money into a stablecoin (the on-ramp) and back into local fiat (the off-ramp) is not free. Depending on provider, corridor, and volume, conversion fees run from 0.5% to more than 2% per leg — 1% to 4% on a full round trip. For a business with thin margins, that can erase the headline saving entirely.
The lesson we draw is one we design around every day: the cheapest blockchain transaction does not automatically produce the cheapest payment. Any honest assessment of stablecoin economics must include the full on/off-ramp cost, not just the on-chain fee. This is precisely why liquidity, FX, conversion, and settlement infrastructure matter so much — and why the industry is consolidating around orchestration layers such as Circle’s Payments Network (CPN) and cross-chain protocols like CCTP that move USDC between blockchains without costly bridges. The economics only work when at least one party can hold and route stablecoins natively, and when conversion is priced in basis points rather than percentage points.
For most businesses, building that liquidity and conversion layer in-house is neither realistic nor wise. The competitive edge is not owning a wallet; it is reaching deep, well-priced liquidity through infrastructure that already has it.
The hard part is no longer the blockchain — it is everything around it
If there is one theme the report returns to again and again, it is this: the technology is ready and has been for years. What was missing was the infrastructure required to run stablecoin flows safely, at scale, through systems businesses already understand. Companies need compliance, liquidity, fiat connectivity, reconciliation, custody, and orchestration wrapped around the stablecoin rail. That is where the market gets interesting — and where the winners will be decided.
Compliance is becoming part of the product
Regulation has flipped from the biggest barrier to an adoption enabler. Frameworks such as the GENIUS Act in the US and MiCA in the EU now give issuers and providers a clearer operational footing, especially for bank-issued or bank-distributed stablecoins that meet defined reserve, compliance, and governance standards. The question is no longer whether stablecoins are “too risky.” It is whether a company’s infrastructure is good enough to use them safely.
That raises the bar on operations. KYC, AML, Travel Rule obligations, wallet screening, and transaction monitoring all still apply — and adapting them to on-chain flows is a genuine engineering challenge. The report notes that redundant, repeated KYC is a real drag on growth: across the industry, 25–35% of users abandon onboarding when asked to upload an ID and selfie, while modern compliance engines can screen over 99% of transactions within seconds. Compliance is no longer a checkbox bolted on at the end. It is part of the product, and it has to be fast enough not to kill conversion.
Orchestration and the multi-rail future
The report’s central strategic conclusion — and ours — is that stablecoins will not replace every payment rail. The likely future is multi-rail: bank transfers, instant-payment networks, and stablecoins operating side by side, each carrying the flows it serves best. Stablecoins shine where traditional rails are slow, costly, or fragmented; in highly efficient domestic markets, their edge narrows.
That makes orchestration the decisive capability. Orchestration is the end-to-end management of a payment’s journey — deciding, for each transaction, whether to use a stablecoin, which issuer and chain to select, and when to convert between fiat and digital assets, based on value, urgency, liquidity conditions, and counterparty location. As more rails become available, this routing layer is where cost, speed, and compliance are won or lost. The industry examples in the report make the point: the SG-FORGE and Swift live trial settled tokenised bonds using both traditional financial infrastructure and regulated digital currencies, and Nexus Global Payments is interlinking domestic instant-payment systems like India’s UPI and Singapore’s FAST. None of these efforts replace the old system. They make the whole system work together.
What this means for businesses evaluating stablecoin payments
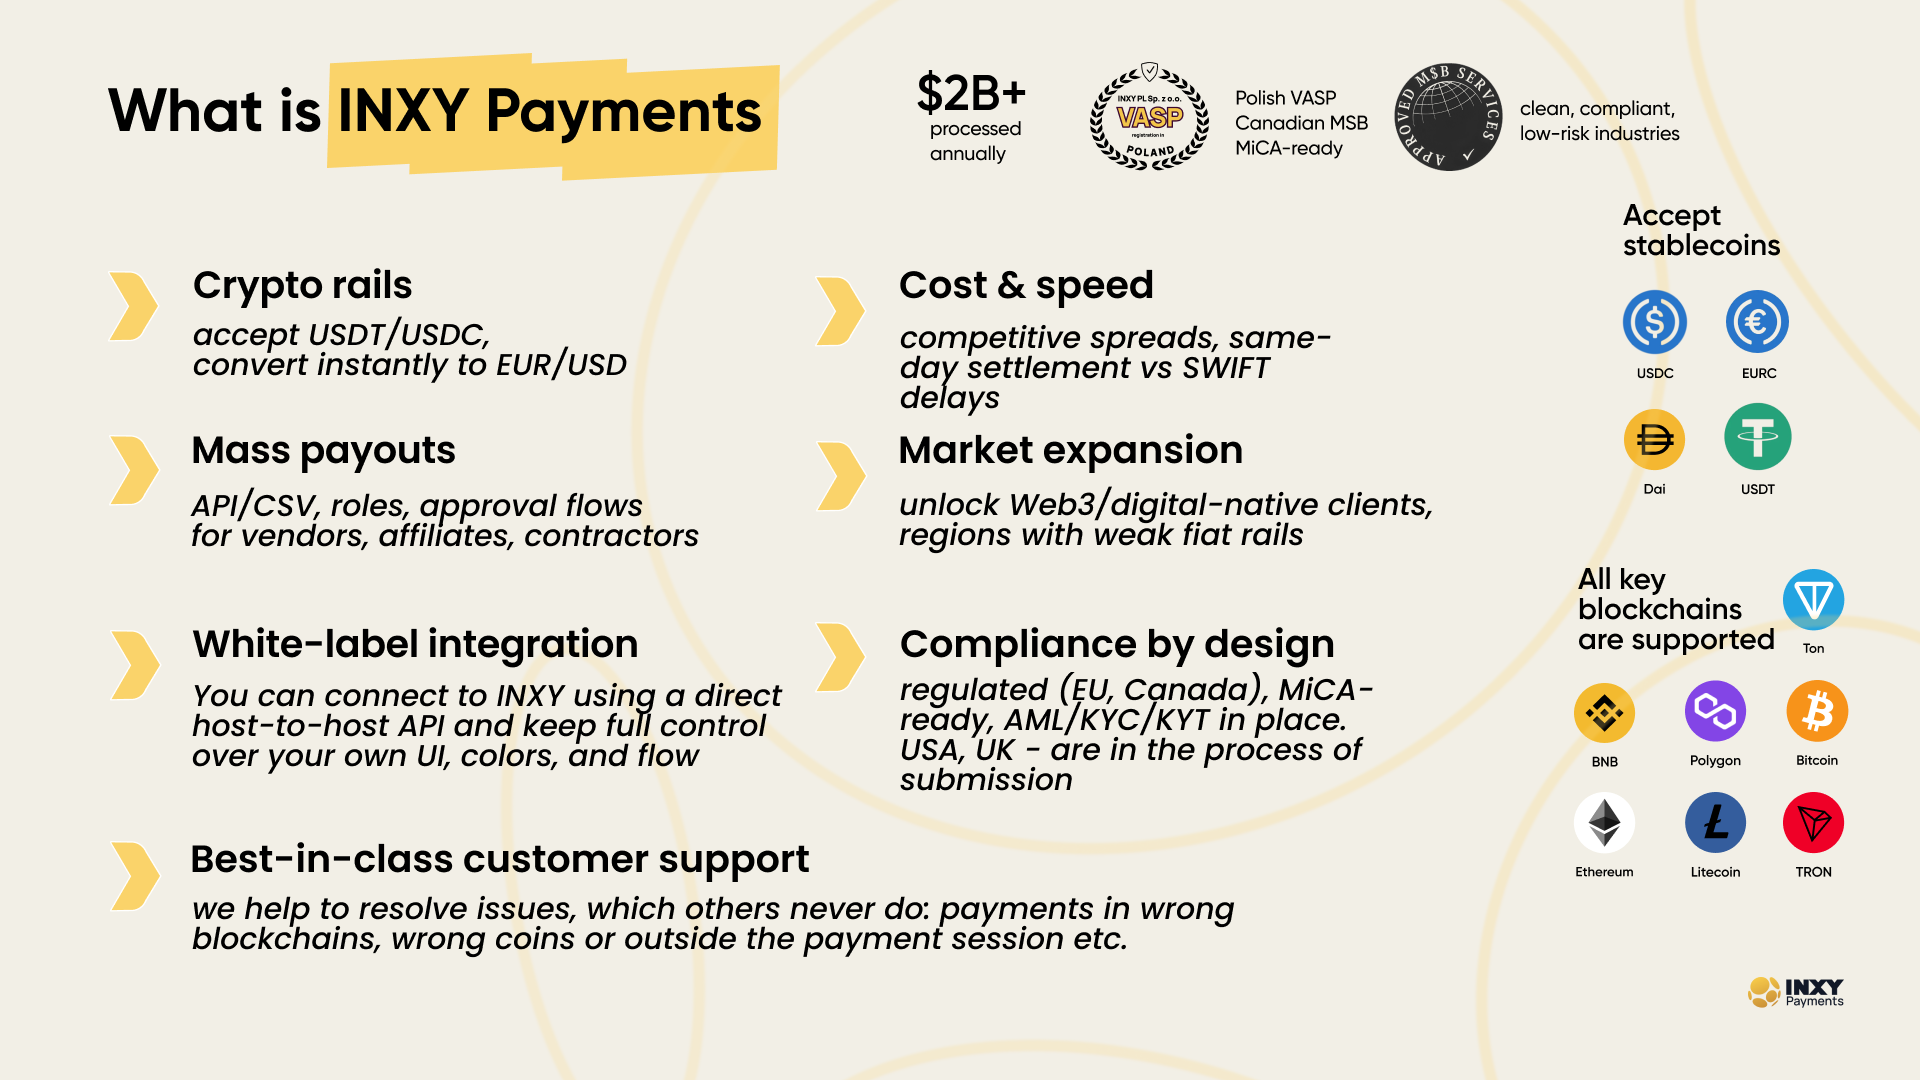
This report describes, almost line for line, the problem we built INXY to solve. INXY provides the infrastructure businesses need to accept stablecoin payments, automate payouts, convert between crypto and fiat, and move money across borders — without building blockchain, liquidity, compliance, and settlement systems from scratch. We operate the layer behind the customer experience, so the complexity stays out of sight.
Concretely, that means:
The merchant does not need to become a crypto company to accept stablecoin payments — acceptance runs through familiar checkout and settlement flows, with conversion to fiat handled behind the scenes.
The fintech does not need to build the entire compliance stack — KYC, AML, Travel Rule, and wallet screening are part of the rail, fast enough to protect conversion rather than throttle it.
The finance team does not need to manage a collection of wallets and chains — payouts, multi-currency treasury, and on/off-ramp conversion are orchestrated through a single integration, priced to keep the full round-trip economics intact.
If you are evaluating stablecoins, we would frame the decision the way the report’s data suggests. Start with the corridors and flows where traditional rails genuinely fail — cross-border supplier payments, international payouts, multi-currency treasury — not with the flows your domestic bank already handles well. Model the full on/off-ramp cost, not just the on-chain fee. And treat compliance and orchestration as core product requirements, not afterthoughts. The businesses that win with stablecoins are not the ones that move tokens; they are the ones that make different payment systems work together.
The winners will be the integrators, not the disruptors
The biggest shift captured in the Global Stablecoins Report 2026 is not from fiat to crypto. It is from crypto product to financial infrastructure — banks, PSPs, and processors integrating stablecoins into systems that already exist. Stablecoins do not need to destroy the old rails to matter. They need to make the whole system move value better.
That is the future we are building for at INXY. Not one payment rail, but many — with an infrastructure layer that decides, routes, converts, and settles across all of them, so businesses get the speed and cost of stablecoins with the trust and control finance teams require. The stablecoin era will not be won by whoever shouts loudest about disruption. It will be won by whoever quietly makes the rails work together.
Navigating Crypto Compliance for Fintechs: How to Offer Stablecoins Safely
As global regulators tighten their grip on digital assets, offering stablecoins safely has become a critical challenge for fintechs. This guide explores how to navigate recent EU restrictions on USDT, why fully collateralized USDC is the gold standard for institutional compliance, and how integrating a multi-asset gateway like INXY protects your platform while providing seamless global transfers.
Imagine launching a killer feature that multiplies your transaction volume overnight, only to have regulators freeze your operations a week later. Welcome to the high-stakes reality of integrating stablecoins into your platform. Right now, digital dollars are powering the global economy, moving billions across borders daily. Your users are demanding it, and the business case for instant settlements is undeniable.
But there is a catch. Financial watchdogs globally are circling. Offering stablecoins is a massive growth lever for ambitious fintechs, but stepping into the crypto arena without an airtight compliance strategy is like walking a tightrope without a net. The ultimate challenge is navigating this regulatory minefield without sacrificing the seamless user experience your customers expect.
The Top Three: USDT, USDC, and DAI
Before diving into regulatory complexities, it is crucial to understand the stablecoin hierarchy and why diversifying your asset offerings is mandatory for compliance.
Tether (USDT): While it currently holds the number one spot for global trading volume, USDT faces severe regulatory headwinds. Notably, the European Union has implemented strict restrictions and effective bans on USDT exchanges under new frameworks, forcing fintechs to rethink relying on a single asset.
USD Coin (USDC): Sitting comfortably as the second most popular stablecoin, USDC is the gold standard for institutional compliance. It is a fully collateralized asset, genuinely backed 1:1 by actual US dollars and short-term assets, providing unparalleled transparency for strict regulators.
DAI: Holding the third position globally, DAI offers a robust, decentralized alternative that maintains its peg through smart contracts and over-collateralization, rounding out the essential stablecoins for any modern financial platform.
Key Regulatory Challenges in the Crypto Landscape
Offering stablecoins is not as simple as plugging into an API. Financial authorities are rapidly tightening their grip to prevent money laundering and systemic economic risks. First, stringent Know Your Customer (KYC) and Anti-Money Laundering (AML) directives require dynamic, ongoing monitoring. Second, the FATF Travel Rule mandates that institutions must securely share originator and beneficiary data for crypto transfers exceeding specific thresholds.
Finally, jurisdictional fragmentation creates a massive headache. The EU’s Markets in Crypto-Assets (MiCA) regulation perfectly exemplifies this, creating strict new rulebooks that directly restrict non-compliant stablecoins like USDT. This makes offering fully backed, transparent assets like USDC an absolute necessity for European operations.
Proven Strategies to Offer Stablecoins Compliantly
To protect your business from crippling fines while maximizing the incredible benefits of digital assets, you must follow these proven operational strategies:
Diversify Your Assets: Do not rely solely on USDT. Offer USDC to satisfy strict regulatory requirements in the EU, and provide DAI for users seeking decentralized options.
Implement Bank-Grade KYC/AML: Utilize automated identity verification systems that check users against global sanctions watchlists in real-time.
Integrate Transaction Monitoring: Deploy sophisticated blockchain analytics tools to trace wallets, ensuring incoming funds are not linked to illicit activities.
Geofence Restricted Jurisdictions: Utilize precise IP tracking to block specific stablecoin features in regions where they are explicitly banned or heavily restricted.
INXY as the Premier Crypto Payment Gateway Partner
Navigating this tangled web of regulations demands the right underlying technological infrastructure. This is where INXY steps in as the premier partner for fintech companies looking to integrate digital assets securely.
As a dedicated cryptocurrency payment gateway, INXY understands the exact pain points fintechs face. Most importantly, INXY natively supports all three of the top stablecoins: USDT, USDC, and DAI. Whether you need a reliable gateway to process fully backed USDC deposits in the heavily regulated EU market or high-speed APIs for global USDT and DAI transfers, INXY provides the robust backbone your application needs to scale while maintaining strict operational compliance.
Conclusion
The future of global payments is strictly digital, and stablecoins are leading the charge. While the fragmented regulatory environment is complex, it should not deter your business from innovating. By prioritizing proactive compliance, diversifying your asset offerings, and choosing the right technological allies, you can confidently offer secure stablecoin services to your users.
Ready to future-proof your financial platform? Discover how we can help you scale your operations compliantly by visiting https://www.inxy.io/fintech today.