In May 2010, a hungry programmer made financial history by trading 10,000 Bitcoins for two Papa John’s pizzas. At the time, there were no global marketplaces, no flashing price tickers, and absolutely no liquidity—just a simple forum post and a massive leap of faith. Today, the landscape has transformed beyond recognition. Those same pizzas would now be worth hundreds of millions of dollars, and the digital asset market has evolved into a trillion-dollar ecosystem.
At the beating heart of this financial revolution is the cryptocurrency exchange. Whether you are a retail investor looking to buy your first fraction of a Bitcoin, a professional trader executing high-frequency strategies, or a modern business owner trying to tap into a global, borderless customer base, understanding what a crypto exchange is and how it functions is the crucial first step to entering the digital economy.
The Engine of the Digital Economy
On any given day, top cryptocurrency exchanges process combined trading volumes exceeding $100 billion. They are the bustling, hyper-active metropolises of the digital age.
At its core, a cryptocurrency exchange is a highly secure digital marketplace that allows users to buy, sell, or trade cryptocurrencies for other assets. These assets can include conventional fiat money (like US Dollars or Euros) or other digital tokens. Exchanges act as the vital intermediary, providing the infrastructure, security, and liquidity necessary for the global crypto market to operate 24/7 without interruption.
Under the Hood: How an Exchange Functions
How does a platform handle millions of transactions per second without collapsing? Buying crypto might look like a simple tap on a smartphone screen, but the magic happens under the hood through several interconnected, highly advanced systems:
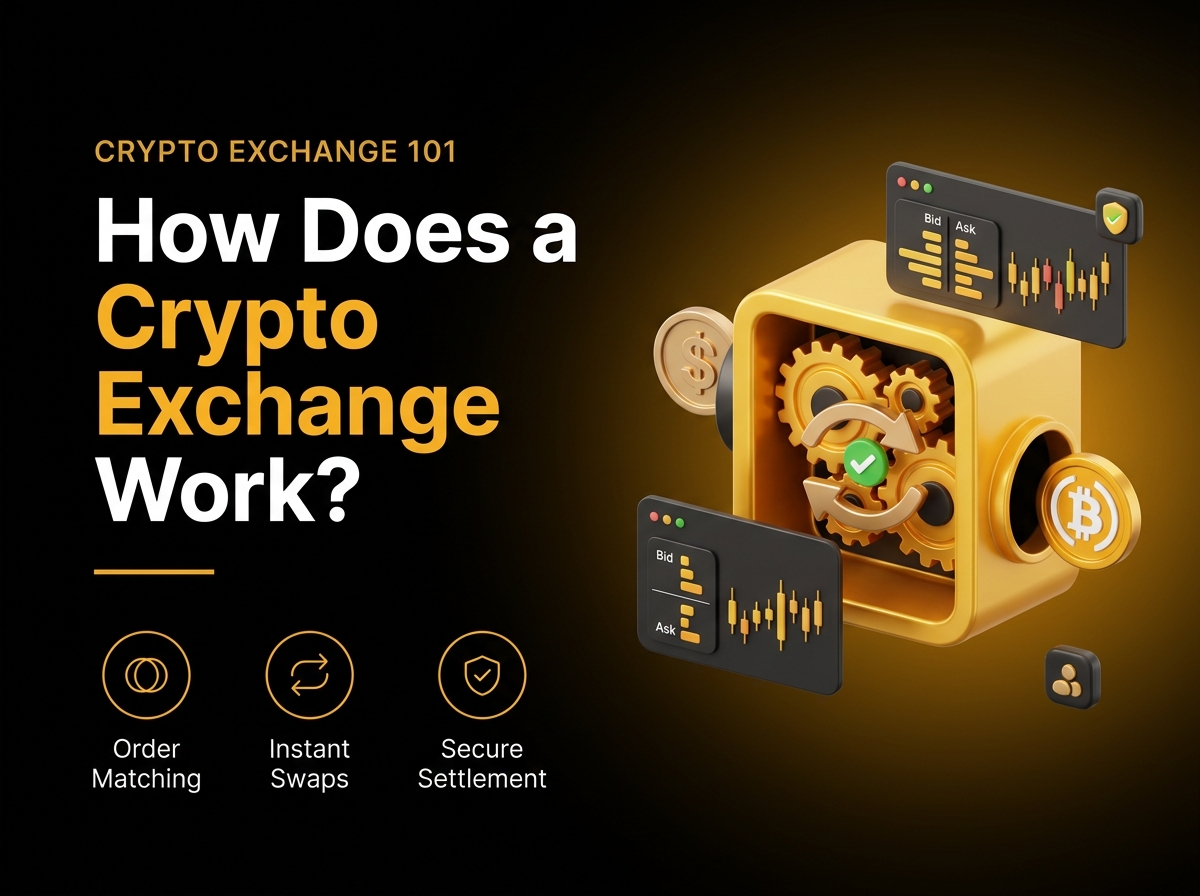
The Matching Engine: This is the absolute brain of the operation. The matching engine is an advanced software algorithm that continuously monitors and pairs buy and sell orders. When a buyer's bid meets a seller's asking price, the engine executes the trade in milliseconds.
Order Books and Market Depth: An order book is an electronic, real-time ledger of all the outstanding buy and sell orders for a specific trading pair (e.g., BTC/USD). It visualizes the current market depth, allowing traders to gauge ongoing supply, demand, and potential price movements.
Liquidity Pools: Liquidity dictates how easily an asset can be converted into cash without drastically affecting its market price. High liquidity means there are plenty of active buyers and sellers, resulting in lightning-fast transaction times and highly stable pricing.
Integrated Wallets: To facilitate instant trading, exchanges provide users with proprietary digital wallets. This allows traders to temporarily store their funds directly within the platform’s ecosystem for rapid deployment.
Centralized vs. Decentralized Exchanges (CEX vs. DEX)
As the industry has matured, two distinct philosophies have emerged regarding how these marketplaces should operate:
Centralized Exchanges (CEX): Platforms like Binance or Coinbase are owned and operated by a central corporate entity. They act as a trusted third party, offering deep institutional liquidity, fiat-to-crypto on-ramps, and user-friendly interfaces. The trade-off is that you must trust the corporation with the custody of your funds.
Decentralized Exchanges (DEX): Platforms like Uniswap operate entirely on blockchain technology using automated smart contracts. There is no central authority. Users retain 100% control of their funds by connecting their own private wallets. While they offer superior privacy and eliminate centralized points of failure, they can be intimidating for beginners.
The Commercial Shift: Why Businesses Need More Than an Exchange
This is where the story shifts from pure speculation to real-world commercial utility. With over 420 million active cryptocurrency users worldwide, digital assets are no longer just a niche internet hobby. They represent a massive, highly lucrative, and untapped consumer base. Recent industry surveys reveal a staggering metric: merchants who begin accepting crypto payments see an average ROI of up to 327%, with nearly 40% of their crypto-paying customers being entirely new to the brand.
However, here is the critical catch for corporate adoption. While exchanges are engineering marvels for individual traders, they are fundamentally not optimized for commercial B2B operations. If an online retailer or a global enterprise wants to accept crypto, directing clients to a standard exchange order book is a logistical nightmare. It leads to severe accounting errors, subjects the company to unpredictable withdrawal fees, and exposes business revenue to extreme, day-to-day price volatility.
To truly capitalize on the crypto economy, modern businesses require specialized, enterprise-grade infrastructure. The optimal solution is an advanced crypto payment gateway like inxy.io.
Instead of forcing merchants to navigate the speculative chaos of a trading platform, inxy.io is built specifically for seamless corporate integration. As a premier crypto payment gateway, it bridges the gap between digital assets and traditional commerce by offering:
An Automated Checkout Experience: It seamlessly integrates into a company's existing website or application, allowing global customers to pay in their preferred cryptocurrency in just a few clicks.
Instant Volatility Shielding: A premium gateway like inxy.io can instantly convert volatile crypto payments into stablecoins or fiat currency at the exact moment of the transaction, protecting the merchant's bottom line from sudden market crashes.
Cost-Efficiency and Compliance: By completely avoiding the heavy withdrawal constraints and hidden spread fees of retail exchanges, inxy.io provides transparent pricing, clear accounting, and professional invoicing tailored for corporate legal compliance.
Conclusion
Understanding the mechanics of a crypto exchange is essential for anyone navigating the modern financial landscape. They provide the necessary liquidity and global accessibility that keep the blockchain economy thriving. However, as digital assets move from the trading floor to the retail checkout, the tools we use must also evolve. While speculators will always rely on CEXs and DEXs, forward-thinking businesses must look toward specialized solutions. By leveraging a dedicated crypto payment gateway like inxy.io, companies can safely, efficiently, and profitably open their doors to the future of global commerce.
Cross-Border B2B Payments With Stablecoins: The 2026 Guide to Faster, Cheaper Settlement
This guide explains how cross-border stablecoin payments actually work, how they compare to SWIFT, where they make the most sense, and what it takes to start accepting them.
For most businesses, sending money across borders still feels like it did a decade ago: slow, opaque, and expensive. Cross-border crypto payments built on stablecoins are changing that. Instead of routing an international crypto payment through a chain of correspondent banks, a stablecoin transfer settles directly on a blockchain in seconds, for a fraction of the cost. In 2026 this is no longer a fringe experiment — it is one of the fastest-growing segments in business payments, and the data behind it is hard to ignore.
This guide explains how cross-border stablecoin payments actually work, how they compare to SWIFT, where they make the most sense, and what it takes to start accepting them.
Why cross-border crypto payments are replacing the old rails
The traditional system was never designed for the speed of modern commerce. It was designed for banks talking to banks.
The hidden cost of SWIFT and correspondent banking
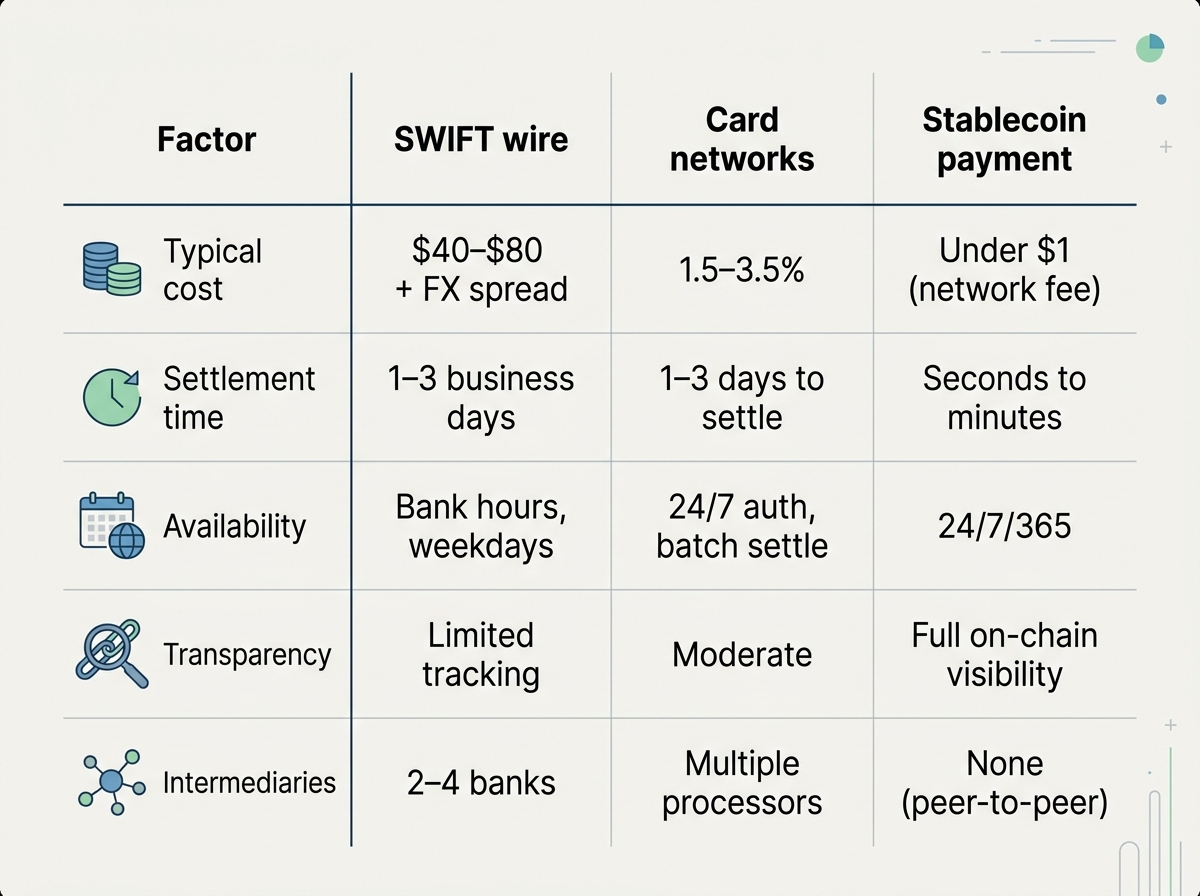
A typical international wire passes through two to four intermediary banks before it reaches the recipient. Each one takes a cut and adds a delay. The result is well known to any finance team: wire fees of roughly $40–$80 per transaction, settlement times of one to three business days (longer across exotic corridors), and almost no visibility into where the money is at any given moment. Add unfavorable FX spreads and the all-in cost of moving money internationally can quietly erode margins on every cross-border deal.
For a company paying dozens or hundreds of overseas suppliers, contractors, or partners each month, that friction compounds fast.
What changed in 2026
Stablecoins — blockchain tokens pegged 1:1 to a fiat currency such as the US dollar — turned out to be an almost perfect fit for this problem. They hold a stable value, move on open networks 24/7, and settle without a banking intermediary.
Adoption has gone vertical. Business-to-business stablecoin payment volume grew roughly 733% year over year heading into 2026, and total stablecoin transaction volume reached about $33 trillion in 2025. Juniper Research projects that cross-border B2B stablecoin payments will hit $5 trillion by 2035, up from an estimated $13.4 billion today, with the large majority of that future value coming specifically from cross-border business use. In short: the rail is being built right now, and businesses that learn it early gain a cost advantage.
How stablecoin cross-border payments actually work
The mechanics are simpler than the technology sounds. Every cross-border stablecoin payment follows the same three-stage path.
On-ramp, settlement, off-ramp
On-ramp. The sender converts local fiat (USD, EUR, etc.) into a stablecoin such as USDC or USDT, either from existing treasury or through a payment provider.
Settlement. The stablecoin moves across a blockchain network directly to the recipient's wallet. This is the step that replaces the entire correspondent-banking chain.
Off-ramp. The recipient either holds the stablecoin or converts it back to their local currency and withdraws to a bank account.
A provider like INXY handles the on-ramp, settlement, and off-ramp as a single flow, so the business never has to touch a crypto exchange directly.
Stablecoins and networks used
Most B2B volume runs on US-dollar stablecoins — USDC, USDT, and increasingly PYUSD — because they remove currency-volatility risk while keeping the speed of crypto. The network matters too, because it determines how fast and how cheaply a payment finalizes:
Solana — settlement finality in under half a second, with sub-cent fees.
Tron — finality in roughly one to two seconds; widely used for USDT.
Ethereum Layer-2s — low fees with fast confirmation, anchored to Ethereum security.
The practical takeaway: a payment that took three days on SWIFT can finalize in seconds on the right chain.
Stablecoins vs SWIFT: cost, speed, and transparency
The clearest way to understand the shift is a side-by-side comparison of low fee crypto payments against the legacy rails.
The economics are most dramatic at scale. Dropping from $40+ per wire to under $1 per transfer changes what is financially viable — micro-payments, frequent payouts, and thin-margin corridors that never made sense on SWIFT suddenly do.
Top use cases for global crypto transactions
Stablecoins are not a fit for every payment, but for global crypto transactions between businesses they solve real, recurring pain.
Supplier and vendor payments. Pay overseas manufacturers and service providers same-day instead of waiting for a wire to clear, improving supplier relationships and unlocking faster terms.
Contractor and team payouts. Pay international contractors and remote staff in stablecoins without losing 5–10% to fees and FX on every transfer. (INXY also covers dedicated crypto payroll.)
Marketplace and platform payouts. Distribute earnings to sellers, affiliates, or creators across many countries in a single batch, at predictable cost.
Treasury and intercompany transfers. Move funds between entities and regions instantly, holding value in a dollar-pegged asset rather than parking it in slow, fee-heavy banking channels.
These are exactly the corridors where the old system performs worst — many small-to-mid payments, many destinations, tight margins.
Are low fee crypto payments compliant? GENIUS Act and MiCA
A fair question from any finance or legal team: is this allowed? In 2026, the answer is increasingly yes — and the regulatory ground is firmer than it has ever been.
In the United States, the GENIUS Act established the first federal framework for payment stablecoins, requiring issuers to be licensed, to hold 1:1 reserves in high-quality liquid assets, and to honor redemption on demand. In the European Union, MiCA (Markets in Crypto-Assets) provides a parallel framework. Together they have moved stablecoins from a regulatory gray zone into supervised, standardized instruments — which is a large part of why institutional adoption accelerated.
What a regulated provider handles for you
Compliance does not have to live on your team. A regulated payment provider performs KYB (Know Your Business) onboarding, screens transactions against AML requirements, and maintains the audit trail you need for reporting. The business gets the speed and cost benefits of stablecoins while the provider absorbs the regulatory heavy lifting.
How to start accepting cross-border crypto payments
Getting started is closer to onboarding a payment processor than to learning crypto.
Choose a regulated provider that supports on-ramp, settlement, and off-ramp in your corridors — not a raw exchange.
Complete KYB onboarding and connect your bank account or treasury.
Pick your stablecoins and networks (USDC/USDT on a fast, low-fee chain) and set how recipients receive funds — held as stablecoin or auto-converted to local fiat.
Integrate and pay. Use the dashboard for one-off and batch payments, or the API to automate payouts inside your existing systems.
Once live, a cross-border payment that used to mean a wire form and a three-day wait becomes a few clicks and a few seconds.
The bottom line
Cross-border B2B payments are being rebuilt on stablecoin rails, and the trend lines — 733% volume growth, a projected $5 trillion market, and clear regulation under the GENIUS Act and MiCA — point in one direction. For businesses that move money internationally, stablecoins offer dramatically lower fees, near-instant settlement, and full transparency, without the volatility of traditional crypto. The companies adopting it now are the ones that will spend the next decade paying cents where their competitors pay tens of dollars.
Are stablecoin payments legal for business? Yes. In 2026, US-dollar stablecoins are regulated under the GENIUS Act in the United States and MiCA in the EU. Using a licensed provider keeps your KYB and AML obligations covered.
How fast is settlement? Depending on the network, a stablecoin payment finalizes anywhere from under a second (Solana) to a couple of minutes — versus one to three business days for a SWIFT wire.
What fees apply? The main cost is a small blockchain network fee, often under $1, plus any provider conversion fee on the on-ramp or off-ramp. This compares to $40–$80 per traditional international wire.
USDC or USDT for cross-border payments? Both are widely accepted dollar-pegged stablecoins. USDC is often preferred for its regulatory transparency; USDT has deeper liquidity in some corridors. A good provider supports both so you can match the recipient's preference.
How to Integrate Crypto Payments into Your Business: A Practical Guide
Adding a crypto payment gateway to your business can open new doors. It lets you accept crypto payments from customers worldwide, bringing faster transactions, lower fees, and no chargebacks. But it’s not as simple as flipping a switch. To truly make crypto work for your business, there’s a list of things you need to get right.
Adding a crypto payment gateway to your business can open new doors. It lets you accept crypto payments from customers worldwide, bringing faster transactions, lower fees, and no chargebacks. But it’s not as simple as flipping a switch. To truly make crypto work for your business, there’s a list of things you need to get right.
Set Up a Digital Wallet
A wallet is where digital assets are stored. For daily operations, software wallets can be enough. But for larger amounts, businesses usually choose hardware wallets for added security.
Choose and Integrate a Payment Solution
You'll need a payment gateway that supports digital currencies. This might be a plugin for your e-commerce platform or a custom API integration. The goal is to make payment easy for customers and seamless for your team.
Handle Pricing and Exchange Rates
Decide how to display prices-directly in digital currency or by converting from your local currency at the moment of purchase. Make sure exchange rates are transparent for your customers.
Manage Volatility
Digital currencies are known for price swings. Have a strategy for dealing with this, such as converting to stablecoins or fiat currency immediately after payment.
Monitor Transaction Fees
Network fees can change depending on demand. Regularly review these costs to ensure they remain acceptable for your business.
Stay Compliant
Digital payments are subject to different rules in different regions. Make sure you understand your obligations around KYC (Know Your Customer), AML (Anti-Money Laundering), and other regulatory requirements.
Educate Your Team
Everyone involved should know how the system works-especially your customer service team, who may need to help customers with payment questions.
Communicate with Customers
Let your customers know that you now accept digital payments. Add clear messaging across your website, marketing materials, and checkout flow.
Test Before Launching
Run test payments to ensure the process is smooth from start to finish. This helps catch any issues before customers experience them.
Strengthen Security
Security is a top priority. Use strong authentication, multi-signature wallets, and cold storage for long-term holdings. Keep your security protocols updated.
Set Up Accounting Processes
Track every transaction carefully. Many tax authorities require detailed reporting of digital currency transactions, and having a solid system in place is essential.
Prepare Customer Support
Expect questions and occasional payment issues. Make it easy for customers to contact you and resolve problems quickly.
Stay Informed
The digital payments landscape evolves rapidly. Keep an eye on regulatory changes, new technologies, and market trends to stay ahead.
Get Tax Advice
Digital currency can create tax liabilities. Consult a tax advisor who understands how digital payments are handled in your jurisdiction.
Review and Optimize
Regularly review how digital payments are working for your business. Gather customer feedback and monitor performance to make improvements as needed.
How INXY Payments Supports These Steps
At INXY Payments, we've built our platform to address all these challenges in one place. Our service is designed for businesses that want to add digital currency payments with minimal friction and maximum compliance. Here's how we help:
Auto-conversion: Incoming payments can be automatically converted to stablecoins or fiat currency to minimize volatility.
Full Compliance: Our platform is fully compliant with MiCA and other EU regulations, with built-in tools for KYC and AML checks.
Seamless Integration: Whether you use the API or our dashboard, setup is simple and fast.
No Wallet Management: You don't need to create and maintain wallets on different blockchains or hold extra coins to pay network fees-we handle that for you.
Custom Reports: We provide detailed, customized reports to simplify your accounting and tax filing.
Security First: Advanced security features protect your funds at every step.
Global Reach: We support payments worldwide and work across multiple industries.
Expert Support: Our team offers personalized onboarding and ongoing assistance, including tax consultations and compliance help.
Always Up-to-Date: We stay on top of blockchain updates and new infrastructure developments, so you don't have to worry about keeping up with tech changes.
Whether you want to accept bitcoin payments, send mass payouts in crypto, or add a seamless crypto billing option to your service, we've got you covered.
This guide explains how to buy USDT, USDC, and DAI using the five most popular methods, including exchanges, bank transfers, cards, P2P platforms, crypto ATMs, and mobile apps. It breaks down the benefits of each option, helping readers choose the fastest and most cost-effective way to purchase stablecoins. The article also highlights key fees to consider and common mistakes to avoid. Strong emphasis is placed on security best practices to protect funds and personal data. By the end, readers know exactly how to buy stablecoins safely and confidently in 2026.
Stablecoins are a type of digital currency designed to keep their value stable. Unlike other cryptocurrencies, which can fluctuate wildly, stablecoins aim to maintain a fixed value. This stability makes them a popular choice for people who want to use digital money without worrying about price changes.
Many stablecoins are linked to traditional money like the US dollar. This link, often called pegging, helps keep their price steady. For example, if you buy one USDT, USDC, or DAI, it is usually worth about one US dollar. This makes it easy for people to understand and trust their value.
Stablecoins are used for various purposes. People can use them to send money across borders quickly and cheaply. They are also popular in trading, allowing users to move money between different cryptocurrencies without converting it back to traditional money. This flexibility makes stablecoins a key part of the digital currency world.
Why Buy USDT, USDC & DAI?
People often ask why they should invest in stablecoins like USDT, USDC, and DAI. These digital coins are tied to real-world currencies, like the US dollar. This makes them less risky than other cryptocurrencies that can jump up and down in value. Let's say you want to save money for a big purchase next year. Storing your money in stablecoins could help keep it safe from market swings.
Using stablecoins can also make transactions faster and cheaper. Imagine sending money to a friend in another country. Traditional banks can take days and charge high fees. But with USDT or USDC, the transfer is usually done in minutes, with lower costs. This speed can be a game-changer for both personal and business transactions.
DAI offers an interesting twist. It's a stablecoin managed by smart contracts on the blockchain, not by a central bank. This decentralization offers more control and transparency. If you value privacy and autonomy, DAI could be your go-to choice.
Choosing the Right Exchange
Picking the right exchange to buy USDT, USDC, and DAI can feel a bit like choosing a new car. You want reliability, trustworthiness, and something that fits your needs. Start by looking at the reputation of the exchange. Is it well-known and respected in the crypto community? Check user reviews and any news about security breaches.
Fees are another important factor. Some exchanges charge a percentage of your transaction, while others have flat fees. You want to find a balance between cost and convenience. Ease of use matters too. If the platform is too complex, it could lead to mistakes. Look for a user-friendly interface.
Consider the payment methods available. Can you use your credit card, bank transfer, or PayPal? More options mean more flexibility. Lastly, check if the exchange supports the stablecoins you want to buy. Not all exchanges offer USDT, USDC, and DAI. By taking these steps, you can choose an exchange that works best for you.
Using a Bank Transfer
Buying stablecoins like USDT, USDC, or DAI through a bank transfer can be a straightforward method. First, select a cryptocurrency exchange that allows bank transfers. Popular exchanges often have this option. Start by linking your bank account to the exchange. You might need to verify your identity, so have your ID ready. Once your account is linked, you'll transfer funds from your bank to the exchange. It may take a few days for the transfer to complete, depending on your bank's processing speed.
When your funds arrive in the exchange account, choose the stablecoin you want to buy. Then, enter the amount you wish to purchase and confirm the transaction. Bank transfers usually have lower fees compared to credit cards. This makes them a cost-effective choice. However, if you're in a rush, the slower processing time might not be ideal. Always check if there are any fees involved with your bank. Each bank's policies can vary, and it's good to know what to expect.
Credit and Debit Card Purchases
Buying stablecoins like USDT, USDC, and DAI with credit or debit cards is a popular choice. Why? It's quick and straightforward, just like buying your favorite online products. Many crypto exchanges allow you to link your card directly to their platform. Once linked, you can purchase stablecoins in just a few clicks.
It's important to know that some exchanges may charge a fee for card transactions. Fees can vary, so it's smart to compare before making a purchase. Also, keep an eye on your bank's foreign transaction fees, as these can add to your costs.
When using this method, security is key. Ensure your chosen exchange uses strong security measures. This helps protect your card and personal information. Always use trusted and verified platforms to avoid scams. Buying stablecoins with a card is easy, but it's wise to stay informed about costs and safety.
Peer-to-Peer (P2P) Platforms
Buying stablecoins like USDT, USDC, and DAI through P2P platforms can be a straightforward process. These platforms let you trade directly with another person, bypassing any middlemen. You can often find better deals because you're negotiating directly with sellers.
To get started, you'll need to register on a P2P platform. Most platforms require identity verification, but this is usually quick. Once registered, browse through the listings to find someone selling the stablecoin you want. Check their reputation score to ensure they're trustworthy.
After choosing a seller, you can initiate a trade. The platform will hold the stablecoin in escrow until the payment is complete. Payment methods vary, including bank transfers and digital wallets. Once the seller confirms the receipt of payment, the platform releases the stablecoin to you. This process makes P2P platforms a flexible option for buying stablecoins.
Using Crypto ATMs
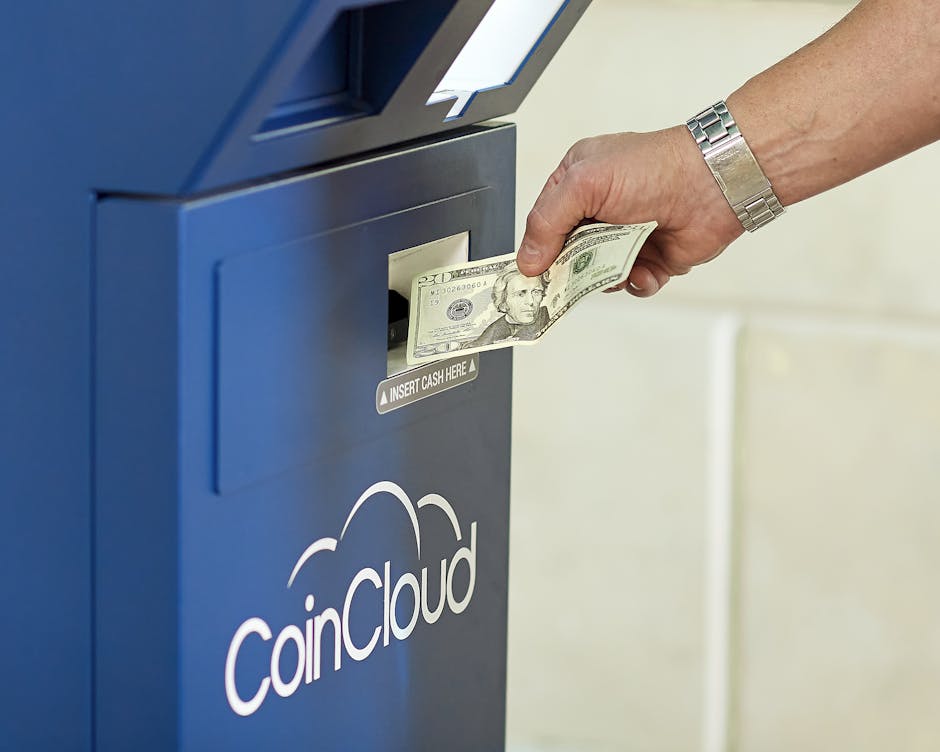
Crypto ATMs have become a popular choice for people looking to buy stablecoins like USDT, USDC, and DAI. These machines offer a straightforward way to purchase digital currencies using cash or a credit card. You can find them in various locations, such as malls, convenience stores, and even airports.
To use a crypto ATM, you first need to find one near you. Websites and apps can help locate these machines. Once you reach the ATM, you choose the type of stablecoin you want to buy. The screen will guide you through the process, ensuring it's easy to follow.
Most crypto ATMs require you to scan a QR code from your digital wallet. This step links the purchased stablecoins directly to your wallet. If you don't have a digital wallet, some ATMs offer to create one for you on the spot. This feature is handy for beginners who might not have set up a wallet yet.
After choosing the stablecoin and scanning your wallet's QR code, you insert cash or use your credit card to make the purchase. The machine will show you the current rate and any fees involved. It's vital to check these rates and fees to ensure you're getting a good deal.
Crypto ATMs typically charge higher fees compared to online exchanges. This is due to the convenience they offer. But for those who prefer a quick, in-person transaction, the extra cost might be worth it. Plus, the process is often faster than waiting for bank transfers when buying online.
Overall, crypto ATMs provide a user-friendly option for buying stablecoins. With clear instructions and immediate transactions, they cater to both beginners and experienced users. As more ATMs pop up globally, they continue to make crypto transactions accessible to everyone.
Mobile Apps for Quick Purchases
Buying stablecoins like USDT, USDC, and DAI using mobile apps is a breeze in 2026. With just a tap, you can access digital currencies right from your smartphone. Let's explore how mobile apps have revolutionized the way we purchase stablecoins.
First off, mobile apps offer convenience. You can buy stablecoins anytime, anywhere. Whether you're at home, on the go, or even on vacation, your smartphone becomes a powerful tool for managing your digital assets. This flexibility is a game-changer for many people.
Now, let's talk about security. Mobile apps have stepped up their game with robust security features. Many apps use two-factor authentication, biometric logins, and encryption to protect your transactions. This ensures that your data and funds are safe from unauthorized access.
When it comes to speed, mobile apps are hard to beat. Transactions are often completed in seconds. This is especially useful when you need to buy stablecoins quickly due to market changes. No more waiting around for lengthy confirmations.
Mobile apps also offer user-friendly interfaces. They are designed to be intuitive, so even beginners can navigate through the app without hassle. Most apps provide step-by-step guides or tutorials to help you through the buying process.
Payment options are another highlight. Mobile apps typically support various payment methods like credit cards, bank transfers, and sometimes even PayPal. This variety makes it easier to choose a method that suits you best.
Customer support is also at your fingertips. Many mobile apps provide in-app chat support or detailed FAQs to assist users. If you face any issues, help is just a click away.
Let's not forget about notifications. Mobile apps can send you instant alerts about price changes or transaction statuses. This keeps you updated on your investments and helps you make timely decisions.
In 2026, buying stablecoins like USDT, USDC, and DAI through mobile apps is not just a trend, it's a preferred choice for many. The convenience, security, and speed make it a favored method for both new and seasoned users. So, if you haven't tried it yet, exploring mobile apps for stablecoin purchases might be a smart move.
Fees to Consider
When buying stablecoins like USDT, USDC, and DAI, fees can significantly impact your purchasing decision. Understanding these fees can help you find the best deals and avoid unnecessary costs. Let's break down the most common fees you may encounter.
Firstly, there's the transaction fee. This fee is charged by the platform where you buy your stablecoins. It can be a flat fee or a percentage of your purchase amount. For example, if a platform charges a 1% transaction fee and you're buying $100 worth of USDT, you'll pay an additional $1.
Another type of fee is the withdrawal fee. Once you've bought stablecoins, you might want to transfer them to a digital wallet. Some platforms charge a fee for this transfer. It's essential to check if the fee is fixed or varies depending on the amount you withdraw. A fixed fee can be more cost-effective if you're transferring a large amount.
Exchange rate fees can also play a role. When you use a credit card or bank transfer in a different currency, you might face a currency conversion fee. This fee is often hidden in the exchange rate offered by the platform. Comparing the exchange rate with the market rate can help you spot any discrepancies.
Some platforms offer discounts or even waive fees for using their native tokens or certain payment methods. For instance, if a platform has its token and you use it to pay for fees, you might get a discount. It's worth checking if such options are available to reduce your costs.
Lastly, be aware of inactivity fees. If you have an account on a platform but don't use it for a while, some platforms charge an inactivity fee. This is less common but can catch you off guard if you plan to hold your stablecoins for a long time without frequent activity.
To sum up, different platforms have different fee structures. It's crucial to read the fee schedules of various exchanges and platforms before deciding where to buy your USDT, USDC, or DAI. This knowledge will help you make informed decisions and keep more of your money in your pocket.
Security Tips When Buying Stablecoins
When you're diving into the world of stablecoins like USDT, USDC, and DAI, security should be at the top of your list. Let's break down some simple yet effective tips to keep your investments safe.
First things first, always use a secure and reputable exchange for your transactions. Popular exchanges often have stronger security measures in place, reducing the risk of hacks. Do a little research to find out which platforms have the best track record for security.
Another important step is to enable two-factor authentication (2FA) on your accounts. This adds an extra layer of protection by requiring not just a password, but a second piece of information that only you have access to. It's like having a double lock on your door.
Keep your private keys safe and never share them with anyone. Think of private keys as the password to your wallet. If someone else gets hold of them, they can access your funds. Consider using a hardware wallet to store your cryptocurrencies offline, away from online threats.
Phishing scams are another thing to watch out for. These are fake websites or emails that try to steal your information by pretending to be legitimate. Always double-check the URLs of the sites you visit and be cautious of links in emails.
Regularly update your software and wallets to the latest versions. Updates often contain security enhancements that protect against new threats. It's like keeping your antivirus software up-to-date to fend off viruses.
Lastly, be mindful of the information you share online, especially on social media. Publicly revealing details about your cryptocurrency holdings can make you a target for cybercriminals.
By following these tips, you can help secure your transactions and enjoy a safer experience in the world of stablecoins.
Conclusion: Your Path to Stablecoins
Navigating the world of stablecoins like USDT, USDC, and DAI can seem daunting at first. These digital currencies offer a stable alternative to more volatile cryptocurrencies. They are pegged to the value of traditional currencies, making them less subject to wild price swings. Let's explore how you can confidently step into the stablecoin space.
Imagine you're standing at the crossroads of traditional finance and the digital world. Stablecoins are like a bridge between these two realms. They combine the stability of fiat currencies with the advantages of blockchain technology. This makes them an attractive option for both seasoned investors and newcomers alike.
When you're considering buying stablecoins, think about why you want them. Are you looking to invest, send money overseas, or simply diversify your holdings? Knowing your purpose can help you choose the right stablecoin. For instance, USDT is widely used and easily accessible on many exchanges. USDC, on the other hand, is known for its transparency and regulatory compliance. DAI offers a decentralized option, which can appeal to those wary of centralized control.
Once you've decided on the stablecoin, it's time to find the best way to buy it. Consider factors like transaction fees, speed, and ease of use. You might choose a centralized exchange for its convenience or a decentralized one for its privacy. Each has its pros and cons, so weigh them carefully.
Before making a purchase, ensure your digital wallet is ready. This wallet will store your stablecoins securely. There are different types of wallets, such as hardware, software, and mobile wallets. Choose one that suits your needs and provides robust security.
Security is crucial when dealing with digital assets. Always use strong passwords and enable two-factor authentication. Be wary of phishing scams and other online threats. Keeping your assets safe is just as important as buying them.
As you venture into stablecoins, stay informed about market trends and regulatory changes. The world of cryptocurrency is ever-evolving, and being updated will help you make better decisions. Engage with online communities, read news articles, and follow industry experts to deepen your understanding.
Your journey into stablecoins can be rewarding. With careful planning and informed choices, you can make stablecoins work for you. Whether it's for investment, transactions, or hedging against volatility, stablecoins offer a world of opportunities. Embrace this digital frontier with confidence, and you'll find a stable path forward.
FAQ
What are stablecoins and why are USDT, USDC, and DAI popular?
Stablecoins are cryptocurrencies designed to minimize price volatility by being pegged to a reserve of assets, like fiat currency. USDT, USDC, and DAI are popular because they offer stability, making them ideal for trading, hedging, and transfers within the crypto ecosystem.
Why should I consider buying USDT, USDC, or DAI?
These stablecoins are beneficial for preserving value, facilitating seamless crypto transactions, and providing a reliable medium for trading and investment strategies without the volatility of other cryptocurrencies.
How do I choose the right exchange for buying stablecoins?
Look for exchanges with competitive rates, low fees, strong security measures, good user reviews, and those that offer the trading pairs you need. Consider factors like liquidity, user interface, and customer support as well.
Is it cost-effective to buy stablecoins using a bank transfer?
Yes, bank transfers often have lower fees compared to credit/debit card purchases. However, it's important to check the exchange's fee schedule and processing times to minimize costs and delays.
What should I know about buying stablecoins with a credit or debit card?
Purchasing with a credit or debit card is convenient but usually comes with higher fees and lower purchase limits. Ensure you're aware of the costs and verify the legitimacy and security of the platform you're using.
How can I use Peer-to-Peer (P2P) platforms to buy stablecoins?
P2P platforms allow you to buy stablecoins directly from other users, often at competitive rates. Ensure you use reputable platforms, check user ratings, and follow security measures to protect your transactions.
Are there any security tips I should follow when buying stablecoins?
Always enable two-factor authentication, use secure wallets, verify the legitimacy of exchanges or sellers, and avoid sharing personal information. Regularly monitor your accounts and transactions for any suspicious activity.