Most companies that look for a Payoneer alternative are not annoyed about their own fee. They are annoyed about their contractors’ fees.
A contractor in Manila invoices 3,000 USD. You pay it in full. She withdraws to her peso account and loses up to 2%, or up to 60 USD, before her bank takes its own cut. Every month. You never see it in your P&L. In month six it comes back to you as a rate-increase request.
This article compares five payout options on published fees, batch size and who pays for conversion. It also names the cases where Payoneer is still the right answer.
All competitor figures below come from each vendor’s own pricing, product or support pages, read between 26 September and 6 October 2026. Prices change often. Re-check every number before it goes into a business case. “Not published” means the vendor does not disclose the figure, not that it is zero.
Diagnose the complaint before you shortlist anything
“Payoneer alternative” is one search for three different problems. Each one has a different answer.
The payee-side deduction. Your payees convert to local currency and lose a percentage you never see. Payoneer’s published fees include up to 2% to withdraw to a local bank account in a different currency, and a fixed 1.50 EUR or 1.50 GBP for a same-currency withdrawal (payoneer.com, read 26 September 2026). The payee carries that cost, and their bank may add its own.
The account, not the price. Ad networks, affiliate platforms and some marketplace models get offboarded, not overcharged. That is a risk decision about the provider’s portfolio. No pricing page will warn you it is coming.
The batch shape. Payoneer’s batch payments product takes up to 1,000 transfers to external accounts, or up to 500 Payoneer-to-Payoneer payments, per file. Recipients do not need a Payoneer account. Coverage is 190+ countries and territories and 70+ currencies. Payoneer-to-Payoneer transfers typically clear within 7 seconds. Batch fees are not published (payoneer.com/batch-payments, read 26 September 2026).
If your complaint is the third one, a cheaper vendor with the same setup will not fix it. Large, regular payout runs need an API, clear approvals and one clean reconciliation file. That is an operations problem dressed up as a pricing problem.
The comparison table
Figures as published by each vendor, read between 26 September and 6 October 2026.
| Option | Architecture | Published headline cost | Batch payouts | Who bears the conversion | Payee needs an account? |
|---|---|---|---|---|---|
| Payoneer | Fiat network + bank rails | Up to 2% cross-currency withdrawal; 1.50 EUR / 1.50 GBP same-currency withdrawal; batch fees not published | File: up to 1,000 external / 500 Payoneer-to-Payoneer per file | Usually the payee | No, for external bank transfers |
| Wise Business | Fiat multi-currency | Conversion from about 0.2%* against the mid-market rate; one-time account fee | Spreadsheet or API, up to 1,000 payments per batch | Sender, at the mid-market rate | No |
| PayPal Payouts | Wallet | 2% per payout, up to a maximum cap; caps vary by country and by domestic vs international; conversion charged on top | Up to 15,000 payments per API call | Sender pays the fee; conversion extra | Yes, the recipient must log in or create one |
| Deel / Remote (contractor admin & EOR) | Employment + admin layer | Deel: 49 USD per contractor / month, 599 USD per EOR employee / month. Remote: 29 USD per contractor / month, 699 USD per EOR employee / month (monthly billing) | Pays contractors in one run; priced per head | Built into the platform, not itemised | Yes, a platform account |
| Stablecoin rails (e.g. INXY Payments) | On-chain settlement, funded in EUR/USD | Fees from 0.1%, depending on volume, currency and corridor; no setup or monthly fees | CSV file or API | Sender funds in EUR/USD; payee bears their own off-ramp | A wallet address or an exchange deposit address |
*Wise prices differ by country page: 0.23–0.24% on the pages we checked. “From” is the best corridor, not the typical one.
Sources: payoneer.com pricing and batch-payments pages; wise.com/pricing/business and Wise batch payments; paypal.com merchant fees and developer.paypal.com Payouts docs; deel.com/pricing; remote.com pricing; inxy.io. Read 26 September – 6 October 2026.
Where Payoneer is still the better answer
Three cases. They are not edge cases.
Your payees are already inside the network. Payoneer-to-Payoneer transfers skip correspondent banking and typically clear within 7 seconds (payoneer.com, 26 September 2026). If most of your contractors already hold Payoneer accounts because a marketplace put them there, moving them elsewhere means re-onboarding thousands of people to save basis points. The migration costs more than the spread.
You need bank-account reach and the payee should not learn anything new. 190+ countries and 70+ currencies, paid to an ordinary local bank account. No wallet, no exchange, no new app. Nothing in the stablecoin category matches that for a payee who does not want to think about how the money moves.
Your payees receive as well as pay. Freelancers who invoice, get paid by several platforms and hold a multi-currency balance use Payoneer as an account, not as your payout rail. Replacing it on your side does not remove it from theirs.
Bottom line: Payoneer’s cost sits in the conversion legs. It is strongest where conversion is rare, and weakest where every payout ends in a conversion to a local currency.
Wise Business: clean FX, careful underwriting
Wise publishes conversion from about 0.2% against the mid-market rate. Its batch payments take up to 1,000 payments by spreadsheet or API. Recipients get paid into their own bank account in their own currency, and they do not need a Wise account (wise.com, read 26 September 2026).
For a company paying contractors in mainstream corridors, this is the clearest cost structure in this comparison. Reconciling against a published mid-market rate is also easier to defend in an audit than reconciling against a blended rate.
One caveat on the number. “From” is the best case. Conversion into many Asian, African and LatAm currencies costs more. Price your own corridors, not the headline.
Where Wise loses: fit, not price. Wise publishes an acceptable use policy that restricts a number of business types. If your vertical sits close to that list, test onboarding before you build an integration. A cheap rail you lose in month seven costs more than a dearer rail you keep. Wise also runs on bank rails. Where correspondent banking is slow or rejects the destination, the software cannot fix the rail underneath.
PayPal Payouts: a small fee, a costly conversion
PayPal charges 2% per payout, up to a maximum cap. Caps vary by sending country and by domestic versus international payouts. On the US fee page, the USD cap is 1.00 USD per payout, or 0.25 USD through the Payouts API. Currency conversion is charged on top. The sender pays the fee, not the recipient (paypal.com and developer.paypal.com, read 6 October 2026).
You can send up to 15,000 payments in one API call. Per-payment limits are 60,000 USD for registered and 20,000 USD for unregistered recipients (55,000 / 17,000 EUR; 50,000 / 15,000 GBP). Payouts support 24 currencies. Recipients are identified by email, phone number or PayPal ID.
The cap changes the math. Where it applies, the fee on a 4,000 USD payout is a fraction of a percent. The real cost sits elsewhere: currency conversion, and what the recipient pays to move money out of PayPal and into a bank.
Where PayPal loses: the recipient must have a PayPal account, or create one, to get the money. An unclaimed payout is a payout that has not happened. Account holds on the recipient side are a real operational risk, and they never show up in a fee table.
Deel and Remote solve a different problem
Deel publishes 49 USD per contractor per month, 325 USD per contractor of record per month and 599 USD per EOR employee per month (deel.com/pricing, read 26 September 2026). Remote publishes 29 USD per contractor per month for contractor management and 699 USD per employee per month for EOR on monthly billing (remote.com, read 6 October 2026).
These are prices for employment and admin work: contracts, onboarding, tax forms, local compliance and, for EOR, being the legal employer. If you need that, buy it.
But look at the unit. You pay per person, per month, no matter how much you pay that person. On a 4,000 USD monthly invoice, 49 USD is about 1.2%. On a 40 USD affiliate payout, it is more than the payout. Run 2,000 small, irregular payees through a per-head platform to fix a payment problem, and you have bought the wrong product.
Changing the rail does not change anyone’s employment status. Classification depends on control, integration, exclusivity and who carries business risk. It does not depend on the currency or the network of the payment. For digital labour platforms, the EU Platform Work Directive, Directive (EU) 2024/2831, introduces a presumption of employment where the facts show direction and control. The platform has to prove otherwise. Member states must transpose it by 2 December 2026. That date belongs on the payments roadmap, not only the legal one.
Stablecoin rails: what changes, and what does not
What changes: settlement stops depending on correspondent banks. Value moves in minutes, on any day, including to destinations your bank may decline. With a hybrid rail you fund in EUR or USD, and your books never leave fiat.
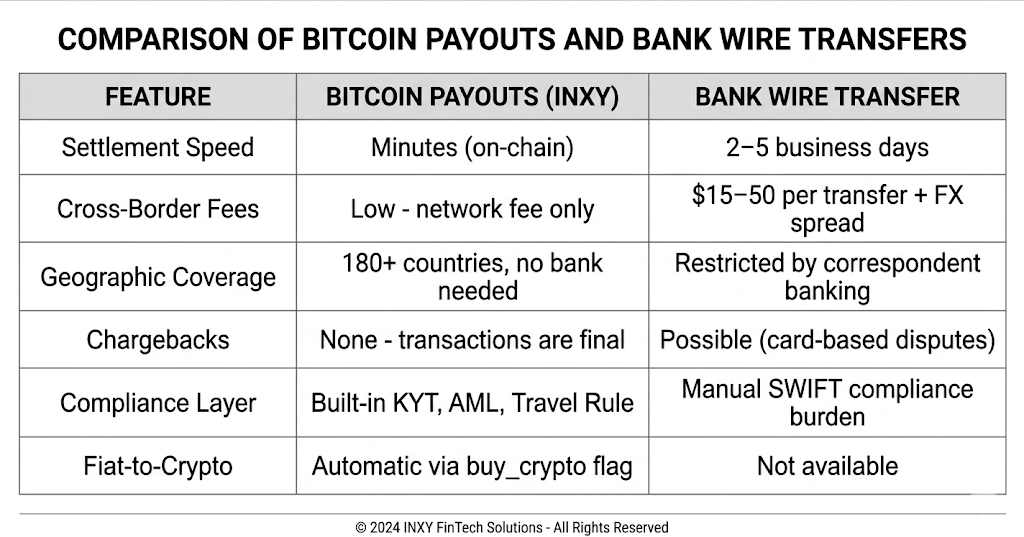
INXY Payments works this way. You fund the payout in EUR or USD. INXY converts and sends USDT, USDC or other supported assets on networks such as Ethereum, Tron, BNB Chain, Polygon and TON. Fees start from 0.1%, depending on volume, currency and corridor, with no setup or monthly fees. Under the hood, each flow is routed to the regulated entity and rails that fit it. You see one account, one balance and one report.
Screening runs before a payout leaves, not after it lands. That covers KYT, sanctions and Travel Rule checks, with Elliptic, Sumsub and Notabene in the stack. The Travel Rule comes from FATF Recommendation 16: originator and beneficiary data travel with crypto transfers. In the EU it is written into Regulation (EU) 2023/1113, with no minimum amount between crypto service providers.
What does not change: the payee still converts. Their local exchange, their spread, their bank’s view of crypto-origin deposits. You have moved the conversion, not removed it. And unlike with Payoneer, you now cannot see it at all. Before you roll anything out, ask a sample of payees per corridor what they net after conversion.
Nor is the rail a default for everyone. BCG and Allium put business-to-individual payouts (contractor pay, creator earnings, refunds and rebates) at about 10% of real-economy stablecoin payment volume. They name strong domestic fiat rails in developed markets, regulation and tax treatment as the brakes (Stablecoin Payments: The Truth Behind the Numbers). Stablecoin rails win where a bank corridor is failing, not because the rail is newer. The mechanics of running one are in our guide to stablecoin payroll, and the wider vendor landscape is in best mass payout platforms in 2026.
What breaks in production
Five failures that show up in month three, not in the demo.
The right address on the wrong chain. Ethereum, BNB Chain and Polygon share the 0x address format, so one address is valid on all three. A payee watching one chain reports a missing payout that is sitting on another. Put the network in the contract and in the batch file. Never guess it from the address format.
The wallet-change email. Shortly before payday, a message that looks like it comes from a contractor asks you to update their payout details. On-chain transfers cannot be recalled. A new address takes effect only after confirmation through a separate, already-verified channel. That rule is the only control you have.
The payday screening hold. KYT flags a recipient address for indirect exposure, and the hold lands on payday. The hold is correct. Screen at onboarding, re-screen before each batch, and decide in advance who resolves a flag and how fast.
Rate drift between preparing and approving. A batch in EUR prepared on Thursday and approved on Monday reprices on a fresh quote. The approver signs a different total from the one the preparer built. Approve on the refreshed quote.
The network fee nobody assigned. Every on-chain payout carries a network fee. Decide in the contract who covers it, you or the payee, and set it the same way in every batch. Otherwise a 500 USDT invoice arrives as slightly less, and someone opens a ticket. See mass crypto payouts for how file and API batches handle fees and statuses.
How to run the evaluation
- Export your last three payout runs. Payee count, ticket sizes, destination countries, currencies. The distribution decides the architecture, and the architecture rules out most of the market.
- Split the file by payout shape. Many small payouts and a few large ones rarely belong on the same rail.
- Ask each payee where the money actually goes: a local bank account, an exchange, a wallet or an existing platform account.
- Price the payee’s leg, not only yours. Sample five payees per corridor and record what they net.
- Ask for the funding-to-execution window. Treat pre-funding as a financing line, not an operational detail.
- Ask how batches run at your volume: file, API or both. Then ask what happens to the other rows when row 14 is rejected.
- Ask what the reconciliation export contains: transaction reference, fiat value at execution, rate used, and fee lines broken out by type.
- Test underwriting early. Name your vertical in the first call, not after integration.
- Run one real batch in parallel with your current provider for a full cycle before you migrate. One month of double fees beats one quarter of clean-up.
Which one, when
| Your situation | The answer |
|---|---|
| Payees already hold Payoneer accounts; moderate volume | Payoneer. Transfers inside the network skip correspondent banking, and re-onboarding costs more than the spread |
| Mainstream corridors; transparent FX is the priority; your vertical onboards easily | Wise Business. From about 0.2% against the mid-market rate, batch payouts by file or API |
| Payees already use PayPal; payouts mostly stay in one currency | PayPal Payouts. The capped fee is low. The costs start when money changes currency |
| You need contracts, tax forms, onboarding or a legal employer | Deel, Remote or another EOR. The rail is not your problem; employment admin is |
| Dozens to thousands of contractors across Asia, LatAm and non-euro Europe; the bank corridor is slow, costly or rejected; accounting must stay in EUR/USD | A hybrid stablecoin rail such as INXY Payments. Corridor reach without handing finance a crypto ledger |
| Payees in the euro area with EUR accounts | SEPA or SEPA Instant. A token adds two conversions and gains nothing |
| Payees in the UK or the US | Usually a domestic bank rail. Both markets have strong local rails, and a stablecoin adds conversions without solving a problem |
| Payees with no reliable local off-ramp | Not a stablecoin rail. You would move cost and risk onto the person you pay, not remove it |
| Mixed base | Two rails, split by corridor. One rail for everyone is a preference, not a requirement |
Start from your own payout export, not from a vendor list. If the rows sit in corridors your bank handles badly, and your finance team needs the ledger to stay in EUR or USD, that is the case INXY Payments is built for. The token mechanics for a USDT-heavy file are in mass payout in USDT. If the rows sit in Frankfurt and Madrid, keep SEPA and spend the time elsewhere.
Either way, bring real data to the conversation. Compare your current payout flow with our team: three months of payout exports are worth more than any pricing page.
This article describes regulatory and market conditions for general information. It is not legal, tax or financial advice. INXY Payments is a payment infrastructure provider, not a law or accountancy firm. Decisions with regulatory consequences should be reviewed by qualified counsel in the relevant jurisdiction.
FAQ
What is the best Payoneer alternative for mass contractor payouts?
There is no single answer, because three different complaints drive the search. If the problem is payee-side conversion cost, compare Wise Business. If it is corridor reach or settlement speed, compare stablecoin rails. If it is contracts and tax admin, you need an EOR or contractor platform, not a payout rail. Diagnose the complaint first.
Does Payoneer charge the sender or the recipient?
Both, in different places. The sending company pays for the payout product; batch fees are not published. The payee pays to withdraw: up to 2% into a different currency, or a fixed 1.50 EUR or 1.50 GBP in the same currency (payoneer.com, 26 September 2026). You will not see the payee’s part.
Can I pay contractors abroad without a local entity?
For genuine independent contractors on a business-to-business contract, yes. No entity is needed to pay them, on any rail. If the people in fact work like employees, you need your own entity or an employer of record, and no payment method changes that. Classification depends on control, integration and exclusivity, not on the rail.
How many payees can I pay in one batch?
It depends on the product and the method. Payoneer publishes up to 1,000 external transfers or 500 Payoneer-to-Payoneer payments per file. PayPal allows up to 15,000 payments per API call. Wise batch payments take up to 1,000. For large, regular runs, an API usually beats file uploads.
Is a stablecoin rail cheaper than Payoneer or Wise?
On the sending side it often is: INXY’s fees start from 0.1%, depending on volume, currency and corridor, with no setup or monthly fees. The comparison is only honest once you add the payee’s own conversion, which no provider quotes. Sample real payees per corridor and compare what they net, not the headline percentages.
Where are stablecoin payouts the wrong choice?
Where payees are in the euro area with EUR accounts, where they are in the UK or the US with strong domestic rails, where they have no reliable local off-ramp, where you pay only a handful of people, or where your real problem is approvals and tax forms rather than the rail. In those cases a bank rail or AP automation is the better buy.